
The Debrief
The Business of Fashion
0
The Debrief is a weekly podcast from The Business of Fashion that goes beyond the glossy veneer of the fashion industry. Hosted by correspondents Sheena Butler-Young and Brian Baskin, it unpacks popular BoF Professional stories. The show covers mega labels, indie upstarts, and the personalities shaping the $2.5 trillion global fashion industry.
Jaksot
-
 Has Fashion Had Enough of AI? 09.09.2026 18minFor many shoppers, fashion is now experienced primarily through a screen — discovered on social media, watched on runway livestreams and purchased from a product photo. Fashion critic Eugene Rabkin argues in his new book that this shift has left the industry prioritising a garment's image over the garment itself, hollowing out creativity and quality along the way. At the same time, as AI generated imagery floods the feed, a counter-movement is emerging: luxury brands are commissioning painters and illustrators, hosting phone-free dinners and building hands-on experiences designed to pull customers back into the physical world.In this episode, senior correspondent Sheena Butler-Young is joined by Diana Pearl, BoF's US Editor, and Marc Bain, BoF's UK Editor and technology correspondent, to discuss whether this renewed emphasis on human creativity and craft is a meaningful response to fashion's image-first culture — or just the next trend cycle.Key Insights:As consumers increasingly interact with clothing through small screens rather than in person, Bain explains that subtler markers of quality have lost their power to communicate value. "As we interact more with clothing through imagery rather than the physical garments themselves, the logo becomes more important... Now the logo is just the easiest thing to identify. And that has become the most important thing on a garment."Drawing on a concept borrowed from French theory, Bain says the gap between a product's online image and its physical reality has left some shoppers disillusioned — a dynamic he says extends well beyond fast fashion. "It doesn't just apply to Shein..Eugene Rabkin's argument is that it's come to apply to a whole lot of fashion, including luxury fashion... There's been this decline in quality over the years."Bain says and Rabkin are careful not to cast technology as the villain, noting that AI's impact depends entirely on how brands choose to use it. " Technology is amoral. It's a tool..And it's really how it's used that is more important."Pearl points to a wave of luxury brands hiring painters, illustrators and sculptors as a direct response to overly polished, perfected imagery that technology has made ubiquitous — a trend only accelerated by AI. e. "Being perfect and having just this picture-perfect imagery is no longer seen as aspirational. It's actually seen as, ‘slop’ … having that human-made art... is what feels now aspirational and special."As brands pull back from influencer-driven content blitzes in favour of intimate, phone-free events, Pearl says the playbook for measuring success has changed. . "It's all representative of this bigger shift that we're seeing away from volume and just get as much content as possible... towards the depth of connection."Additional Resources:Is Fashion Stuck in Its Simulation Era? | BoFAs AI Floods the Feed, Fashion Marketers Tap Artists | BoFLogging Off Is the New Luxury. How Can Brands Adapt? | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 Who's Winning Beauty's H1 Reckoning 02.09.2026 27minBeauty has long been one of the industry’s most reliable growth engines — fragrance boomed post-pandemic, prestige beauty held up better than other categories, and value-driven brands like e.l.f. proved that sharp pricing and marketing could keep consumers spending. But a slowdown that began last year and has only become more pronounced since has challenged that thinking.In this episode, senior correspondent Sheena Butler-Young is joined by BoF senior beauty correspondent Daniela Morosini to unpack the first half's earnings across the beauty conglomerates — from Estée Lauder and Shiseido to L'Oréal, Beiersdorf and E.l.f. — and identify what’s still driving growth and what’s stalling, as well as what investors will be watching for next.Key Insights:Selective Spending, Not Shrinking Wallets: Consumers haven't stopped buying beauty — they've become pickier about where they spend and what they’re purchasing. "People are just getting a little bit more selective," said Morosini. Shopping itself is shifting, too: "Maybe it's not always Sephora and Ulta. Maybe it's TikTok Shop."Skincare Results, Injectables and the Price-Value Equation: Affordable, results-driven skincare brands are outperforming, while medical aesthetics are surging in parallel. Morosini points specifically to "the derm-backed skincare brands or the dermatological brands, the more affordable ones like CeraVe and La Roche-Posay, alongside the growing pull of the lasers and the injectables."Hair's Unexpected Boom: Hair has emerged as one of the biggest bright spots this earnings season, driven equally by innovation and a cultural shift around hair loss. Morosini notes, "hair loss has just become so much more of a hot topic and I think a lot of stigma has been removed," while also crediting brands like K18 and Olaplex that “have increased what we expect hair products to do for us."Estée Lauder's Momentum Question: Lauder posted a 17 percent stock jump on its first results under new leadership, but Morosini cautions the win may be borrowed. "The question is how much has Estée Lauder improved its brand's desirability and how much has it benefited from a rising tide," she says, adding that stripped of Amazon Prime Day effects, US growth was closer to "about two percent."The Danger of the One-Hero Brand: From E.l.f.'s reliance on Rhode to Beiersdorf's dependence on Nivea, this earnings season exposed how a single hero product can mask underlying weakness. "When that's basically all concentrated around one brand, that makes investors a little bit nervous," Morosini says, noting the read-through for M&A: “At a certain point you have to buy the growth."Additional Resources:Beauty Is Growing. Not Everyone’s Benefitting. | BoFCan Estée Lauder Turn a Moment Into Momentum? | BoFBeauty Is Betting on Fragrance. Why Isn’t Shiseido? | BoF Hosted on Acast. See acast.com/privacy for more information.
-
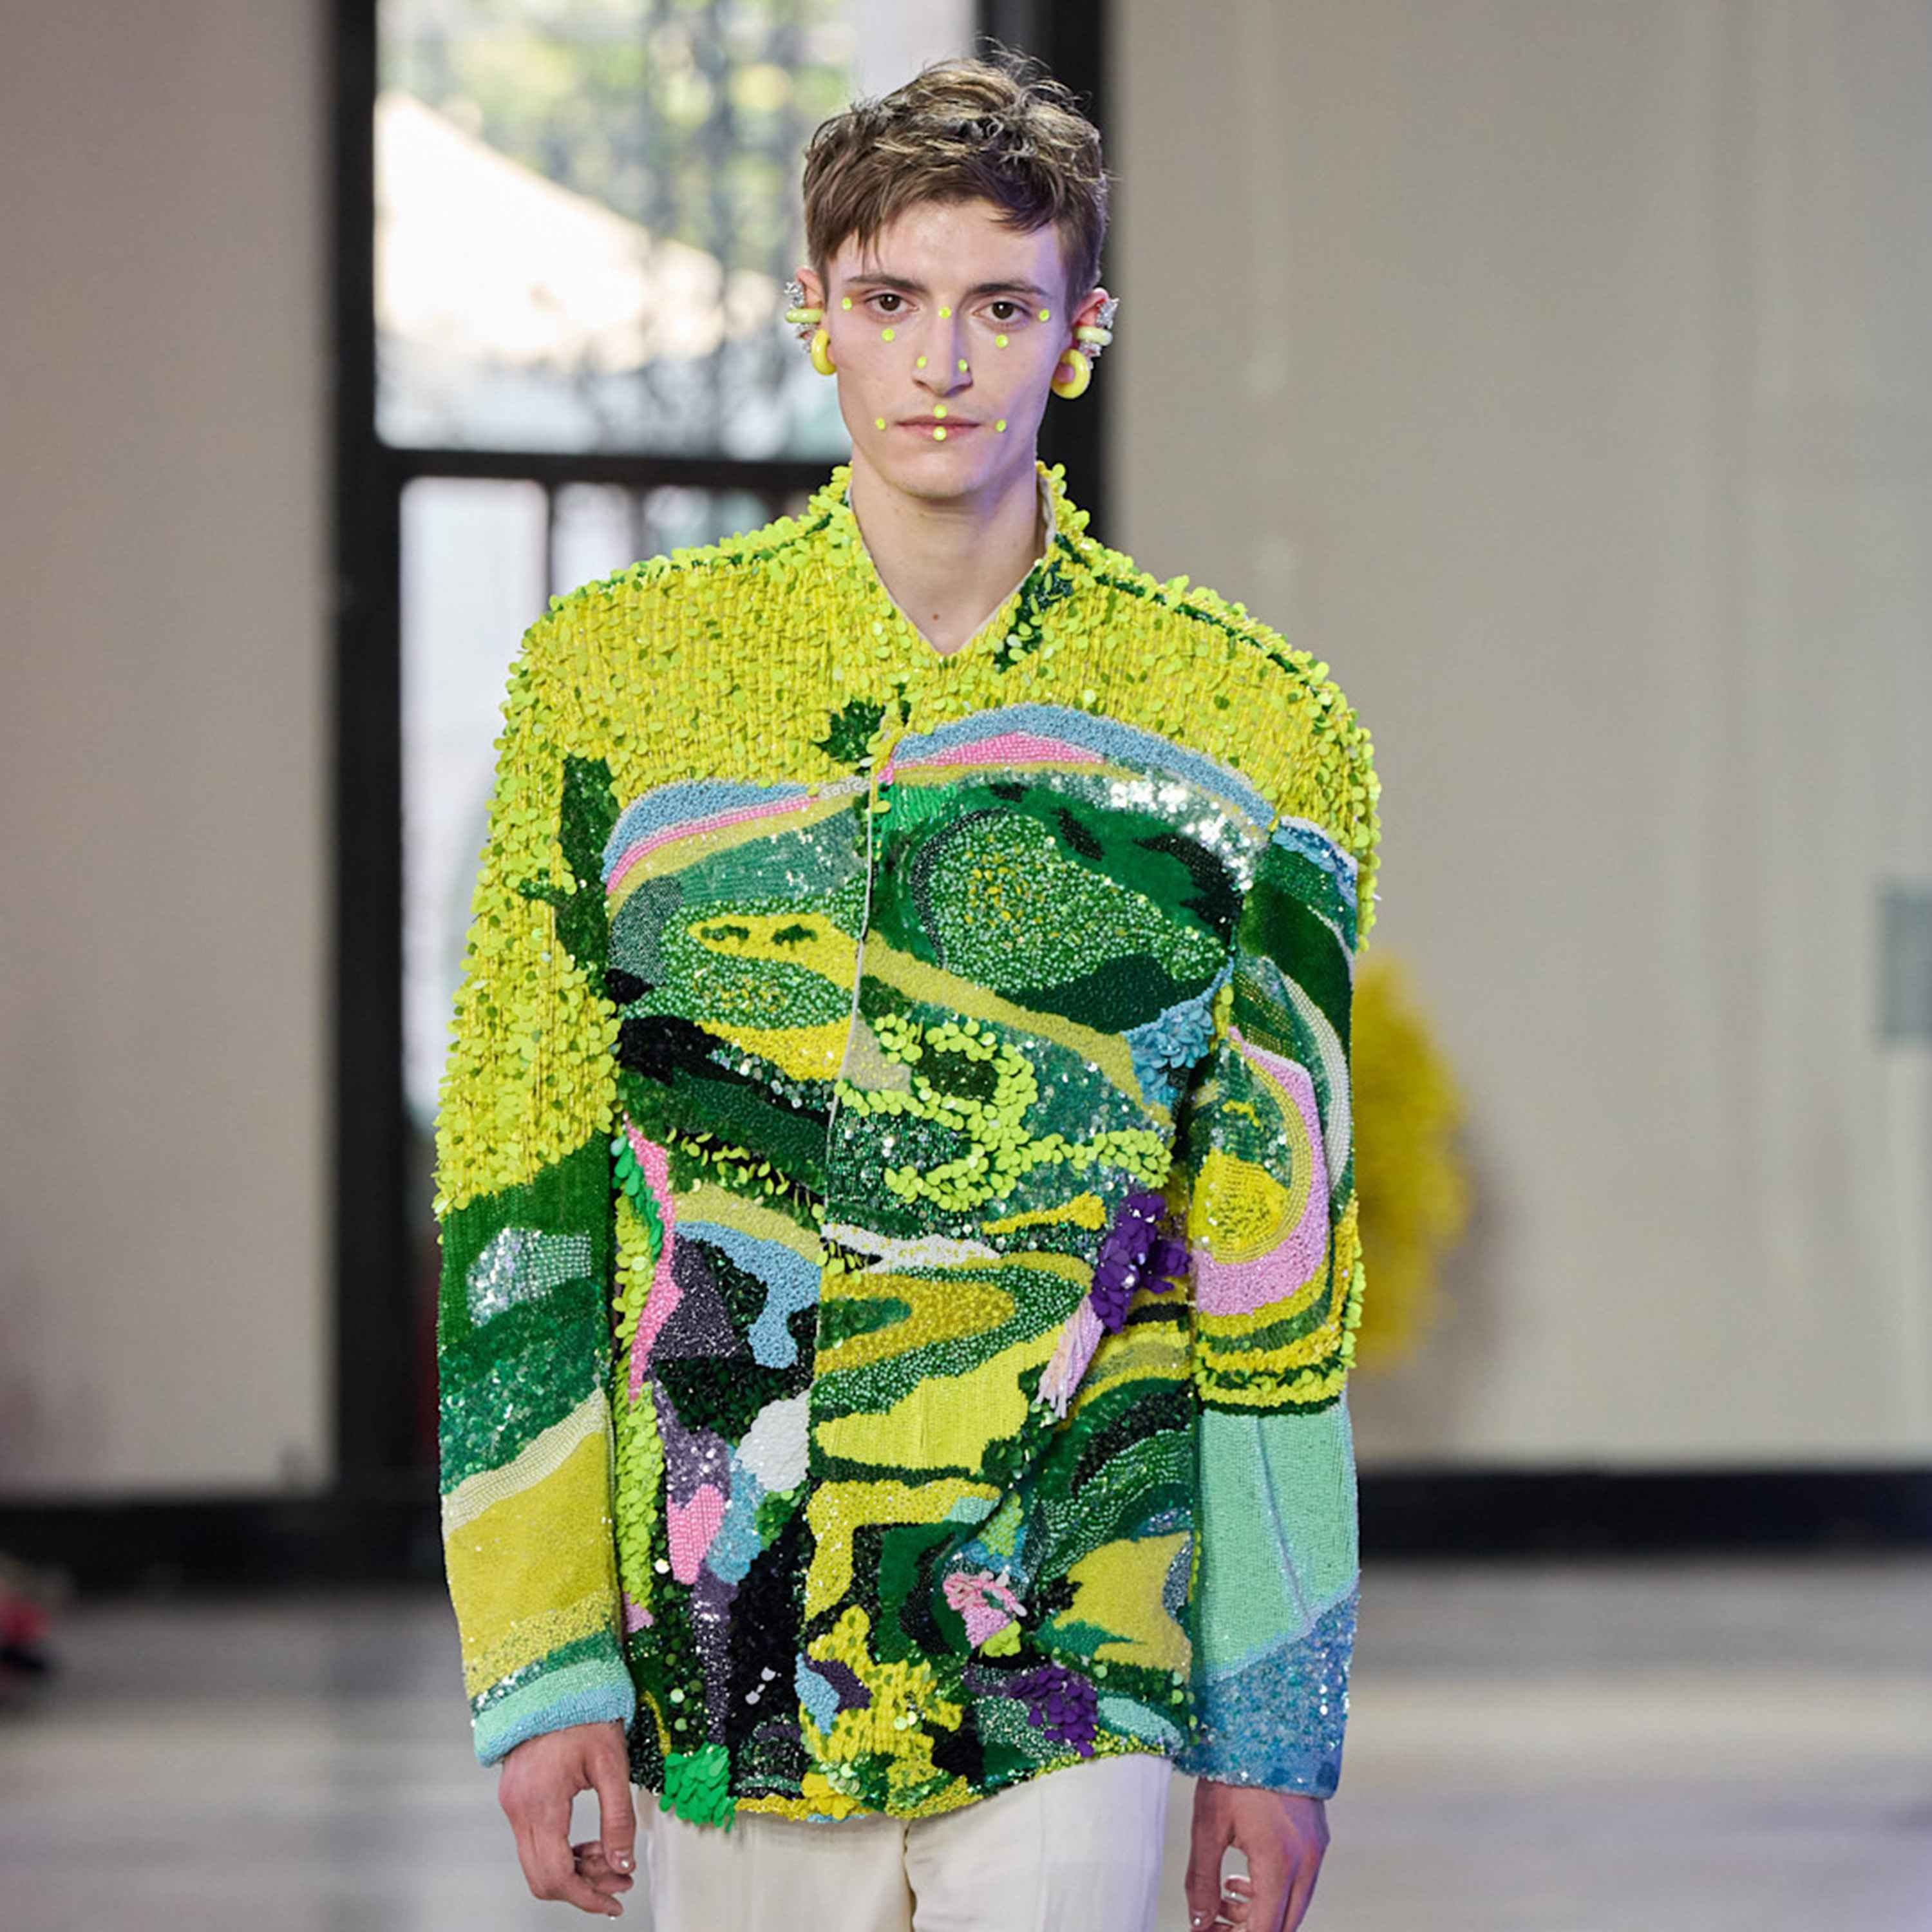 Why Upcycling Is Suddenly Everywhere in Fashion 26.08.2026 28minFor a long time, upcycling sat on the fringes of the fashion industry, a tactic used primarily by small independent designers, niche sustainability labels and in one-off capsule collections. That's changing. At Paris Couture Week this spring, Swiss designer Kevin Germanier closed the season with a collection made entirely from excess inventory across seven LVMH-owned brands. Coach is turning used denim into new bags, and Uniqlo is remaking unsellable and used garments under its RE label.In this episode, senior correspondent Sheena Butler-Young speaks to senior editorial associate Shayeza Walid to explore why upcycling brands are increasingly marketing upcycling through creativity and individuality rather than sustainability alone, and what's really driving the shift from new EU regulations to a changing consumer mindset.Key Insights:Selling Creativity, Not Just Conscience: Walid points to a fundamental shift in how upcycling is marketed. It's no longer framed primarily as an environmental fix, but as a source of design distinction and story. "It felt like the term was becoming ubiquitous across marketing," she says, noting that upcycling has moved from something "relegated to a certain type of consumer or a certain type of brand" to being claimed by some of the industry's biggest names.Regulation Is Quietly Doing the Heavy Lifting: Walid connects the timing of the boom to the EU's ban on the destruction of unsold goods, which came into force in July. She notes that Kevin Germanier's LVMH-backed couture collection was deliberately built from unsold stock, not deadstock fabric — a distinction he emphasised on stage. "It also means that they'll have to figure out sustainable and approved ways for using their excess stock, and upcycling is one of the methods for that."Deadstock vs. Textile Waste — Not the Same Debate: Walid unpacks a live tension among practitioners: using deadstock fabric is being challenged by some critics as not addressing overproduction, since it still puts commercial value on excess production. "With deadstock, it's the same as using new fabric in the sense that they're rolls of fabric... that's not necessarily what upcycling is about," while brands like E.L.V. Denim work directly with used, discarded garments instead.The Infrastructure Is Finally Catching Up: Sorting, collecting and sourcing — the industry's biggest upcycling bottleneck — is improving. Walid cites organisations like Fashion for Good working on AI-assisted sorting, and platforms such as Nona Source and The Materialist connecting brands to deadstock fabric. "There's a greater design interest in it now more than there's ever been," she says of the shift she's tracked through conversations with suppliers.The Consumer Wants Range, Not a Label: Walid argues the audience for upcycled product has broadened well beyond the sustainability shopper. "You could have an upcycled Miu Miu product today, and maybe that says that you like high fashion... but also you think it's cool that your product is from an upcycled material," she says, describing a consumer who wants variety in their closet rather than to be defined by one aesthetic or ethic.Scale Remains the Unsolved Problem: Despite the momentum, there are limits. Sizing and colour inconsistency frustrate wholesale buyers, the process is inherently slower than working with virgin material, and export bans on used textiles in countries like Bangladesh complicate sourcing. She also flags that upcyclers in the Global South — in markets like Kantamanto in Ghana — have done this sort of work for generations but remain largely excluded from the value chain brands are now building.Additional Resources:Why So Many Fashion Brands Are Upcycling | BoFWhy Fashion’s Economics Work Against Sustainable Brands | BoFCan the EU Ban on Destroying Unsold Goods Actually Work? | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 The Influencer Follower-Count Era Is Ending 19.08.2026 23minFor years, follower count was the clearest shorthand for a creator's value — more followers meant more reach, more brand deals, more money. But social media doesn't work that way anymore. TikTok's For You page, Instagram's suggested posts and other algorithmically curated feeds mean creators can reach huge audiences without those people ever following them. At the same time, affiliate marketing platforms like LTK and ShopMy are giving brands a much clearer picture of who actually drives sales, with smaller creators often outperforming bigger names. In this episode, senior correspondent Sheena Butler-Young talks to BoF US Editor Diana Pearl about how brands and creators are rethinking the value of an audience, and where creator value is headed next.Key Insights:A huge following no longer guarantees cultural weight. Pearl points to the gap between raw numbers and actual impact: "You look at someone like Dixie D'Amelio, who has almost 54 million followers on TikTok... but I would not say [she is] as culturally relevant as someone like Alex Earle, who has not even 9 million followers on TikTok."New platforms have made it possible to see exactly who is driving sales, not just who has the biggest audience. As Pearl explains, "ShopMy really changed that — they offer brands a lot more insight into which creators are actually driving sales, even if they're not running a paid partnership."TikTok's For You page and Instagram's suggested posts have done more than any other shift to break the link between followers and visibility. "Those are the two primary factors that have really diminished the importance of follower count," she says, "because you can have someone with 300 followers who goes viral."The single most important quality a creator can build today resists easy measurement. "Trust is the number one most important thing that an influencer or creator can curate today," Pearl says, "and that trust is not something that can necessarily be measured by metrics on a spreadsheet."Chasing every viral trend is a losing strategy — consistency is what builds a durable audience. "Playing the long game is really the best strategy," she says. "Staying true to who you are — that's how you build that community. That is how you built that trust in that community."Additional Resources:Why Follower Count Matters Less Than Ever | BoFNot All Creators Convert. Here's How to Find Those That Do. | BoFFrom Hype to Discipline: The New World of Influencer Marketing | Case Study | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 What the Best Fashion Stores Get Right 12.08.2026 31minFor much of the last decade, fashion brands and retailers were fixated on making shopping as seamless as possible — endless product online, algorithmic recommendations, next-day delivery. But after years of digital sameness, something more analogue is starting to feel exciting again. That shift sits at the heart of BoF's new retail package, The Best Fashion Stores in the World — an insider's guide to 65 independent retailers spanning from Brooklyn's Ven. Space to Dongliang in Shanghai, Alara in Lagos and Dover Street Market. BoF retail editor Cathaleen Chen joins senior correspondent Sheena Butler-Young to discuss why independent retailers are becoming more important to shoppers, brands and the wider fashion ecosystem, as well as why the ritual of engaging with fashion IRL is more important than ever.Key Insights: Chen says the list's three pillars — curation, experience and partnership — were designed to reflect more than consumer taste. Partnership, she explains, addresses "the support and the responsibilities that all retailers have to the fashion ecosystem," at a moment when department stores have earned a track record for not paying vendors and multi-brand retail has been reshaped by the collapse of players like Matches and the struggles of Net-a-Porter.With e-commerce solving for intent-driven shopping, Chen argues stores now win on discovery. As she puts it: "If you know exactly what you want, you shop online. If you don't know what you want, you shop in stores." She adds that the best shopkeepers add value "not just discovery for new brands" but new ways of styling — an eye that "allows designers to sort of view their collection in new eyes" in a way social feeds may fall short, Per wholesale data from the platform Joor, independent retailers' share of transactions rose from 49 percent in 2020 to 62 percent in 2025 — meaning independents "now make up the majority of transactions in wholesale" on the platform, a significant insight even when accounting for the caveat that it reflects one marketplace.The list includes retailers in Ibiza, Hangzhou, Cairo, Cartagena and Kuwait City — a deliberate move beyond fashion's traditional capitals. Citing a conversation with Kallmeyer founder and chief executive Daniella Kallmeyer, Chen notes that regional boutiques may be " even more important than the larger international stores because they're able to penetrate these outer-tier markets," which represent white space for fashion, rather than lesser opportunity.The appeal of independent retail is fundamentally about a different mindset: casual discovery and "bopping around the neighbourhood," which Chen calls "the opposite of online shopping, where I know exactly what I want.”Asked to name the one quality that will define the best stores for the next decade, Chen didn't hesitate: "I think conviction is what makes these doors so special, and ultimately what makes them so successful today" — pointing to Ikram Goldman's boutique, Ikram, in Chicago, and her famously intimate client relationships as the clearest example.Additional Resources:Why Independent Retail Is More Important Than Ever | BoFThe Best Fashion Stores in the World | BoFThe Debrief | Why Some Retailers are Ignoring the Internet | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 The Fashion and Beauty Companies Everyone Wants to Work For 05.08.2026 34minWhat makes a fashion or beauty company a truly desirable place to work? BoF’s second annual ranking of the industry’s most sought-after employers looks beyond brand recognition to examine what workers value — and where companies’ reputations do not always sync up with employee experience. In this episode of The Debrief senior correspondent Sheena Butler-Young speaks with junior commercial writer Eoghan O’Donnell and commercial features editor Dan Hastings about the companies that topped the list, the factors shaping employees’ choices and the challenges facing employers today. They also discuss career development, leadership, workplace stability and how artificial intelligence is changing fashion jobs.Key Insights: The conglomerate stability draw: Amid market volatility, candidates are gravitating toward European luxury conglomerates and beauty giants. Chanel, Hermès and Dior topped the fashion list, while L'Oréal Paris led beauty, ahead of Dior Beauty and Charlotte Tilbury. Their appeal lies partly in perceived stability and career longevity. Founder-led brands including Charlotte Tilbury, Rhode, Victoria Beckham Beauty, Fenty Beauty and Rare Beauty also made the beauty top 20, driven more by product and creative vision than corporate scale.Prestige recruits, it doesn't retain: Iconic brand names remain powerful recruitment tools, but employees consistently rank pay, career progression and company culture as their top three priorities — even as prestige tops their stated reason for choosing a dream employer. The disconnect is measurable: only 28 percent of current workers say their employer's external reputation strongly aligns with their day-to-day experience, and among those who perceive a gap, 80 percent plan to leave within 12 months. "Prestige attracts talent, but it's not necessarily what retains it," says O'Donnell. The ivory tower effect: Of all cohorts surveyed, C-suite and HR respondents were the least likely to say their employer's external image differed from internal reality — the group best placed to close that gap is often the most disconnected from it. A Glassdoor and Indeed review analysis (December 2024 onward) of the top 10 companies in both rankings surfaced consistent complaints about workload, benefits, and disconnects between store-level management and headquarters. "There is a [difference] between having a prestigious brand name and working for a brand that doesn't necessarily deliver a healthy workplace," says O'Donnell. "The generational AI divide: Sentiment on AI splits sharply by seniority, not by digital fluency. Workers over 40 are the most AI-optimistic cohort — not Gen Z, as employers might assume — while 39 percent of fashion workers and 35 percent of beauty workers say they want AI training they haven't received. A small but notable share admitted using AI at work without disclosing it to their employer.The "job lock" threat: Many employees are staying in roles for economic security, not satisfaction. "We know that some employees are staying in roles because of economic uncertainty rather than that sense of genuine satisfaction," says O'Donnell. Hastings sees the same pressure building from the other direction: "I don't think [Gen Z] are willing to sacrifice their [salary], paying the rent, and eating on the altar of working for a prestigious fashion or beauty company — and that will create a lot of friction within the industry."Women's health is the next battleground: In survey responses skewing majority-female, respondents voiced urgent, largely unmet demand for egg freezing, menstrual leave, and support through perimenopause and menopause — benefits nearly absent from current employer offerings in two female-dominated industries.Additional Resources:The Most Desirable Beauty Companies to Work for in 2026 | BoFThe Most Desirable Fashion Companies to Work for in 2026 | BoFThe Debrief | Making Sense of Fashion’s Brutal Job Market | BoF Hosted on Acast. See acast.com/privacy for more information.
-
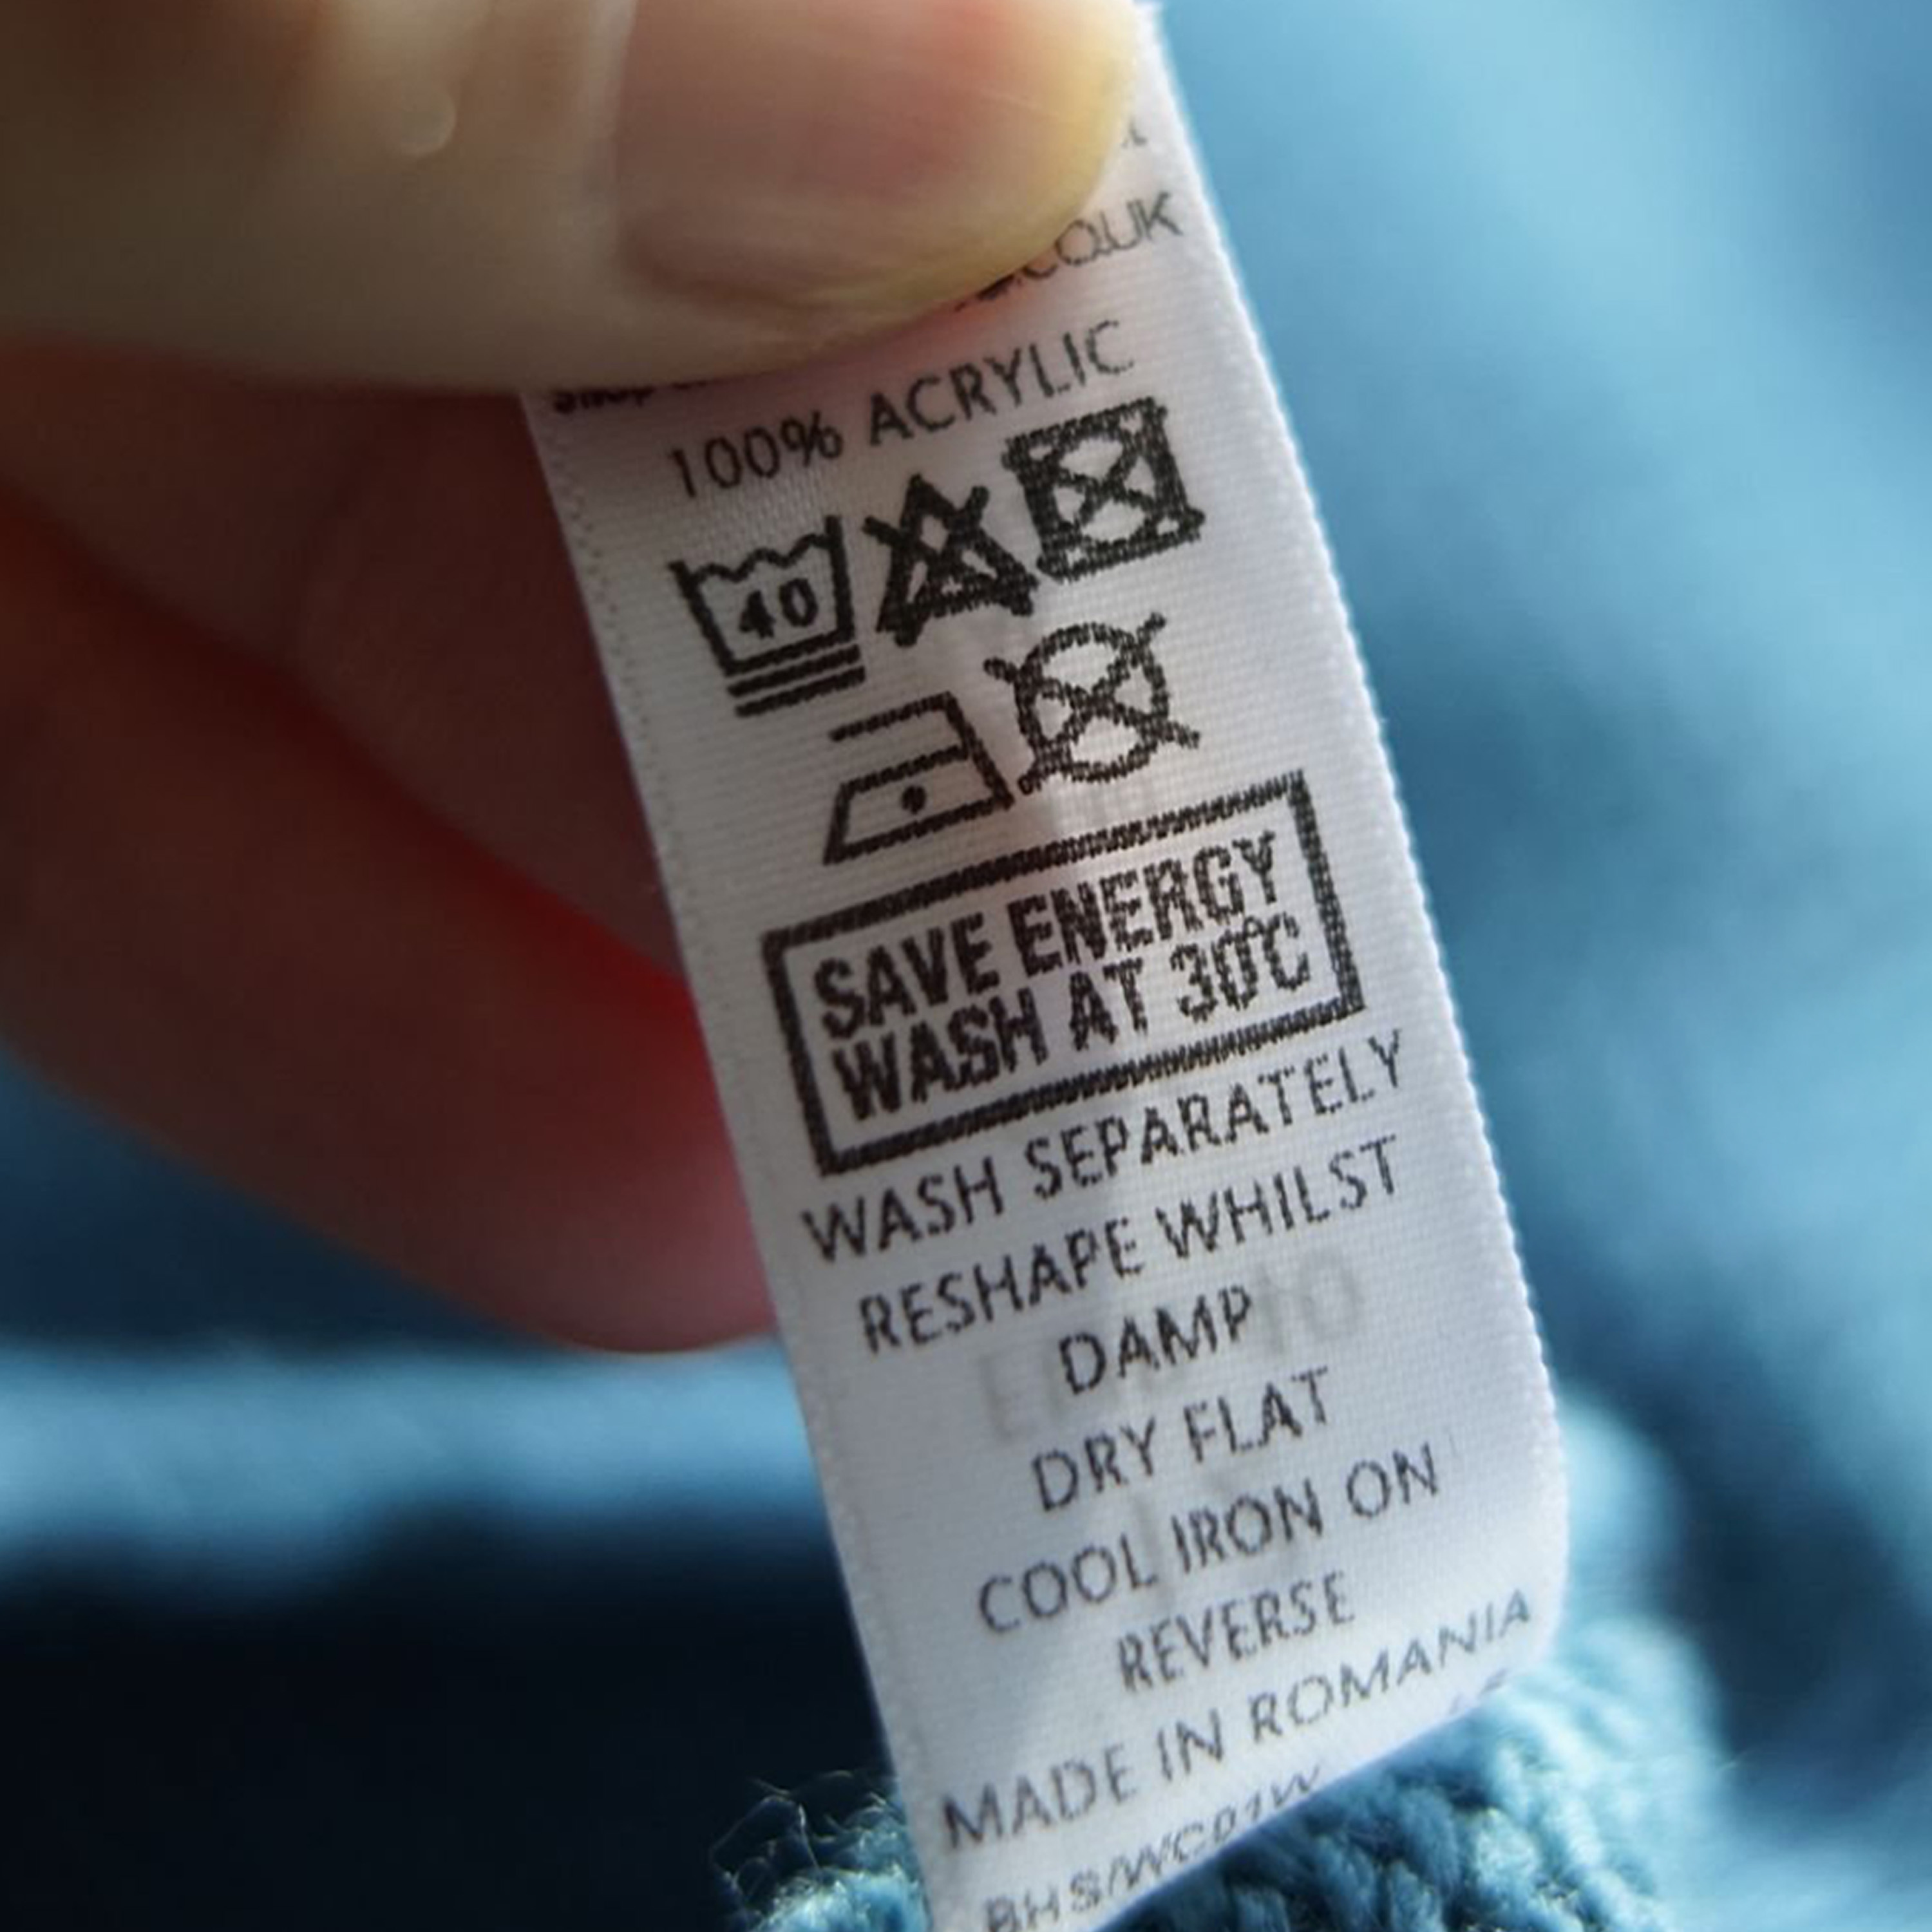 Why Everyone's Reading Clothing Labels Again 29.07.2026 30minFabric content used to be a niche sustainability conversation. Now it's a mainstream health one, driven by the same scrutiny shoppers already apply to what they eat and put on their skin — searches for "natural fibre" are up over 100 percent in five years, and searches for "what is viscose?" have climbed roughly 5,000 percent in the US over the same period. Gap found out just how fast that shift can turn into backlash when its nostalgic Zac Posen knit drop — 80 percent polyester, 20 percent elastane — drew comparisons to fast fashion within days of launch, despite carrying a premium, above-$100 price tag.In this episode of The Debrief, Sheena Butler-Young and Shayeza Walid unpack why natural fibres have become a health obsession rather than a values debate, why "natural" doesn't automatically mean sustainable, and whether polyester can ever really be dethroned.Key Insights: Health Is the New Driver: The conversation used to centre on durability and value; now it's about wellness. Walid explains that shoppers are "instead of just talking about durability and value... starting [to go] more into this health conversation," adding that clothing has become "this final frontier" for the same scrutiny people already apply to food and skincare.Gap's Zac Posen Knit Became a Cautionary Tale: The backlash wasn't really about one sweater — it was about price and expectation. Walid notes the item retailed above $100, so "the disappointment was... doubled down on by the fact that this is supposed to be like a premium level of Gap." As she puts it, "people are [now] associating price with natural fiber."Natural Doesn't Automatically Mean Sustainable: Walid is blunt that the "natural equals good" framing oversimplifies things: "natural does mean that it might have a higher carbon footprint," she says, pointing to methane from grazing cattle for wool and the water intensity of cotton. Her summary: "anything that's derived from nature... naturally has a higher environmental footprint because it's from the earth."Different Generations, Same Shift: Motivations diverge by age, but the direction is the same. Gen Z shoppers are driven by "value signaling" around climate, Walid says, while older shoppers are asking "how can I live a healthier, better life?" Her takeaway: "you're seeing it across different age brackets, but the end result is this shift."Polyester Isn't Going Anywhere Soon: Despite the backlash, Walid says synthetics remain entrenched, especially in performance wear. "It's cheap... it is subsidized by... the oil lobby," she says, and its "malleable qualities are so unique to itself that it's very difficult to replace." Bio-based elastane is emerging, but only at pilot scale.Additional Resources:Why Consumers Are Ditching Polyester for Natural Fibres | BoFSustainable Fashion’s New Marketing Angle Is All About Wellness | BoFWool Workout Clothes? The Demand Is Growing | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 Is Fashion School Still Worth It? 22.07.2026 32minFor decades, institutions like Central Saint Martins, Parsons and Institut Français de la Mode have launched some of fashion's most successful careers. But, today's graduates are entering a more competitive industry grappling with slower growth across the board, where AI is changing how work gets done and employers are reassessing the skills they need. This week, BoF Careers features editor Dan Hastings joins Senior Correspondent Sheena Butler–Young to examine how fashion education is evolving alongside a rapidly changing industry — and whether those changes are enough to prepare students for today's job market.Key Insights:Fashion graduates are entering a far more competitive industry. With thousands of graduates competing for a limited number of entry-level roles, breaking into fashion is arguably becoming even more difficult than it was just a decade ago. According to UCAS data, the UK alone now offers over 200 bachelor's-level fashion courses, with cohorts running from single figures up to roughly 50 at institutions such as Central Saint Martins and the London College of Fashion. That points to close to 5,000 new fashion design graduates a year, entering a job market that, in Hastings's words, “is not ready for that number of young graduates” — and competing not only with each other but with the backlog of graduates from previous years who haven't yet found work.Financial barriers persist. Despite some progress, Hastings describes many fashion students continuing to work unpaid internships to gain much-needed experience while struggling to afford tuition, housing and other college expenses. It’s structure that, he says, often “excludes people from working-class backgrounds, even if now they have access to fashion degrees.” UK student loans widen access to the degree itself, but not to the unpaid work experience that increasingly follows it.Prestige still opens doors. Hastings says some of fashion's most prestigious schools continue to offer a route into the industry's most sought-after roles—but not because of the name on the diploma alone. Their value lies in the combination of rigorous creative training, selective programmes and sustained access to industry professionals. As examples, Hastings points to schools like La Cambre in Brussels, whose highly selective programmes and graduate shows, he says, continue to attract attention from leading luxury brands and recruiters. He also highlights institutions like IFM in Paris, where close industry ties and scholarship support help connect students with the wider fashion ecosystem. As Hastings puts it, "when you have a foot inside the door, you can really connect with really amazing people."Additional Resources:Paris' New Super-School Aims to Rival Central Saint Martins | BoF How Fashion Schools Court Industry Talent | BoFHow Fashion Schools Are Tackling AI’s Blind Spots | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 The Anti-Unicorn Playbook That Beat Fashion's DTC Boom 15.07.2026 26minIn 2016, the global retail landscape was dominated by successful direct-to-consumer (DTC) disruptors like Everlane, Glossier, Allbirds and Outdoor Voices. Backed by hundreds of millions of dollars in venture capital, they prioritised rapid sales growth and hyper-aggressive social media customer acquisition over immediate profitability.In this episode, senior news and features editor Diana Pearl joins senior correspondent Sheena Butler-Young to explore why the once-dominant DTC formula ultimately unravelled — and how a quieter, lesser-scrutinised class of brands, such as Doên, Hill House and Staud, built more durable businesses by taking a different path.Key Insights: A faltering DTC playbook faltered : IIn 2016, fashion's direct-to-consumer boom was fuelled by venture capital. Well-funded startups spent heavily on creative agencies, polished brand identities and social media advertising in pursuit of rapid growth, while largely rejecting wholesale. But as customer acquisition costs climbed and digital marketing became less effective, many brands discovered that bypassing traditional retail wasn't the sustainable advantage it once seemed. Brand before scale: Having a strong aesthetic is key to the equation. . “Being very defined with your aesthetic and your point of view, you can then take that and apply it to a bunch of different categories,” says Pearl Direct consumer selling can be a good way to control brand identity but wholesale remains a critical avenue for brand awareness and discovery. 'It’s not that direct- to-consumers can't work, you just need to build up that brand identity,” says Pearl. “I think a lot of these big 2016 names went wrong by raising so much money without [the brand identity].”The value of being small and growing slow Limited capital forced many of these brands to stay disciplined with inventory, giving them time to understand what customers actually wanted before making bigger bets. While frequent sell-outs weren't ideal, they were often less damaging than excess inventory that required markdowns and eroded profitability. The result was a stronger feedback loop between brands and their customers and quicker pivots.“When products sell out, you get to see what your customers are really resonating with versus if you're just advertising on social media in order to grow sales,” says Pearl. Community over customer acquisition : Rather than relying on expensive paid marketing, many of these brands built loyal followings through authentic relationships with creators and customers. Early influencer partnerships grew alongside the brands themselves, creating trust and awareness that proved more durable than simply buying reach through social media advertising. “Additional Resources:For These Brands, Resisting the DTC Playbook Paid Off Glossier’s New Strategy: Fewer Stores, Fewer Products The ‘Nap Dress’ Propelled Hill House to $110 Million. What’s Next? Hosted on Acast. See acast.com/privacy for more information.
-
 Luxury’s New Reality 09.07.2026 31minLuxury's post-pandemic boom is over. Growth has slowed, shoppers are pushing back on years of price increases and many brands are struggling to convince customers they're still worth the premium. Drawing on BoF's 2026 State of Luxury report — which includes a survey of more than 2,000 affluent consumers in the US and China, alongside interviews with industry leaders — BoF editors Mimosa Spencer and Robert Williams explore what's driving luxury's reset and what it means for brands.They unpack why heritage, craftsmanship and logo power are no longer enough to justify premium prices on their own, and why emotional connection, creativity and exceptional retail experiences have become increasingly important to today's luxury shopper. They also discuss what brands need to do to rebuild excitement, restore value and win customers back.Key Insights:Emotional Matters More Than Heritage: Craftsmanship, heritage, and logo power are still important, but they are increasingly seen as table stakes rather than the ultimate selling point. After years of price increases, luxury shoppers are looking for brands that spark excitement, feel culturally relevant, or offer a more meaningful emotional connection. As Spencer explains, this shift is deeply tied to a broader consumer weariness: "Luxury fatigue has been a real problem. Shoppers are tired of price hikes. They're tired of things costing more when... the product hasn't actually changed." Luxury Shouldn’t Feel Like a Chore: Luxury brands once built exclusivity through long queues, appointment-only access, and other barriers to entry. Today, shoppers expect premium service to feel effortless, requiring brands to balance accessibility for aspirational consumers with absolute privacy for Very Important Clients (VICs). The traditional mechanics of high-end retail are fast becoming liabilities; as Spencer observes, "Once you've peaked somebody's interest, you've gotten your audience, you want to be able to serve them right away. Don't make them go through hoops. Don't let them wait in line. None of that is appealing anymore."Different Meanings in Different Markets: While emotional connection remains key across both major economic engines, how that plays out is heavily influenced by geography. In China, luxury consumption is closely tied to external self-expression and social recognition—even through understated "quiet luxury". In the US, shoppers are more likely to prioritise personal taste, self-reward, and alignment with a brand's values. Explaining this cultural divergence, Williams notes that "historically there is a stereotype that conspicuous consumption and very obvious signifiers of luxury are what are gonna perform much better in a country like China, [but] you have a really strong success for certain brands there that have a much more discreet or understated approach."Navigating the Spectator Divide: Luxury brands are increasingly catering to two distinct groups: transactional store clients who buy products, and digital audiences who engage with brands strictly through fashion content. The challenge is turning online attention into meaningful retail engagement without losing either audience. This structural shift requires brands to balance commercial conversions against the growing weight of pure spectatorship. As Williams notes, "There is a real issue in fashion right now with spectatorship and the idea that lots of people are just as happy to consume images of fashion than to actually go buy it. We're compulsive consumers of imagery in our culture today."Additional Resources:The State of Fashion: Face-to-Face with Luxury Clients | BoFChanel’s Bruno Pavlovsky on Reengineering an Iconic Brand | BoFHaute Couture and High Jewellery Take the Paris Stage | BoF Hosted on Acast. See acast.com/privacy for more information.
-
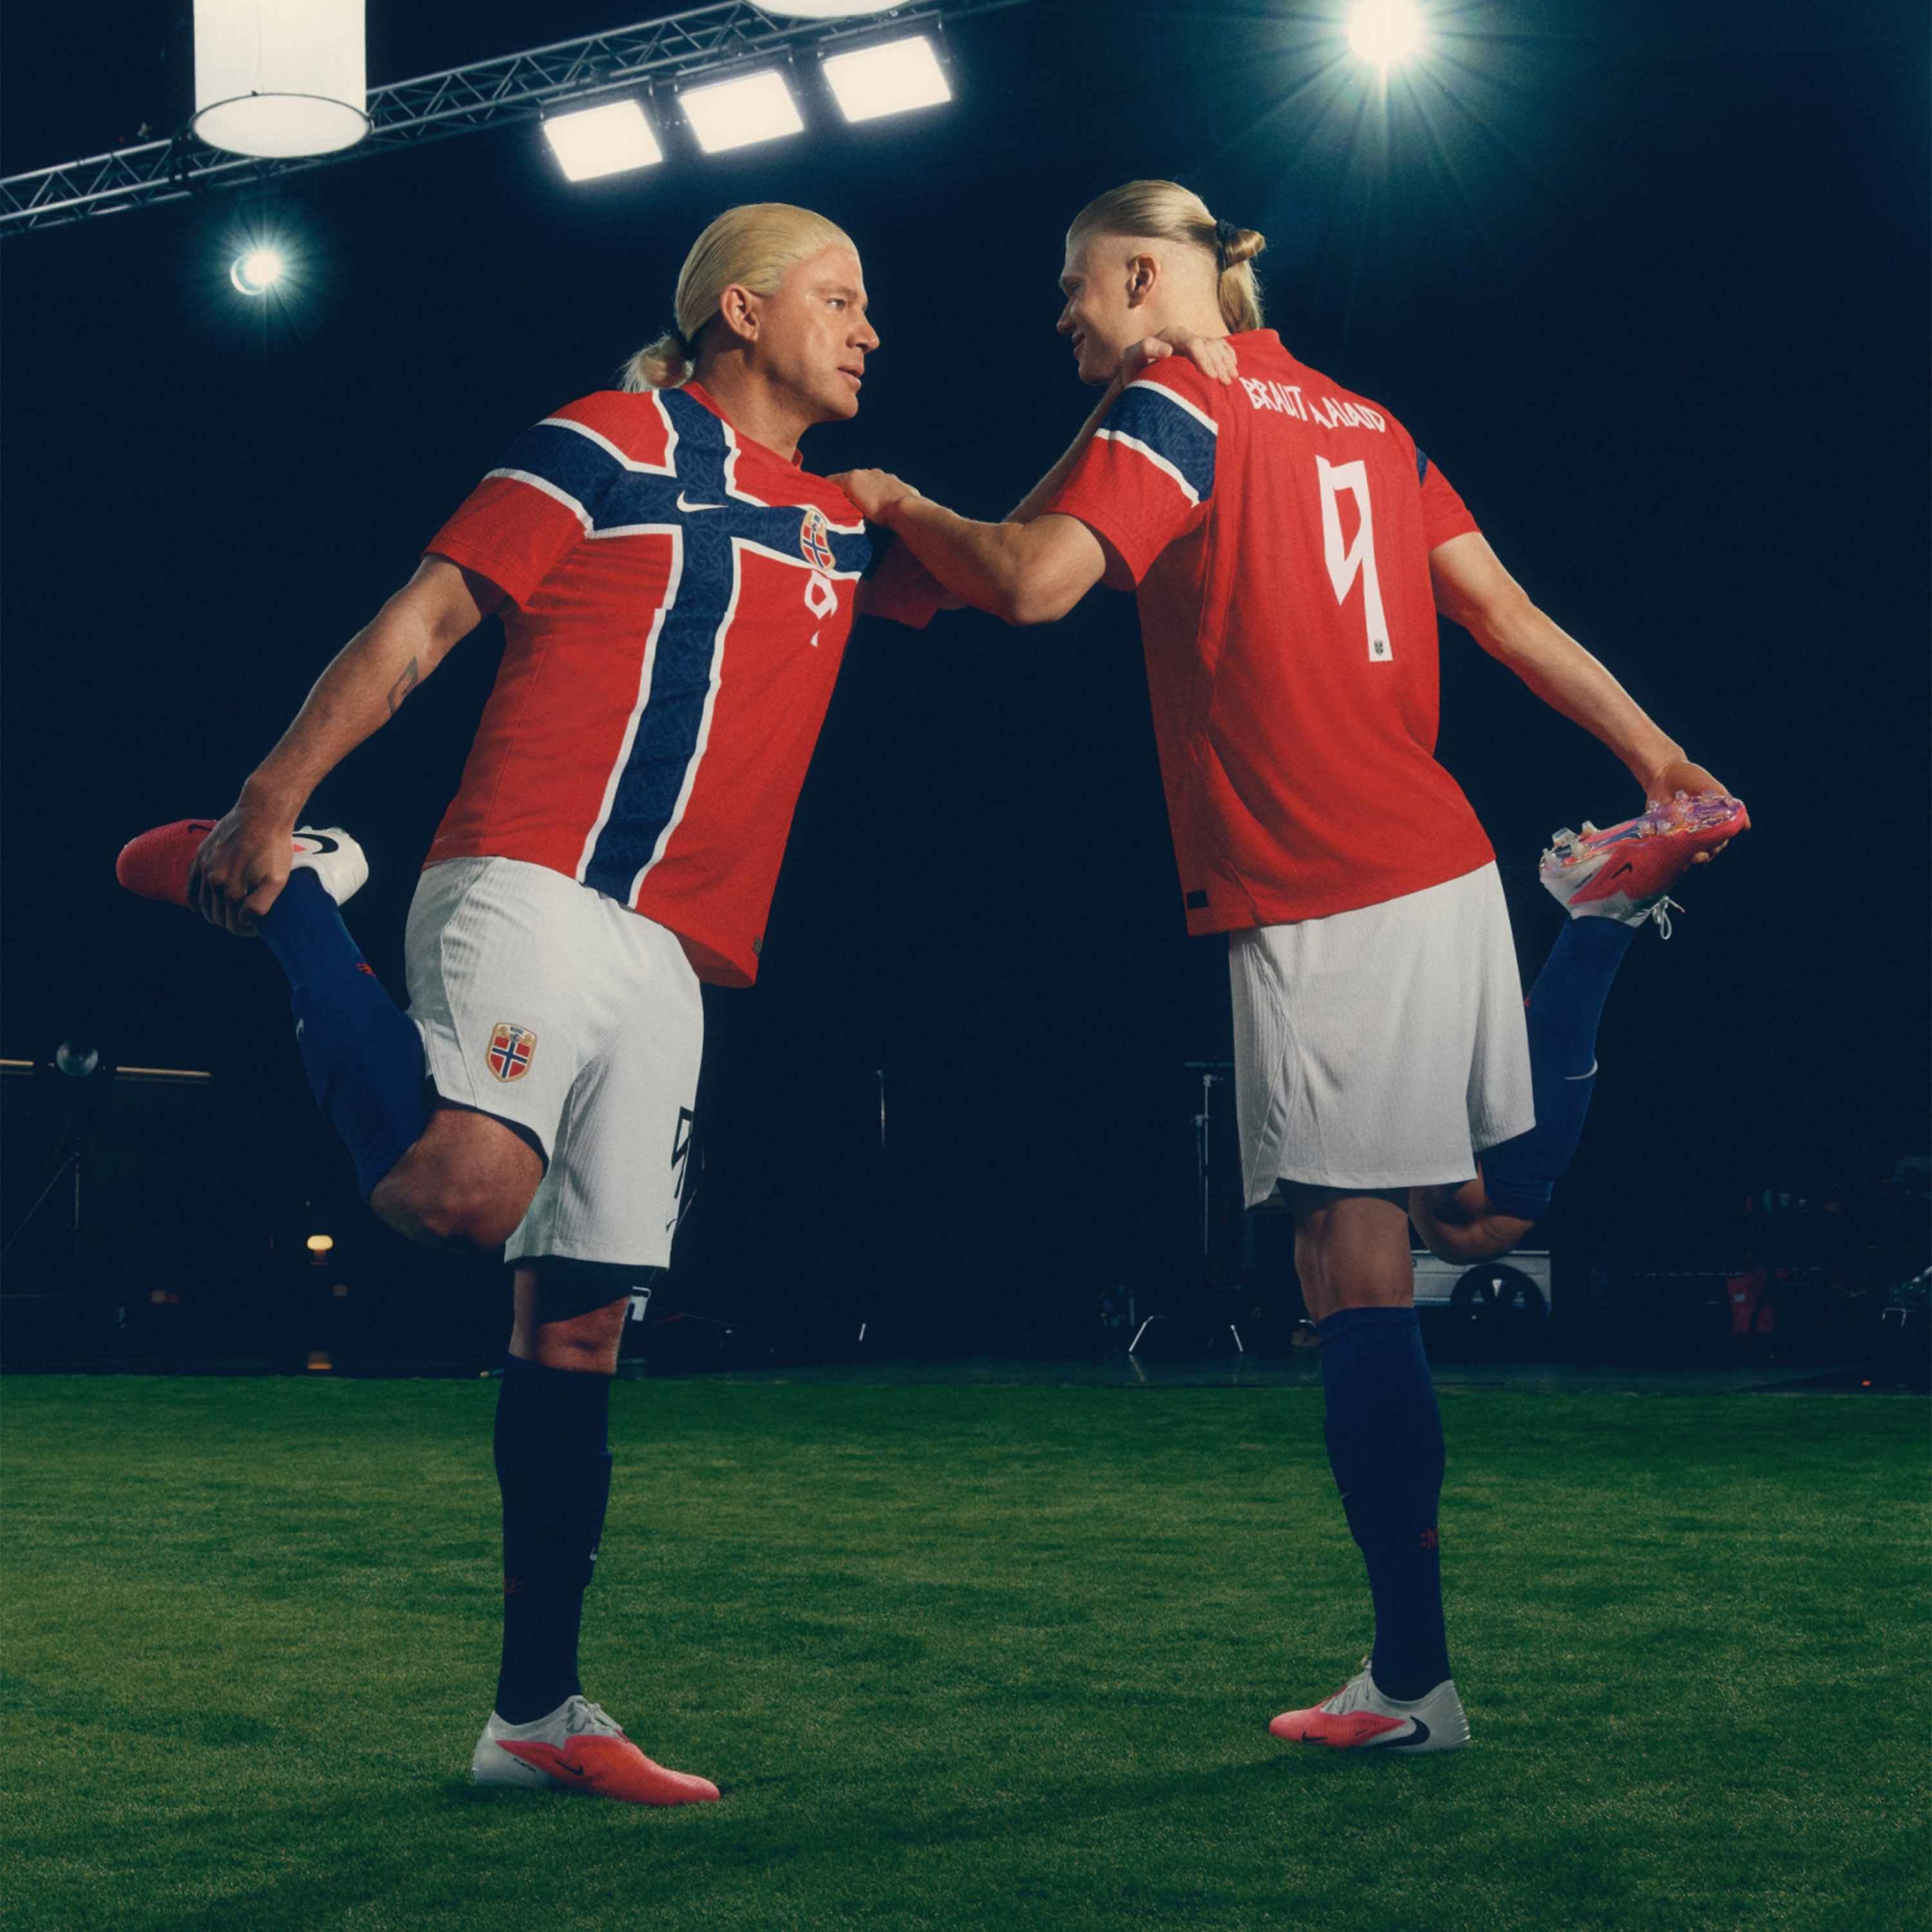 How Nike Built the Biggest World Cup Campaign Ever 01.07.2026 48minThe 2026 World Cup marked an unprecedented milestone for global football, expanding to 48 teams playing over 100 matches across the US, Canada and Mexico. In this special episode of The Debrief, Nike’s vice president of global brand management Helena Thornton joins BoFsenior correspondent Sheena Butler-Young and sports and fashion correspondent Mike Syke to discuss the strategy behind the brand's World Cup campaign, the expansive relationship between football, culture and commerce and what the tournament means at a pivotal moment for Nike.The episode examines how Nike approached the sport's biggest stage, from the creative thinking behind its 'Rip the Script' campaign — which brought together elite athletes, pop culture figures and cinematic storytelling — to the challenge of building campaigns that resonate in an increasingly fragmented media landscape. Thornton also reflects on how the World Cup fits into Nike's broader brand strategy as the company works to regain brand heat.Key Insights:Breaking beyond football fans requires becoming part of the broader cultural conversation. As brands compete for attention with creators, entertainment and other cultural forces, Nike designed its World Cup campaign to extend beyond the sport itself, bringing together elite footballers, athletes and cultural figures to appeal to both dedicated supporters and more casual fans. “Including the sort of that celebrity class alongside the elite footballers and the athletes, because I think that speaks to the more casual fan,” Thornton says. Long-term community building matters more than tournament marketing alone. Thornton says major sporting events should serve as a catalyst for brand storytelling and momentum rather than the entirety of the brand’s strategy. You don't ever just want to be the shiny object that drops in for the weeks of the tournament and then you leave,” she says. “We really want to make sure that people have unbelievable access to the game... that moment actually really ignites this huge love of the game.” Grassroots investments, like Nike's ‘Toma’ platform, the street football movement, help build deeper consumer relationships than short-lived tournament campaigns.Nike built its campaign around athlete instinct rather than a traditional sports marketing playbook. Rather than relying on rigid creative formulas, the brand grounded 'Rip the Script' in conversations with professional footballers, embracing emotion, authenticity and intuition as the foundation for the campaign. “We spoke to hundreds of footballers who kept telling us the same thing,” Thornton explains. “They were … just a bit sick of people telling [them] what to do... ‘we just wanna trust our gut.’” Football creates moments of connection that few cultural platforms can match. The World Cup's global reach made it more than just a sporting event, creating a shared cultural moment at a time when people were looking for connection and optimism. “There's just a passion about the sport…there is just this larger unity right now that I'm seeing from people,” Thornton says. “I think the world just needed this thing to bring us all together and there is no other sport other than football really that truly, truly is the global game.” Innovation remains central to Nike's broader turnaround strategy. While campaigns like 'Rip the Script' are among the brand's most visible expressions, Thornton says major sporting moments bring together teams across the company to think beyond marketing. “We sit down across all of the different departments at Nike and we talk about these big sports moments, ‘what do we wanna do to totally change the industry again? What is the athlete problem that we're solving for? What innovation can we push to allow an athlete to do something they never even believed that was possible?’”Additional Resources:Nike and Adidas Are Taking the World Cup to the Street The Strategy Behind Nike’s Colossal World Cup Bet Nike’s World Cup Takeover Is Off to a Hot Start Hosted on Acast. See acast.com/privacy for more information.
-
 Why Activewear Consumers Are Looking Beyond Lululemon 24.06.2026 24minFor more than a decade, activewear shoppers largely looked to Lululemon and Nike. But as the post-pandemic boom cools and growth becomes harder to find, a new crop of brands is gaining traction.Smaller labels like SetActive, 437 and Oner Active aren’t reinventing activewear. They’re winning customers through social media, creator-led marketing and a deep understanding of today’s fitness culture where consumers move fluidly through workouts like pilates, Hyrox and tennis on any given week. In this episode of The Debrief Podcast, retail editor Cathaleen Chen joins senior correspondent Sheena Butler-Young to discuss why these newer brands are resonating, whether their momentum is sustainable, and what their success reveals about the challenges facing industry leaders Nike and Lululemon. Key Insights:The era of Lululemon as a status symbol may be ending. "Lululemon in the past two decades effectively cornered the market on activewear as a status symbol," Chen says. "I do think the era of Lululemon as a status symbol is ending ... if you're not going to be a status symbol, what will you be?"Consumers are craving something new. The rise of brands like Set Active, 437 and Oner Active is being driven less by breakthrough product innovation than by a broader desire for novelty. "The answer that I got overwhelmingly from my reporting is that, honestly, we are just in this moment of desire for newness," Chen says. "People were like, ‘okay, I have Lululemon in my closet, what's next?’"Founder-led social media is helping challengers compete. Rather than relying on big marketing budgets, many emerging brands are building audiences through creator-style content — from behind-the-scenes glimpses into product development to founders who function as influencers in their own right. "What they have done incredibly well is build organic followings on social media and be able to capitalise on certain TikTok trends," Chen says. “They have the benefits of … the founder coming in every day, trying on the products herself... it makes a big difference in being visible to the customer”. Activewear is entering its own version of the indie beauty era. As consumers build wardrobes around multiple activities rather than a single sport, the category is becoming more fragmented and open to new players. "What's happening in activewear is very similar to what happened in beauty a few years ago," Chen says. "Where the category was dominated by a handful of brands … but we reached this inflection point where people want something that feels new."Additional Resources:The TikTok-Savvy Activewear Brands Stealing Market Share Why Every Fashion Brand Thinks It’s a Sportswear Label Now The Reign of Leggings Is Over. What’s Next? Hosted on Acast. See acast.com/privacy for more information.
-
 How Books Became Fashion’s Latest Status Symbol 17.06.2026 25minFashion’s book obsession is no longer subtle. What started as the occasional literary reference has become a broader wave of book clubs, salon-style events, campaign imagery and products designed to signal that a brand — and its customer — has cultural depth. It’s all happening as reading rates are declining, but the image of the reader has never looked more fashionable. This week on The Debrief, BoF reporters Haley Crawford and Shayeza Walid explain how books became fashion’s latest flex, and when the trend starts to look less like culture and more like marketing.Key Insights: Books have become fashion’s new status symbol: Literature has always inspired fashion, but both reporters argue the relationship has become far more explicit. “We felt like books were being productised by fashion itself,” says Walid. In a world saturated by digital content, books now function as markers of cultural literacy and intellectual identity. As Crawford puts it: “You actually have to take the time to read a book from cover to cover. Fewer people are doing that today, so it is more of a flex to have read the book and actually understand the reference.”TikTok is fueling an analogue revival: Ironically, fashion’s literary turn is being accelerated by social media. Online subcommunities like BookTok have transformed reading into a visible identity and community marker for younger consumers. “Social media, the stores, the products you’re buying and this analogue signalling, are all coming together,” says Walid. “ I don’t think this is happening in a silo. I think it’s very interconnected to other forms of analogue connection that people are finding nowadays.”Not every literary collaboration resonates equally: Both reporters argue that the strongest examples are those rooted in genuine engagement with literature rather than surface-level branding. Crawford points to Prada’s collaborations with authors and literary scholars as examples of brands building deeper cultural worlds. Walid highlights Chanel’s funding of a library at a Shanghai art museum. “It was actually creating or funding something which allowed people to engage with books and literature,” she says.The trend risks losing its cultural power: Fashion using books as a cultural signal is likely to lose some potency if every brand adopts the same strategy. “The ones that have been doing it for quite some time will continue to do so. But those that have maybe slapped a book name on a T-shirt or created a book tote might see less success,” says Crawford. “The second consumers start noticing the corporatisation of this trend, it is going to start to become stale,” adds Walid.Additional Resources:How Books Became Fashion’s Favourite Flex | BoFWhen Taste Is All Over TikTok | BoF Hosted on Acast. See acast.com/privacy for more information.
-
 Fashion's Ozempic Reckoning 10.06.2026 31minThe rise of GLP–1 drugs, such as Ozempic and Wegovy, is forcing fashion and beauty companies to rethink everything from sizing and fit to product development. With one in eight Americans having tried a GLP–1 medication, brands are grappling with how to serve consumers whose bodies may be changing more rapidly than traditional product cycles were designed to accommodate.In this episode of The Debrief, senior correspondent Sheena Butler-Young sits down with BoF senior news and features editor Diana Pearl and The Business of Beauty news and features editor Brennan Kilbane to discuss how fashion and beauty brands are responding to the GLP-1 boom — and why the industry's apparent willingness to adapt to these consumers is raising difficult questions about its long history with size inclusivity.Key Insights:GLP-1s have turned into a fashion infrastructure problem: GLP-1 drugs are creating a new kind of consumer need — not just smaller sizes, but clothes and products that can accommodate rapid physical change. For fashion, this exposes the limits of systems built around relatively stable bodies, from fit models to inventory planning to alterations. As Pearl puts it, the industry may be talking more openly about fit, but real change will be slow because the underlying systems are deeply entrenched. “I don’t think it’s going to be a change that happens overnight or even in the next few months,” she says. “This is something that’s going to take years to fully address.”The best brand responses meet customers where they are: Brands such as Soma offer one model for how to respond: create products for bodies in transition without framing that change as something to fix. Pearl says that approach works because it centres practical need rather than aspiration or shame. “It’s really just making it about: ‘okay, your life has changed, your body has changed, let’s meet you where you are,’” she says. Kilbane adds, “It's possible that we’re going to continue to see more people fluctuating in their weight and it’s quite forward-thinking for a fashion brand to accommodate that changing body.”Beauty is already speaking more directly to the GLP-1 consumer: Beauty and wellness brands are moving faster than fashion in addressing the physical effects of rapid weight loss, from skin laxity to changes in facial volume. According to Kilbane, the category has to have a clearer product rationale for entering the conversation and respond to specific consumer concerns with products and treatments that feel practical. As Kilbane says, “I’ve talked to a lot of plastic surgeons and dermatologists and even some skincare executives. There are things that happen to your skin when you take these medicines,” he says. “I think especially beauty and wellness brands do need to talk to this customer differently, because they are going through a different transformation.”Fashion’s unresolved relationship with thinness: The GLP-1 conversation has provoked scepticism as plus-size consumers have long argued that fashion sizing is broken, yet the industry appears more willing to change when bodies are getting smaller. For Kilbane, this criticism is fair: “It’s hard to not see any of this as the fashion industry’s excuse to champion thinness once again,” he says. Pearl adds that the debate cannot be separated from fashion’s deeper history of exclusion. “On the surface, it’s about sizing, but you can’t talk about what’s going on and not talk about fashion’s history of championing thinness,” she says.Additional Resources:How Ozempic Is Forcing Fashion to Rethink Fit Novo Nordisk Looks Beyond Weight Loss to Longevity and Aesthetics At Wellness Resorts, Ozempic Becomes Part of the Menu Hosted on Acast. See acast.com/privacy for more information.
-
 A Message to Listeners 27.05.2026The Debrief podcast is taking a short break and will be back in 2 weeks. Hosted on Acast. See acast.com/privacy for more information.
-
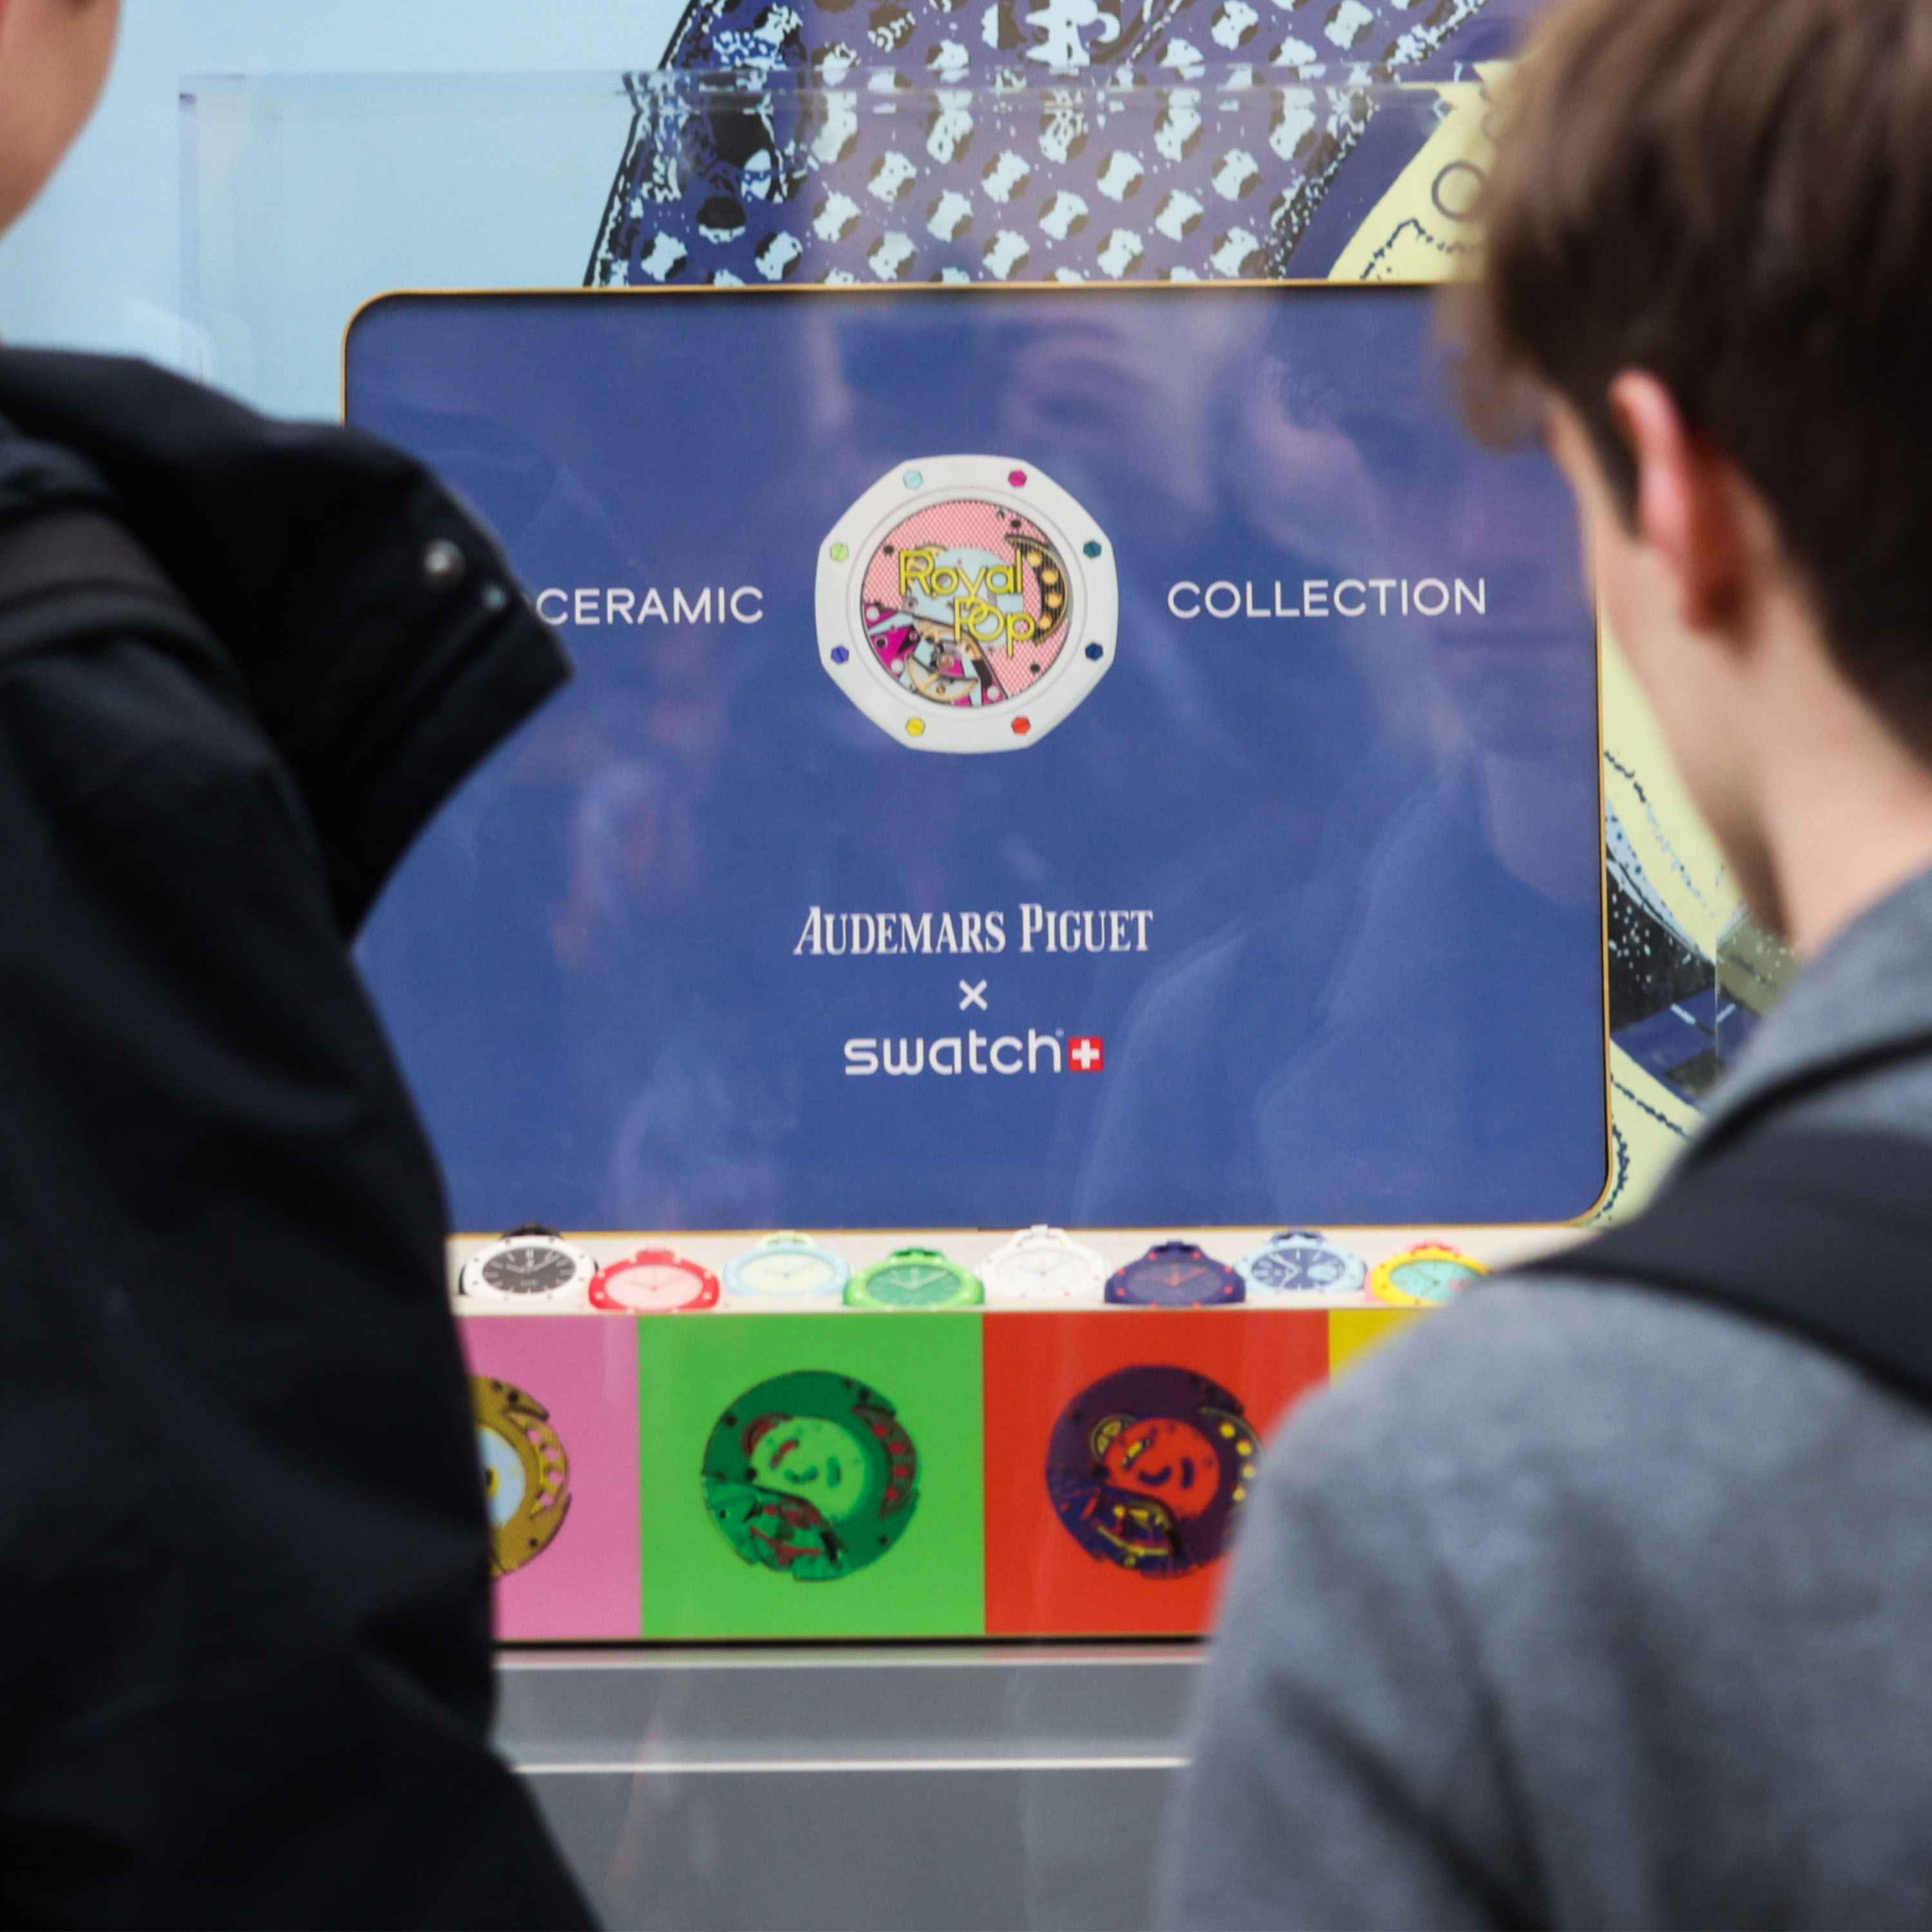 Inside The Swatch X Audemars Piguet Global Frenzy 20.05.2026 21minIn May, sleeping bags lined pavements and police barriers went up outside Swatch stores from Times Square to Dubai. The object of this global hysteria was not a piece of high-end mechanical art, but the "Royal Pop" – a $400 pocket watch collaboration between mass-market giant Swatch and watchmaker Audemars Piguet. Based on AP’s iconic Royal Oak, which typically starts at $20,000, the launch divided the insular watch enthusiast community while captivating Gen Z consumers and equity analysts alike. In this episode of The Debrief, senior correspondent Sheena Butler-Young is joined by retail editor Cathaleen Chen and luxury editor Mimosa Spencer to evaluate the highs and lows of the fallout of the viral launch, the operational chaos across retail and whether a plastic pendant can truly serve as a long-term customer recruitment tool.Key Insights:The Strategy of Alternative Formats: By designing the collection as pocket and pendant watches rather than traditional wristwatches, Audemars Piguet aimed to protect the brand equity of its foundational core product while still opening the brand to a younger, accessory-loving Gen Z demographic.An Unequal Value Exchange: While Audemars Piguet is treating the collaboration as an insulated, almost philanthropic “special project,” Swatch Group stands to gain significantly more commercial momentum. Despite some short-term negative sentiment driven by watch purists, the partnership represents a major cultural breakthrough for Swatch as it attempts to reverse recent financial stagnation.The Accessibility Offense: The intense backlash from traditional watch collectors exposes a deeper tension within the luxury value proposition. For an industry built on status signaling and rigid gatekeeping, the mass participation of everyday consumers is often viewed by insiders not as democratization, but as a dilution of exclusivity in luxury watchmaking.The PR Stunt Demerit: While market traffic and mainstream cultural buzz reached unprecedented stratospheres, the operational execution – which resulted in store closures and aggressive crowds – inflicted real in-person emotional damage. For legacy luxury institutions, headlines detailing retail chaos and police barricades run directly counter to the controlled, pristine environment that high-net-worth clients expect.Entering the Cultural Conversation: The collaboration underscores a broader challenge facing the luxury sector: building cultural relevance and household-name recognition among younger consumers who may currently be priced out of $25,000 mechanical timepieces, while planting the seed for future customer loyalty. Additional Resources:How Swatch and Audemars Piguet Defied Collaboration Fatigue | BoF Professional Pete Nordstrom on the Enduring Power of Retail’s ‘Best Mousetrap’ | The BoF Podcast Can Department Stores Save Themselves? | The Debrief Hosted on Acast. See acast.com/privacy for more information.
-
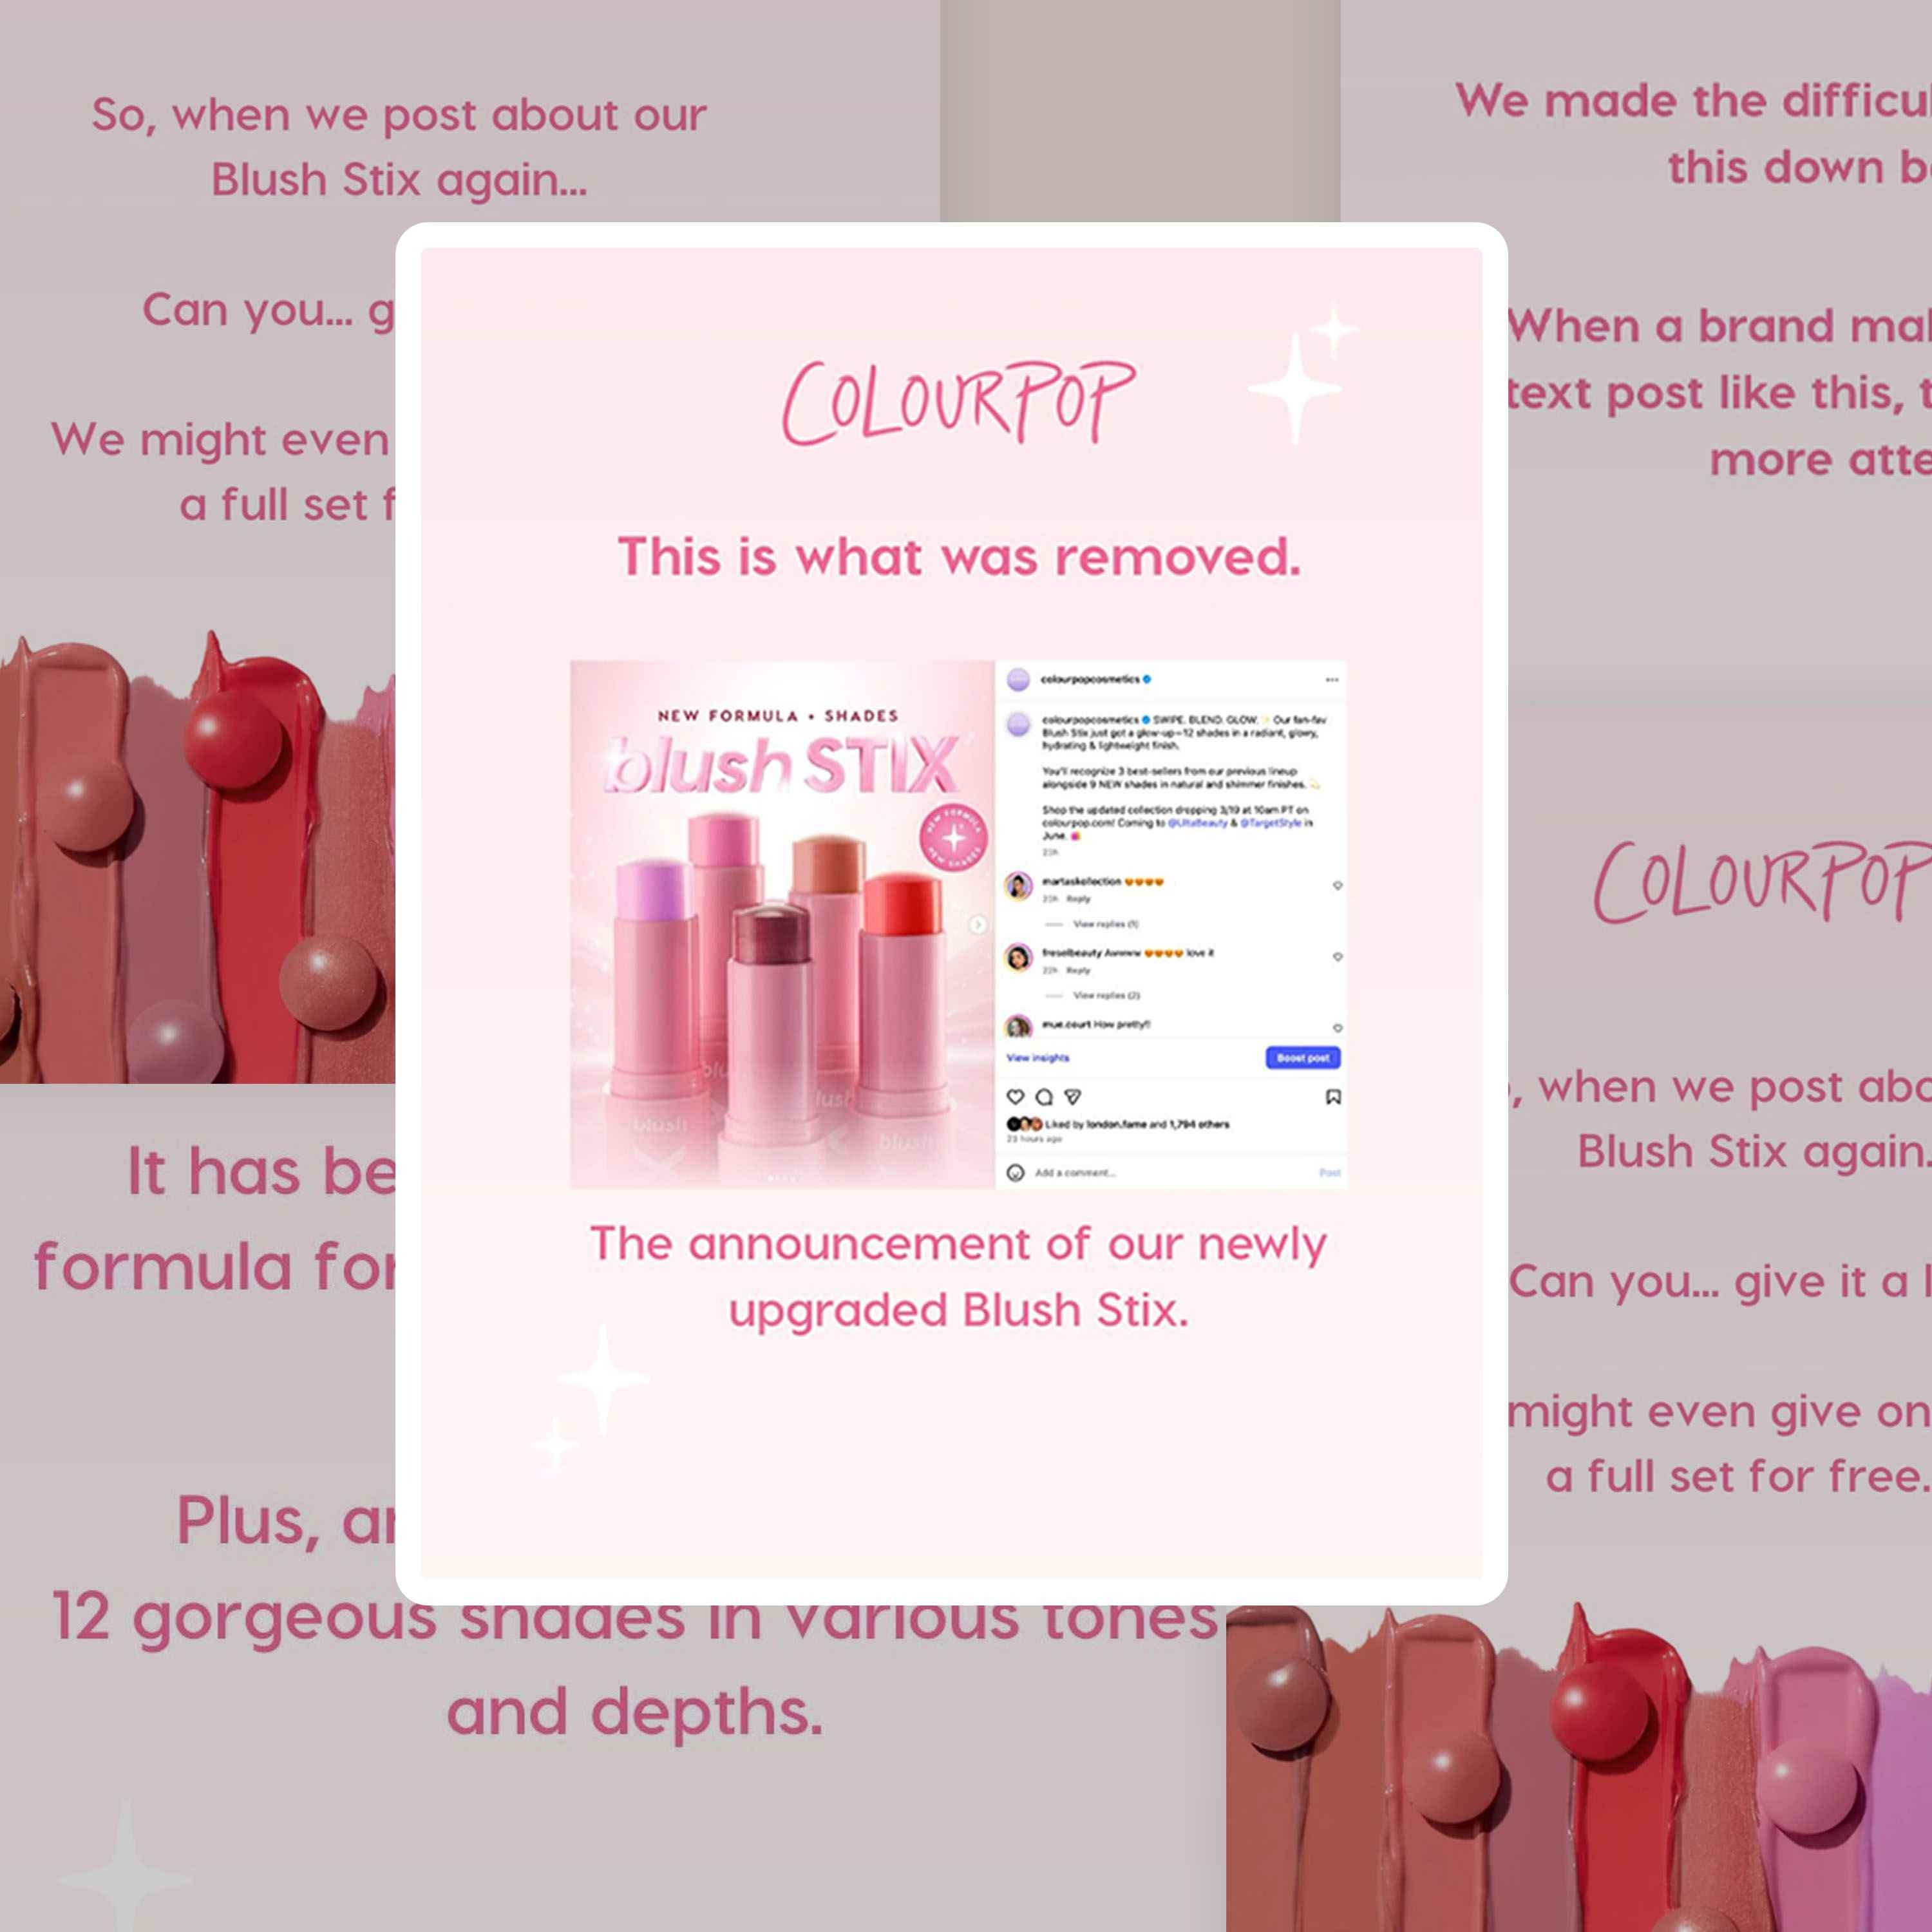 Why Are So Many Brands Faking Scandals? 13.05.2026 20minThe beauty industry is currently contending with marketing saturation, compounded by an overcrowded content ecosystem in which traditional metrics like follower counts and comments are often distorted by bots. To combat this, brands are turning to "rage bait"— content designed to trigger shock, anger or confusion and meant to drive shares and saves, which are now seen as more authentic indicators of engagement. From Lancôme’s "misdirected" PR mailers to ColourPop’s fake apology squares, the strategy bets that a negative or confused reaction is more valuable than no reaction at all in a world where attention is the ultimate currency.In this episode, BoF’s Sheena Butler-Young talks to Business of Beauty Executive Editor Priya Rao, and Senior Editorial Associate Rachael Griffiths about whether these high-risk stunts build genuine brand equity or simply erode long-term consumer trust.Key Insights:The Engagement-Sales Gap: While rage bait excels at awareness and can grab people’s attention, there is no direct, proven line to immediate sales. Success is currently measured through the "halo effect" on other posts and metrics like shares and saves rather than conversion.The "Boy Who Cried Wolf" Risk: Brands face a significant limitation in that this strategy is often a one-time lever. If a brand issues a fake apology for marketing, it risks losing all credibility when a genuine corporate blunder occurs.Suitability by Segment: Chaotic creator" style may work best for indie or playful brands like ColourPop and Dieux. Heritage or luxury brands — particularly those focused on medical-grade efficacy or high price points — risk alienating customers who expect a serious relationship with the brand.The Confusion Trap: Stunts that cross the line from cheeky to genuine misinformation, such as Schick’s ambiguous partnership with Nick Jonas, can leave consumers feeling annoyed and disappointed rather than entertained.Additional Resources:Why Are So Many Beauty Brands Faking Scandals? | BoFPlaybook | Beauty Retail in the Age of Connected Commerce | BoFHow to ‘Un-Cancel’ a Beauty Product | BoF Hosted on Acast. See acast.com/privacy for more information.
-
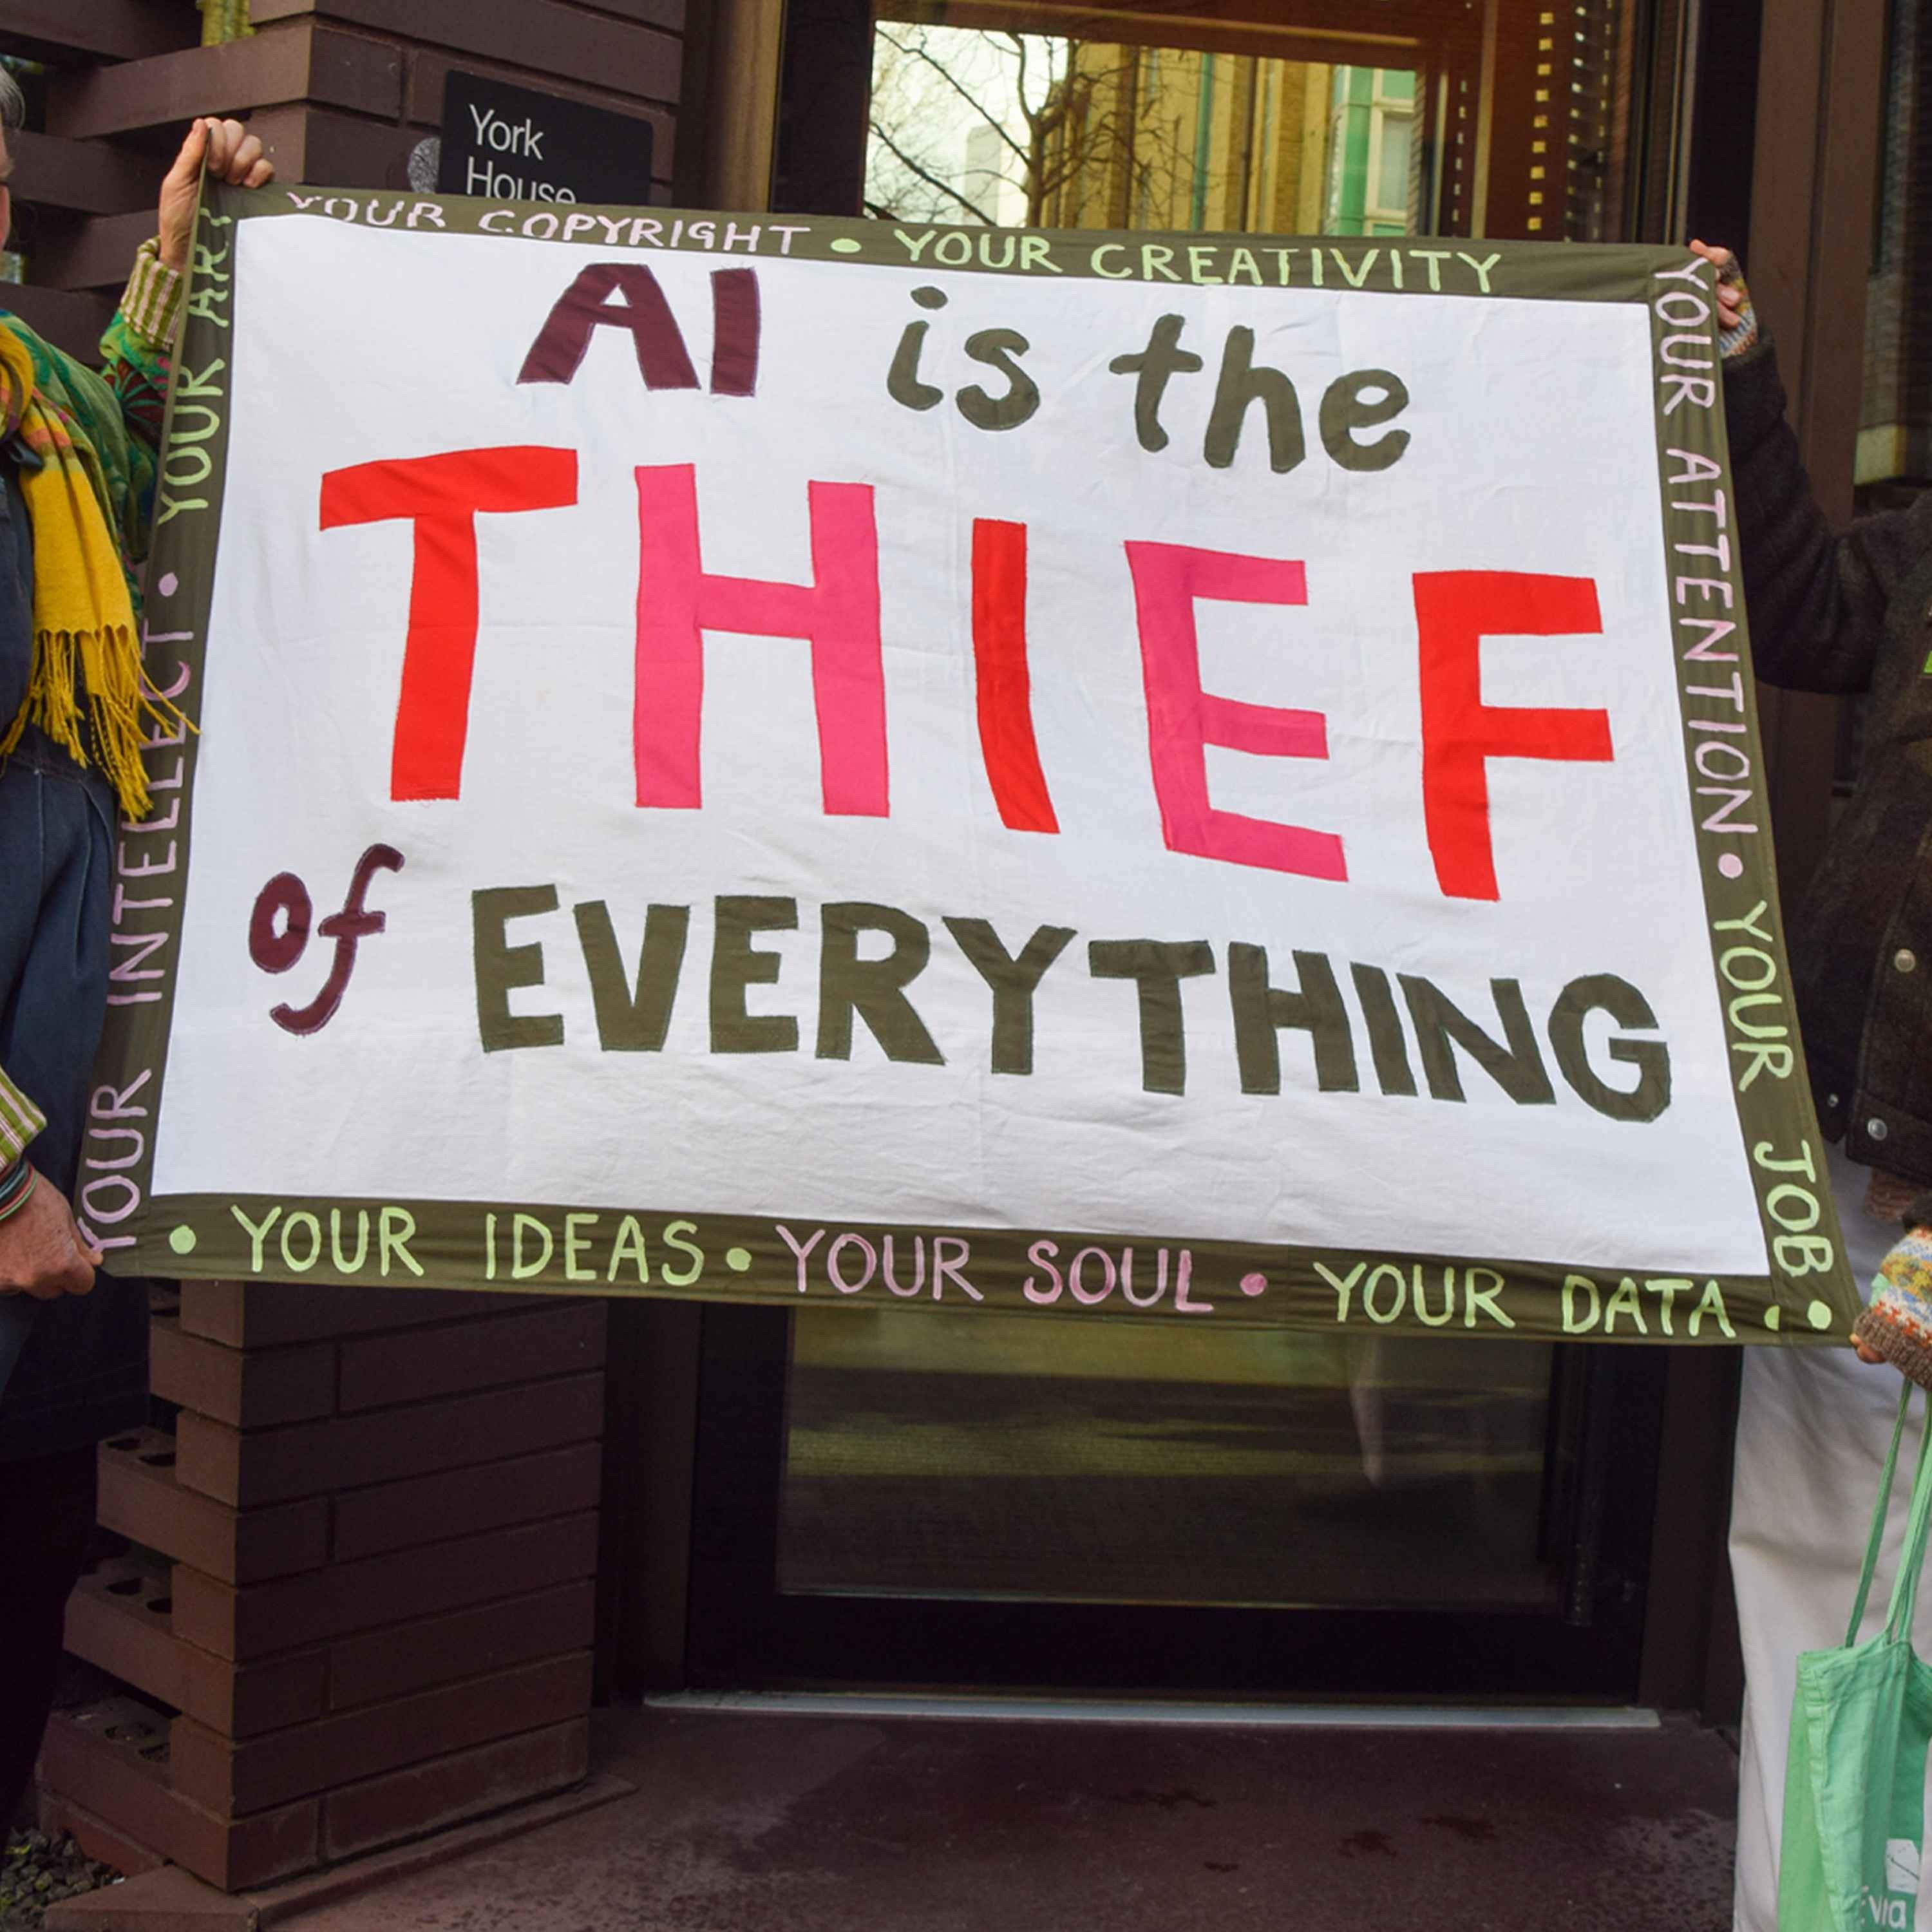 Why People Hate AI 06.05.2026 30minSince the earliest days of tools like ChatGPT and Claude, industry conversations have been marked by a tension between excitement around speed and efficiency alongside deep-seated fears of job loss, creative dilution and concerns about its environmental footprint. What once played out in theory is now unfolding in practice – as a broader rejection of what AI represents — particularly as more consumers view AI-generated content as a cost-cutting measure that erodes fashion’s human touch,In this episode, The Debrief host Sheena Butler-Young discusses with BoF correspondents Marc Bain and Haley Crawford why the backlash is intensifying and how consumer sentiment against brands using AI-generated imagery is forcing a reckoning. They explore whether fashion can actually embrace these tools without losing the care and time that confers luxury status.Key Insights:Consumers are moving past passive skepticism around AI and increasingly displaying a more visceral negative reaction to AI visuals.In an industry built on originality and attribution, AI is often perceived as shortcutting the creative process — or worse, borrowing from artists without credit. For many, it raises uncomfortable questions about what constitutes real creative ownership.At the same time, there is growing concern that AI could erode both the craft and the pipeline behind fashion creativity, threatening entry-level roles and the time, care and human touch that underpin luxury’s value. Additional Resources:Why People Hate AI The Fashion Marketer’s Guide to AI Why Revolve Can’t Stop Talking About AI Hosted on Acast. See acast.com/privacy for more information.
-
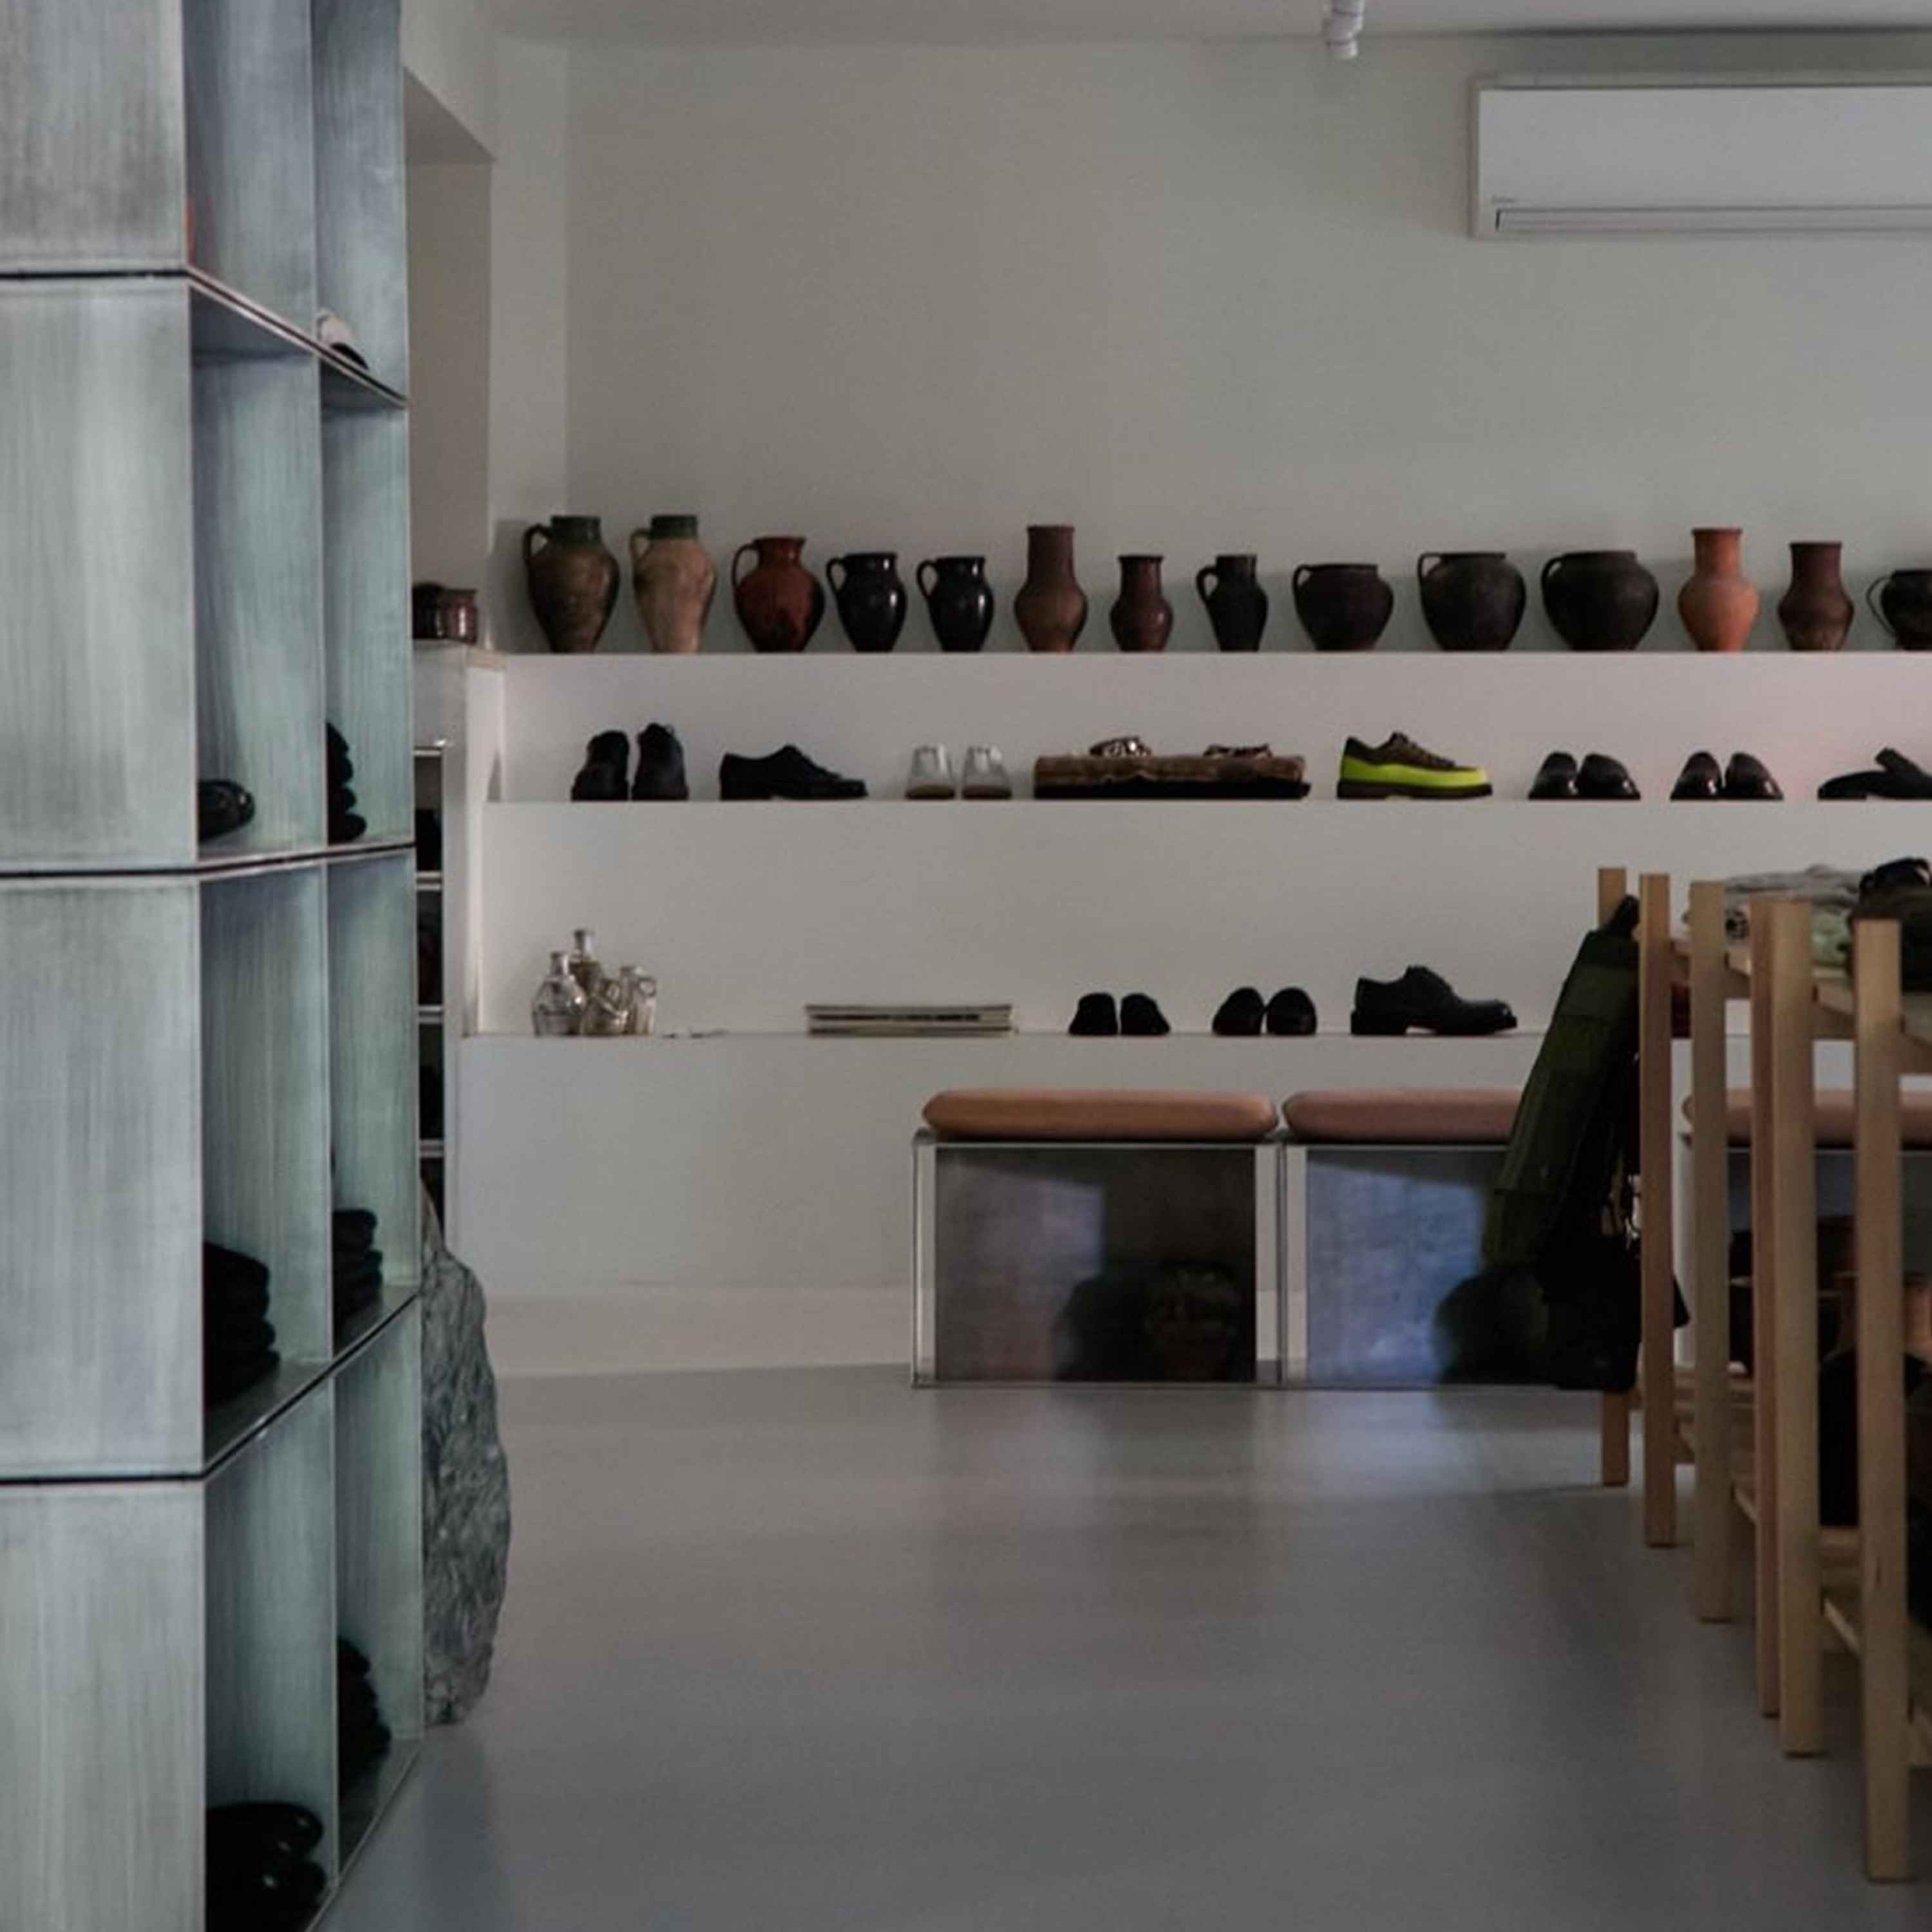 Why Some Retailers are Ignoring the Internet 29.04.2026 25minFor years, the fashion industry operated under the assumption that digital scale was the right path. However, the "growth-at-all-costs" model is currently fracturing as luxury giants grapple with soaring customer acquisition costs and a logistical crisis fueled by high return rates. In response, a quiet counter-culture is emerging, with stores like Ven. Space and Dot Reeder thriving by intentionally limiting their digital footprints. In this episode, executive editor Brian Baskin and senior correspondent Sheena Butler-Young discuss with BoF correspondent Austin Kim how these analogue retailers are using hyper-local intimacy and intelligent curation to build a more resilient business model that values brand equity over infinite reach. Key Insights:The Rejection of Digital Friction: Store owners like Chris Green of Ven. Space are intentionally limiting their digital footprints to avoid the "grind" of high customer acquisition costs. Austin Kim notes that for these owners, "these small businesses are people doing what they love and what they don't love is e-commerce and they have no interest in it".The "Sit and Fit" Financial Advantage: Analyst Simeon Siegel posits that the in-store customer is the superior economic unit because they absorb the costs of fulfillment. As Kim explains, "In the store, the customer takes the pair of jeans off the rack, walks it over to the cash register, and then takes it home to themselves," whereas online, a brand must pay for picking, packaging, and the high probability of returns.Product Curation as a Moat: Success for these boutiques relies on a "mythic" assortment of brands that creates a level of trust an algorithm cannot replicate. Kim highlights that the draw is the owner's perspective: "Chris Green is almost like a Mr. Rogers if he wore Dries van Noten ... that perspective is exactly what I think customers connect with".Analogue Marketing and the "Third Space": To cut through digital exhaustion, retailers like Outline are pivoting to high-quality print catalogs. Co-founder Margaret Austin describes e-commerce as "unsexy," preferring a strategy where receiving something at your door acts as "an amazing strategy" to cut through the noise of social media.The Scalability Paradox: The "secret sauce" of these stores is often the owner-operator’s deep local roots, which is difficult for corporate entities to mimic. Kim warns that "you lose the soul of a business really quickly as you scale, especially on e-commerce," because you begin buying for an international audience rather than maintaining a specific, connected perspective. Additional Resources:Meet the Retailers Succeeding by Ignoring the Internet | BoFThe State of Fashion 2026: When the Rules Change | BoFThe BoF Podcast | Pete Nordstrom on the Enduring Power of Retail’s ‘Best Mousetrap’ Hosted on Acast. See acast.com/privacy for more information.
-
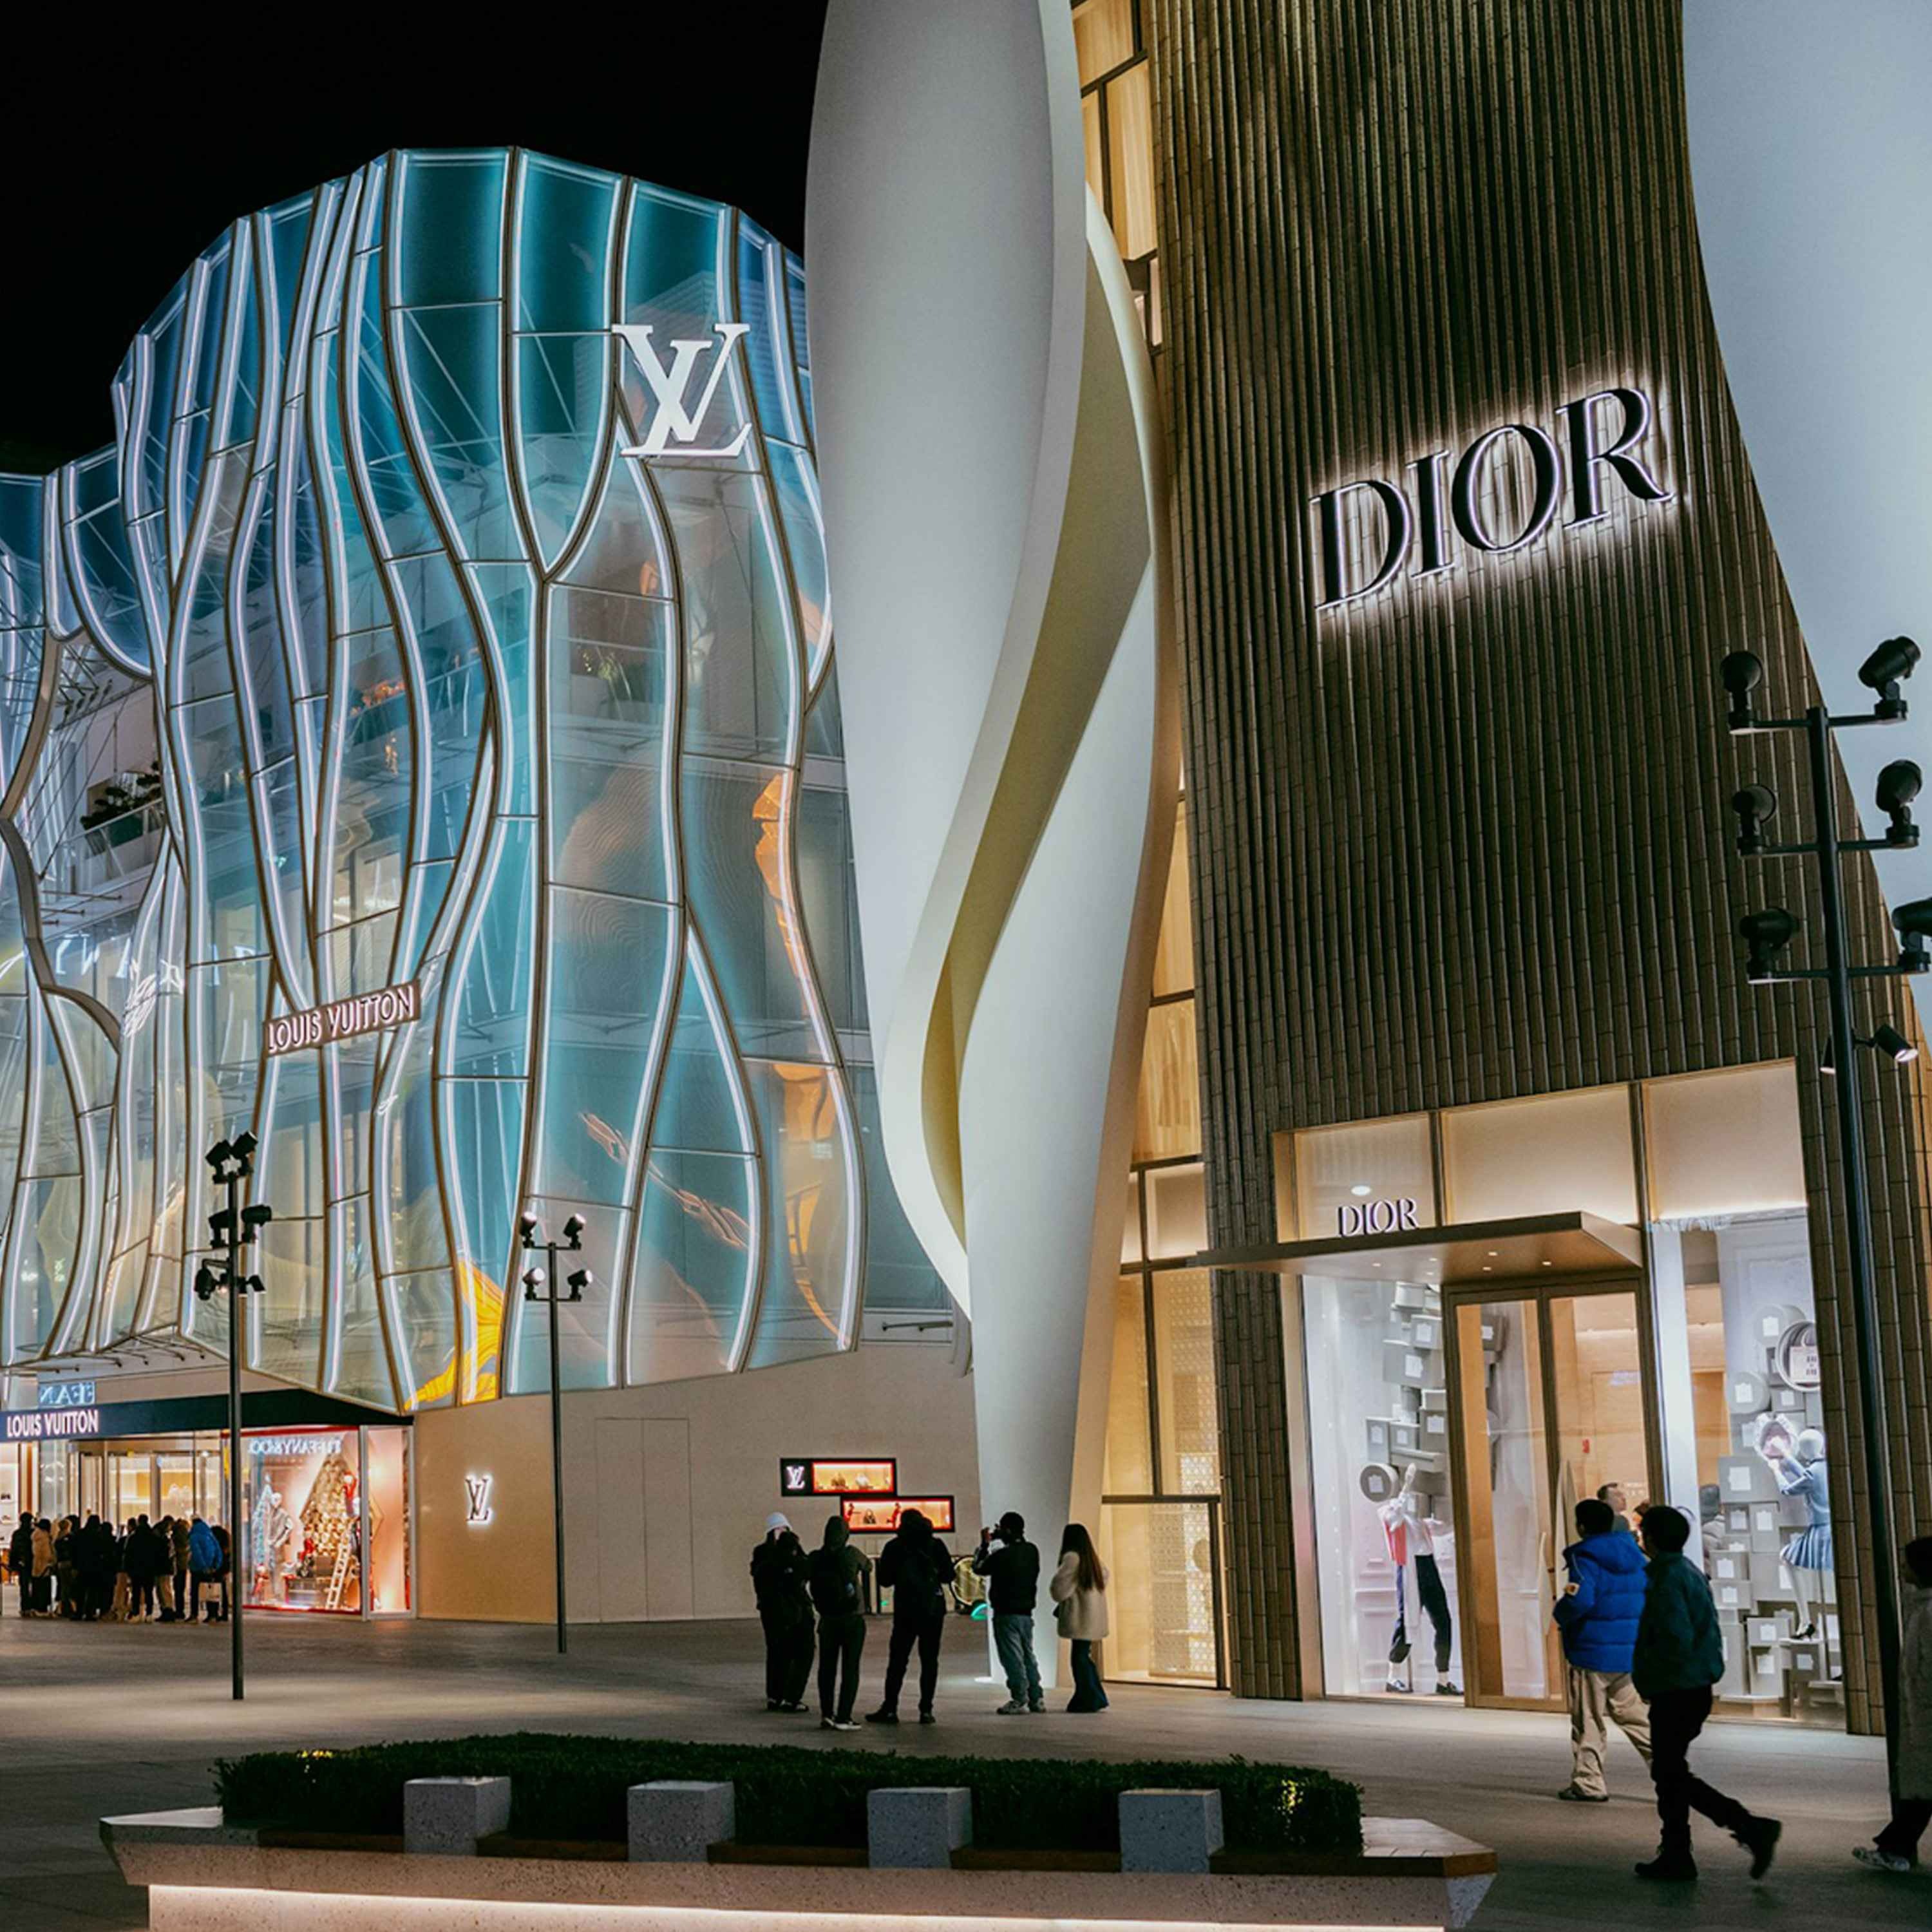 Why Luxury Still Can’t Find Its Way Out of the Slump 22.04.2026 36minLuxury entered 2026 with hopes that new creative directors and signs of stabilisation would finally help the sector turn a corner. Instead, the latest round of earnings has raised bigger questions about what growth now looks like for the industry. While brands including Dior, Gucci and Chanel are generating renewed interest, that excitement has not yet translated into a meaningful sales rebound. From the slowing Chinese market to geopolitical tensions in the Middle East, luxury conglomerates are facing a complex web of challenges that creative hype alone cannot solve.On the episode, BoF luxury editors Mimosa Spencer and Robert Williams explain why China remains such a critical missing piece, why Louis Vuitton is under closer scrutiny than usual, and why jewellery continues to outperform the rest of luxury.Key Insights:One of the clearest messages from this earnings season is that new designers can lift mood and momentum internally, but that alone is not enough to restart the industry. Williams says the latest results confirmed that the impact of all these creative resets is “pretty limited, especially in isolation”. As he puts it, “the result of that is more like treading water or stabilising versus actually reigniting growth.” Spencer adds that the disappointment was sharper because there had been so much excitement around these debuts that “a lot of investors were expecting some earlier results.”Both Spencer and Williams point to China as the market hanging over the entire sector. Even where sentiment improved at the end of last year, investors were still looking for signs that Chinese demand might return in a meaningful way. Spencer says the bigger issue now is not just timing but structure: “The question is whether the kind of growth we saw in the past will actually come back.” She adds: “It seems like it takes a lot more work for a luxury brand to actually get good results in China.”LVMH still wants the market to see Dior as the manageable turnaround story, but Williams suggests the real anxiety now sits around Louis Vuitton. The brand has held up better than many peers, but investors are increasingly asking where its next phase of growth will come from. Williams points out that the bigger concern is not short-term performance, but what comes next. “No one can really see where the growth is going to come from,” he says. “Is this still a growth industry? What will the industry look like and how will it operate if it's not growing anymore?” If the industry’s strongest player cannot clearly define its next phase of growth, it raises deeper questions about the trajectory of luxury as a whole.Despite the broader slowdown across luxury, Spencer argues that jewellery’s outperformance is not just about demand for hard luxury, but about how consumers now judge value. Handbag prices have climbed so sharply that jewellery, by comparison, can feel like a more rational indulgence. “Jewellery prices haven’t gone up in the same way that handbag prices have gone up,” she says. At the same time, jewellery still carries a perception of durability and investment value, whether or not that always holds in practice.Luxury brands may be making more progress with their established high-spending clients than with the broader aspirational base they once relied on for volume. Williams notes that some houses are succeeding in pulling core customers back into stores, even if that is not yet translating into a wider recovery. At Chanel, for example, he points to renewed momentum among “well-to-do women with big executive jobs in their late 30s, 40s, and 50s,” while Louis Vuitton’s monogram anniversary campaign has helped refocus attention on its most iconic products.Additional Resources:The Luxury Rebound Gets a Reality Check | BoF Kering’s Strategy Reveal, Examined | BoF Hosted on Acast. See acast.com/privacy for more information.
Samankaltaiset podcastit


Suosittu maassa
Tämä podcast esiintyy myös näiden maiden podcast-listoilla.


