
The Earnings Debate
EarningsBeat.ai
0
A financial comedy podcast that turns quarterly earnings calls into a debate between two AI hosts: a skeptic and an optimist. The show cuts through corporate jargon, pressure-tests claims, and highlights the most important questions from each call. It offers rigorous analysis with a humorous twist, aiming to keep listeners informed and entertained. The tagline emphasizes staying on top of the beat so you don't miss a beat.
Jaksot
-
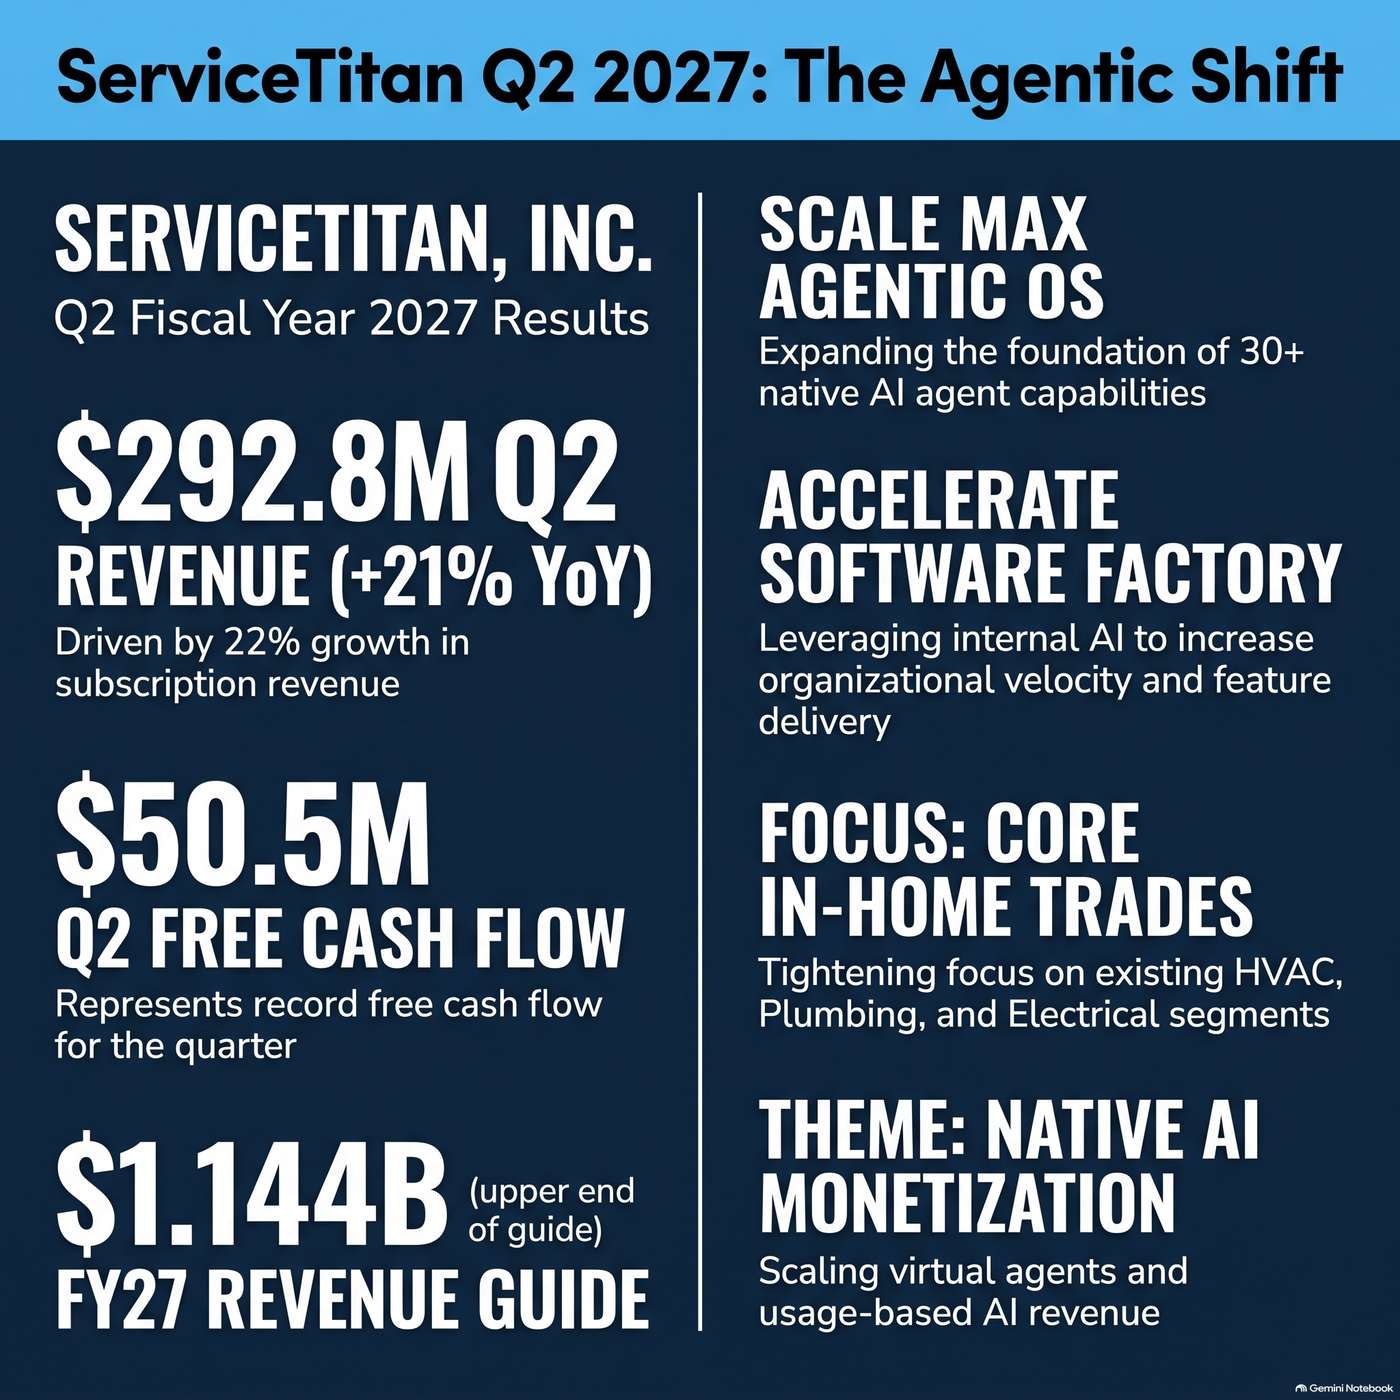 ServiceTitan, Inc. (TTAN) Announced Q2 2027 Earnings on September 8, 2026, Reporting "Q2 total revenue of $292.8 million grew 21% year-over-year." 08.09.2026 18minServiceTitan, Inc. reported its fiscal second quarter 2027 financial results.For the quarter, the company reported that Q2 total revenue of $292.8 million grew 21% year-over-year.Subscription revenue for the quarter was $212.4 million, growing 22% year-over-year, and usage revenue for the quarter grew 24% year-over-year to $72.1 million.The company reported that Q2 operating income of $44.4 million resulted in operating margin of 15.2%, representing an improvement of 310 basis points year-over-year.Free cash flow for the second quarter was $50.5 million, up 47% year-over-year, and year-to-date free cash flow was $40.9 million.Additionally, net dollar retention was greater than 110% for the quarter, and gross transaction volume for the quarter was $26.8 billion, representing 17% year-over-year growth.In key business updates, management announced a significant executive transition.Chief Revenue Officer Ross Biestman is stepping down from his operating role after helping scale the company from less than $30 million in annual recurring revenue to over $1 billion of annual normalized run rate revenue.Rikus Pretorius, who has served as Senior Vice President of Worldwide Sales for over seven years, will step into the Chief Revenue Officer role in the fourth quarter.Strategically, the company decided to narrow its trade expansion scope to focus on existing commercial trades and residential roofing rather than expanding into new trades.This prioritization allows the company to focus resources on its Max program and its software factory initiative to optimize development speed and internal efficiency.For product and technology updates, the company reported accelerating adoption of its Max platform, which now features over thirty native agentic capabilities.The company doubled the number of locations enrolled in Max during the first quarter and exceeded its goals in the second quarter, now forecasting to end the fiscal year with over 700 enrolled Max locations.The company also expanded its AI virtual agents product by launching new voice and SMS capabilities, including speed-to-lead technician notifications.Consequently, virtual agent revenue and call volume each more than doubled sequentially quarter-over-quarter.Management provided forward guidance for the third fiscal quarter and full fiscal year 2027.For the third quarter, the company expects total revenue in the range of $285 million to $287 million and operating income in the range of $29 million to $30 million.For the full fiscal year 2027, ServiceTitan expects total revenue in the range of $1.139 billion to $1.144 billion and operating income in the range of $152 million to $154 million.Due to the company's strong margin performance, management noted that they now expect full-year incremental margins of 33% and believe a 25% incremental operating margin will represent a floor rather than a target moving forward.💡 What's next? Would you like to create a set of promotional social media posts or compile a detailed comparison chart of ServiceTitan's sequential financial performance across their fiscal 2026 and 2027 quarters?
-
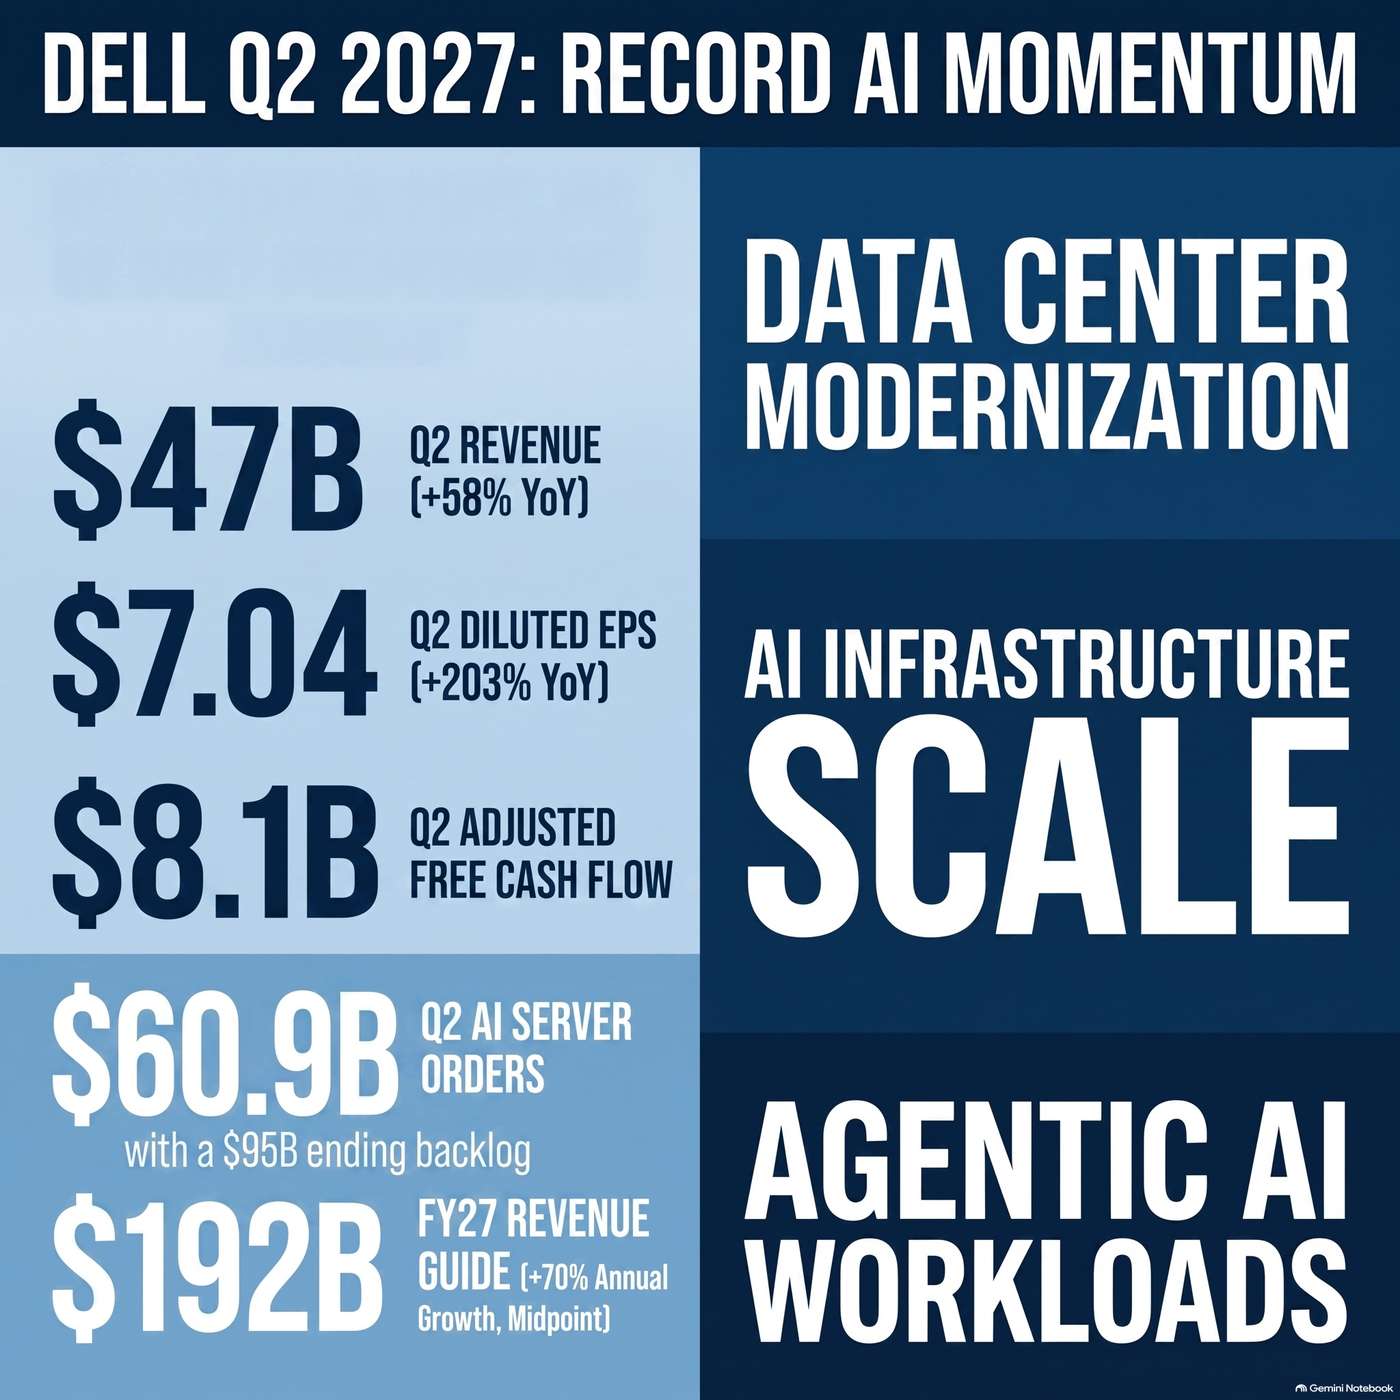 Dell Technologies Inc. (DELL) Announced Q2 2027 Earnings on September 1, 2026, Reporting "Revenue was $47 billion, up 58%" 05.09.2026 18minDell Technologies Inc. reported its fiscal year 2027 second quarter financial results, stating that total revenue was up 58 percent to 47 billion dollars.Gross margin dollars grew 78 percent to 9.9 billion dollars, with a gross margin rate of 21.1 percent.Non-GAAP operating income grew 160 percent to 5.9 billion dollars, representing 12.6 percent of revenue, and net income was up 189 percent to 4.6 billion dollars.Record quarterly diluted earnings per share increased 203 percent to 7.04 dollars.The company delivered cash flow from operations of 2.2 billion dollars and adjusted free cash flow of 8.1 billion dollars for the quarter. It also returned an all-time record of 4.3 billion dollars to shareholders, which included repurchasing 9.5 million shares at an average price of 401 dollars per share and paying a dividend of approximately 0.63 dollars per share.Within business segments, the Infrastructure Solutions Group delivered record revenue of 31.8 billion dollars, up 89 percent.This performance was driven by the artificial intelligence business, where the company booked a record 60.9 billion dollars in AI orders, recognized 16.4 billion dollars in AI server revenue, and exited the quarter with a record 95 billion dollars of AI backlog.Traditional server and networking revenue was 10.5 billion dollars for the quarter, up 122 percent, while storage revenue was 4.9 billion dollars, up 26 percent.The Client Solutions Group posted revenue of 15 billion dollars, up 20 percent, driven by commercial revenue of 13.2 billion dollars, up 22 percent, and consumer revenue of 1.8 billion dollars, up 7 percent. In managing supply chain conditions, executive Jeffrey Clarke highlighted that component constraints persist, stating that the constraints remain the same with DRAM followed by NAND.Regarding strategic initiatives, products, and partnerships, the company expanded its customer base, noting its AI customer count has surpassed 6,500.Dell announced it became the first to ship rack systems engineered on the NVIDIA Vera Rubin platform, and noted that Lightning, its parallel file system designed for native AI use cases, remains in beta with several customers.Looking ahead to guidance, the company expects third-quarter revenue to be 49 billion dollars at the midpoint, up roughly 80 percent year-on-year, with diluted non-GAAP earnings per share expected to be 6.50 dollars for the third quarter.For the full year, the company raised its full-year revenue guidance midpoint by 25 billion dollars to 192 billion dollars, up roughly 70 percent, with diluted non-GAAP earnings per share expected to be 25.50 dollars for the full year.This full-year guidance includes expected Infrastructure Solutions Group growth of roughly 120 percent, driven by AI server revenue of 74 billion dollars for the full year.🎙️ Would you like me to draft the five FinTwit tweet variants matching this Q2 print next?
-
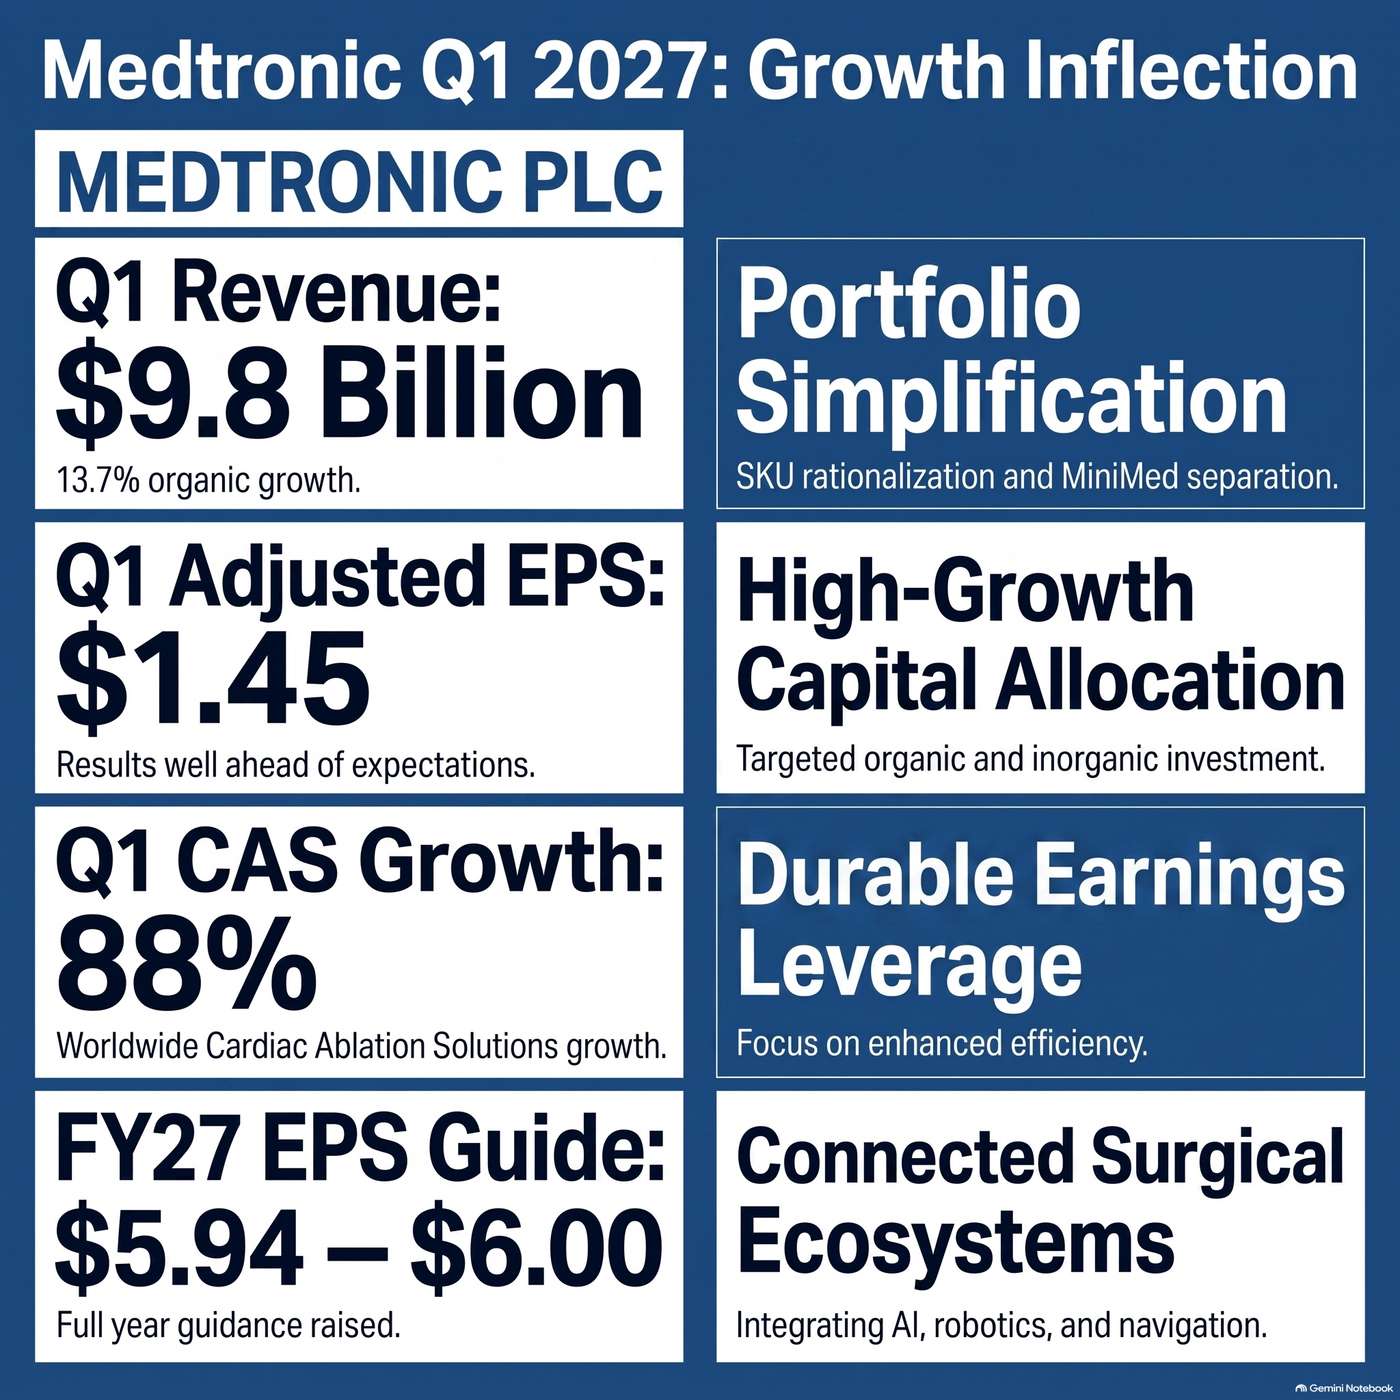 Medtronic plc (MDT) Announced Q1 2027 Earnings on September 1, 2026, Reporting "revenue of $9.8 billion" for the first quarter 05.09.2026 21minMedtronic plc reported first quarter fiscal year 2027 financial results, including "revenue of $9.8 billion" for the quarter, up "13.7% on both the reported and organic basis." This performance "benefited from the extra selling week, which we estimate contributed approximately $570 million or 670 basis points to total organic enterprise revenue growth." The company delivered first quarter "adjusted EPS of $1.45," which was "$0.06 above the midpoint of our guidance range." First quarter "adjusted gross margin was 65.2%," which was "up 10 basis points year-over-year," and "adjusted operating profit was $2.3 billion," an increase of "15% year-over-year." This resulted in a first quarter "adjusted operating margin of 23.7%, up 10 basis points from the prior year." Adjusted SG&A was "32.4% of revenue" and adjusted R&D was "7.9% of revenue in Q1." The company noted that cash conversion was at "70%" for the first quarter.In business updates, Medtronic highlighted that its Cardiac Ablation Solutions business delivered "88% worldwide growth" in the first quarter, driven by the "Sphere-9 momentum" which "continued with a 9-point increase in U.S. share during the quarter," and the business "surpassed the $2 billion mark in trailing 12-month revenue." In Neuroscience, "Cranial & Spinal Technologies delivered 13% growth worldwide" and the recently launched "Stealth AXiS platform also meaningfully outperformed this quarter." In Pelvic Health, procedures for "Altaviva" "doubled sequentially." In Surgical, the "Hugo" robotic platform is expected to "surpass 50,000 completed procedures" by the end of the fiscal year.The company announced a "strategic investment and distribution agreement for Cornerstone's Sentire Surgical System in select markets outside the U.S." and a "strategic investment" in "Pi-Cardia," which is "the first FDA-cleared leaflet modification technology for TAVR procedures." Medtronic also completed its acquisition of "Scientia" and is on track with the "separation of MiniMed" which they "intend to close prior to fiscal year-end."For forward guidance, Medtronic is raising its "fiscal year '27 organic revenue growth guidance to 7.25% to 7.75%," representing a "50 basis points increase from our prior guidance." For the second quarter of fiscal year 2027, the company expects "roughly 6% organic revenue growth" and adjusted "EPS in the range of $1.32 to $1.34." Foreign exchange is projected as a "roughly $50 million to $150 million headwind for the full year with approximate $25 million to $75 million headwind in 2Q." For the full fiscal year 2027, the company expects "operating profit to grow approximately 10%, with operating margin expanding approximately 50 basis points year-over-year." Finally, Medtronic is raising its full-year fiscal 2027 adjusted EPS guidance range to "$5.94 to $6."Would you like me to draft some social media posts or create a slide deck outline based on these first quarter fiscal year 2027 results?
-
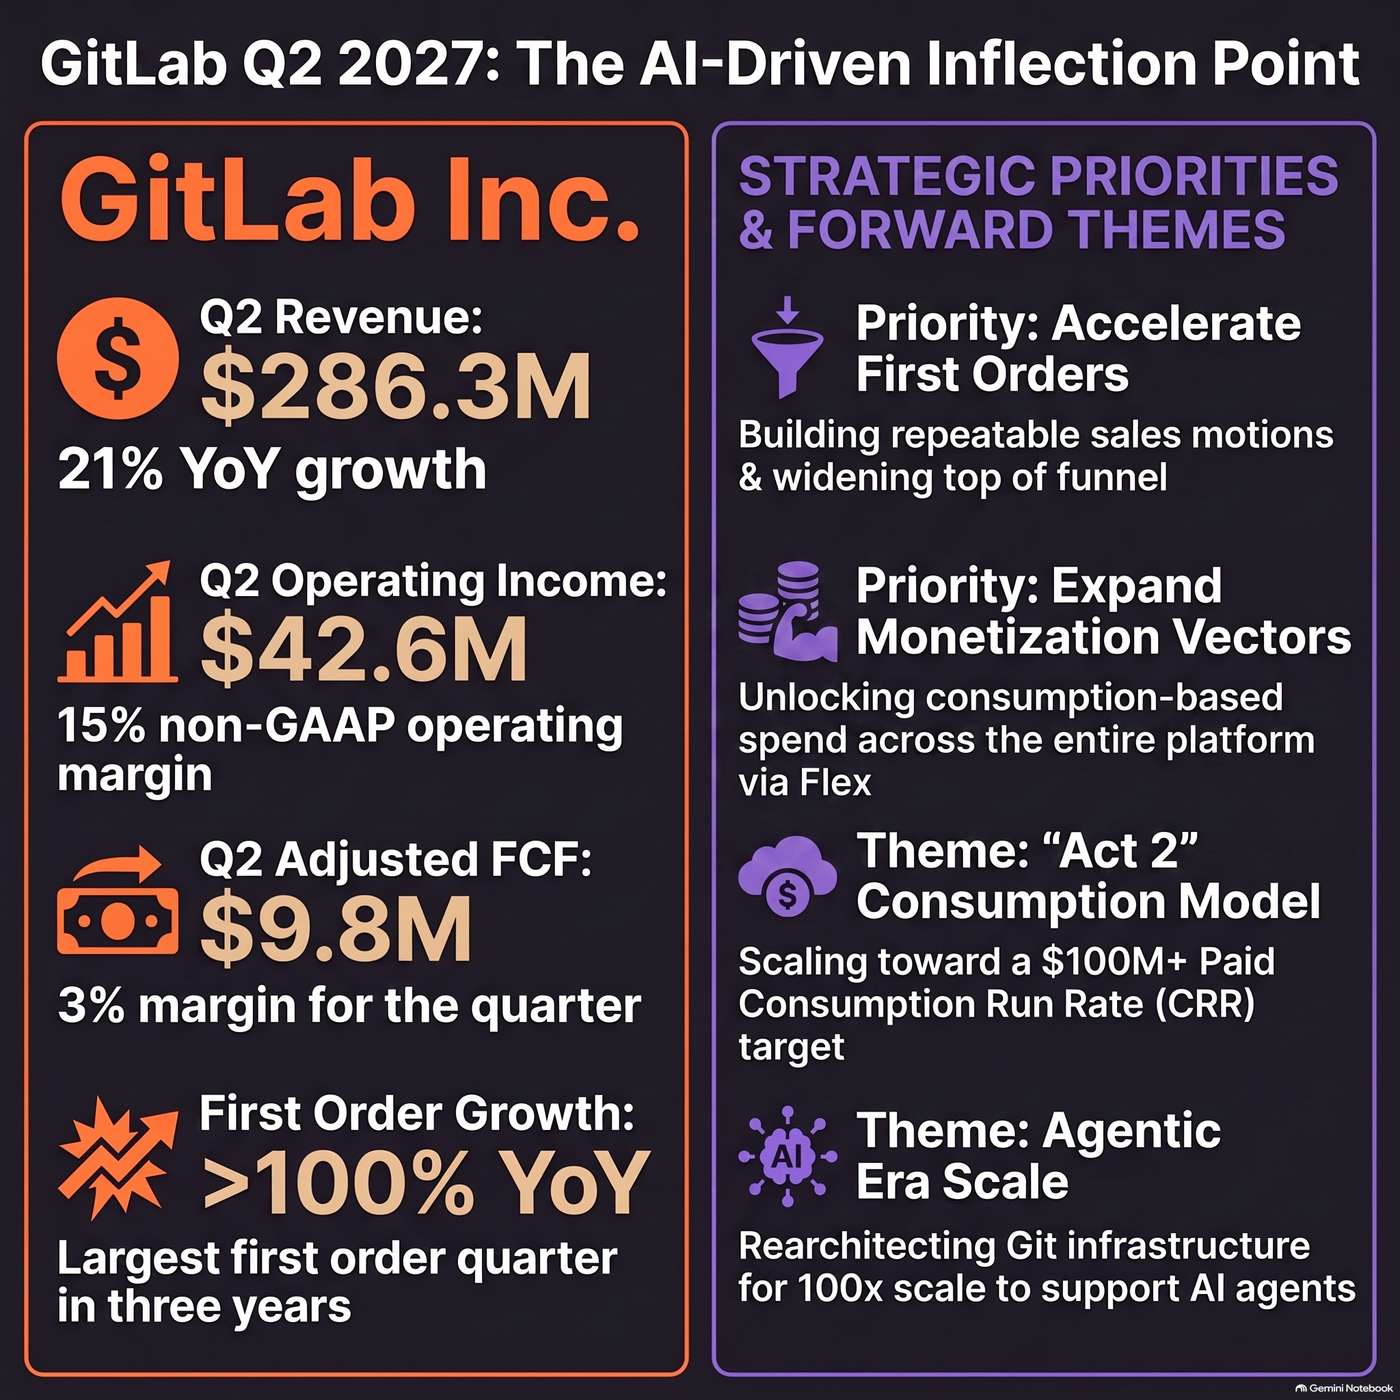 GitLab Inc. (GTLB) Announced Q2 2027 Earnings on September 1, 2026, Reporting "Revenue was $286.3 million, up 21% year-over-year" 04.09.2026 21minManagement noted that "Q2 was an exceptional quarter", reporting that second quarter total revenue was $286.3 million, up 21% year-over-year, and non-GAAP operating income was $42.6 million, representing a 15% operating margin.Non-GAAP gross margin was 86.5%.For the second quarter, adjusted free cash flow was $9.8 million, representing a 3% margin, and the company ended the quarter with $1.3 billion in cash and investments.Additionally, the company delivered the largest gross bookings quarter in history, with dollar-based net retention rate at 117% and net ARR growing 42% year-over-year.Calculated billings grew 24% for the quarter.During the call, management discussed updates on their five growth initiatives. On the product front, the company highlighted the launch of GitLab Flex, noting that "in the first 6 weeks on the market, over 130 customers committed more than $20 million to Flex". Exiting the quarter, the platform-wide paid consumption run rate was above $40 million, up from $15 million in the first quarter.Under their AI strategy, Duo Agent Platform paid CRR grew 50% sequentially, and more than 2,200 organizations have enabled GitLab Orbit indexing in the public beta.The company also announced the August launch of Secrets Manager and Dedicated Runners as their second and third new consumption products of the year.For forward guidance, management raised its outlook for the full year, with Jessica Ross stating "we are raising our guidance to reflect the strong momentum we experienced in the first half of the year as well as the momentum we anticipate will continue into the back half". For the third quarter of fiscal year 2027, the company expects total revenue of $281 million to $283 million, representing approximately 15% to 16% year-over-year growth, and non-GAAP operating income of $35 million to $37 million.For the full year, total revenue is expected to be $1.129 billion to $1.133 billion, representing approximately 18% to 19% year-over-year growth, and non-GAAP operating income is expected to be $148 million to $152 million.Full year non-GAAP gross margins are expected to be between 85% to 87%.
-
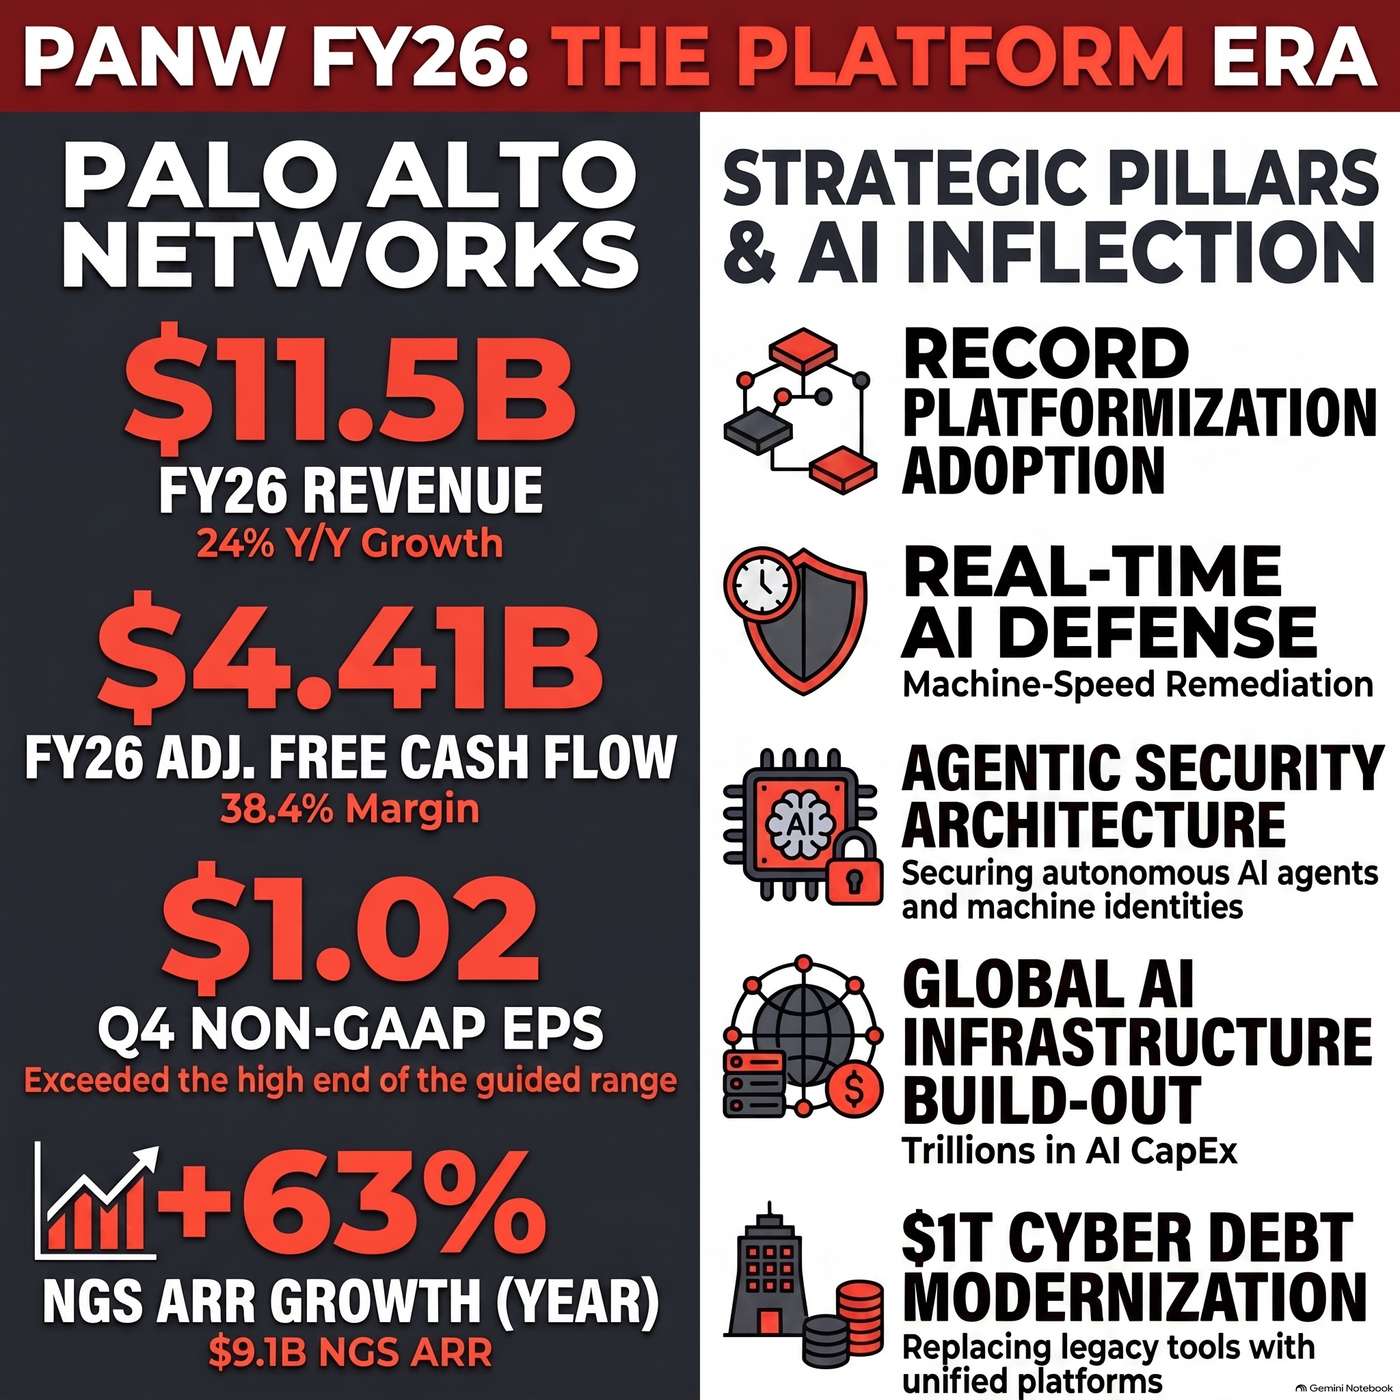 Palo Alto Networks, Inc. (PANW) Announced Q4 2026 Earnings on September 1, 2026, Reporting "revenue grew 34% to $3.41 billion in the fourth quarter" for the Quarter. 04.09.2026 20minPalo Alto Networks reported "total revenue grew 34% to $3.41 billion in the fourth quarter" of fiscal year 2026.For the full fiscal year 2026, "revenue reached $11.5 billion, up 24% year-over-year." Performance metrics for the fourth quarter included "Q4 non-GAAP EPS of $1.02" and "Q4 non-GAAP operating margin came in at 29.6%." For the fourth quarter, the company reported "adjusted free cash flow... reached $1.29 billion, growing 35% year-over-year," bringing the full fiscal year 2026 "adjusted free cash flow" to "$4.41 billion" with a margin of "38.4%." In addition, "NGS ARR reached $9.1 billion in Q4, up 63%," and "Q4 RPO exceeded $20 billion for the first time, ending the year at $21.2 billion, up 34%."In strategic business updates, management highlighted that "during the fourth quarter, we achieved approximately 220 net new platformizations." In core products, "Prisma AIRS achieved a remarkable milestone in Q4, surpassing $100 million in ARR within just 4 quarters of general availability." Under its observability business, "since finalizing the Chronosphere acquisition in Q2, our observability ARR has more than doubled, eclipsing the $500 million mark." Additionally, the company announced that "we closed our acquisition of Console today" to bring "an AI-first approach to product development." In identity security, the company's CyberArk acquisition is now called "Idira," which reached "$1.26 billion" in pro forma revenue for the "fiscal year '26" and "grew 21%."For notable product launches, the company "expanded our frontier AI Defense Service last month, introducing a multimodal harness that enables enterprises to stress test their environments" and noted they are "the first certified commercial partner for Mythos 5." The company also launched a new product called "Modern PAM" which is "generally available now." In terms of guidance, for the first quarter of fiscal year 2027, the company expects "revenue of $3.3 billion to $3.31 billion, or 33% to 34% growth" and "diluted non-GAAP EPS to be in the range of $0.96 to $0.98 per share." For the full fiscal year 2027, the company forecasts "revenue of $14.1 billion to $14.2 billion, or 23% to 24% growth," "operating margin of 29.5%," and "diluted non-GAAP EPS to be in the range of $4.16 to $4.19 per share."
-
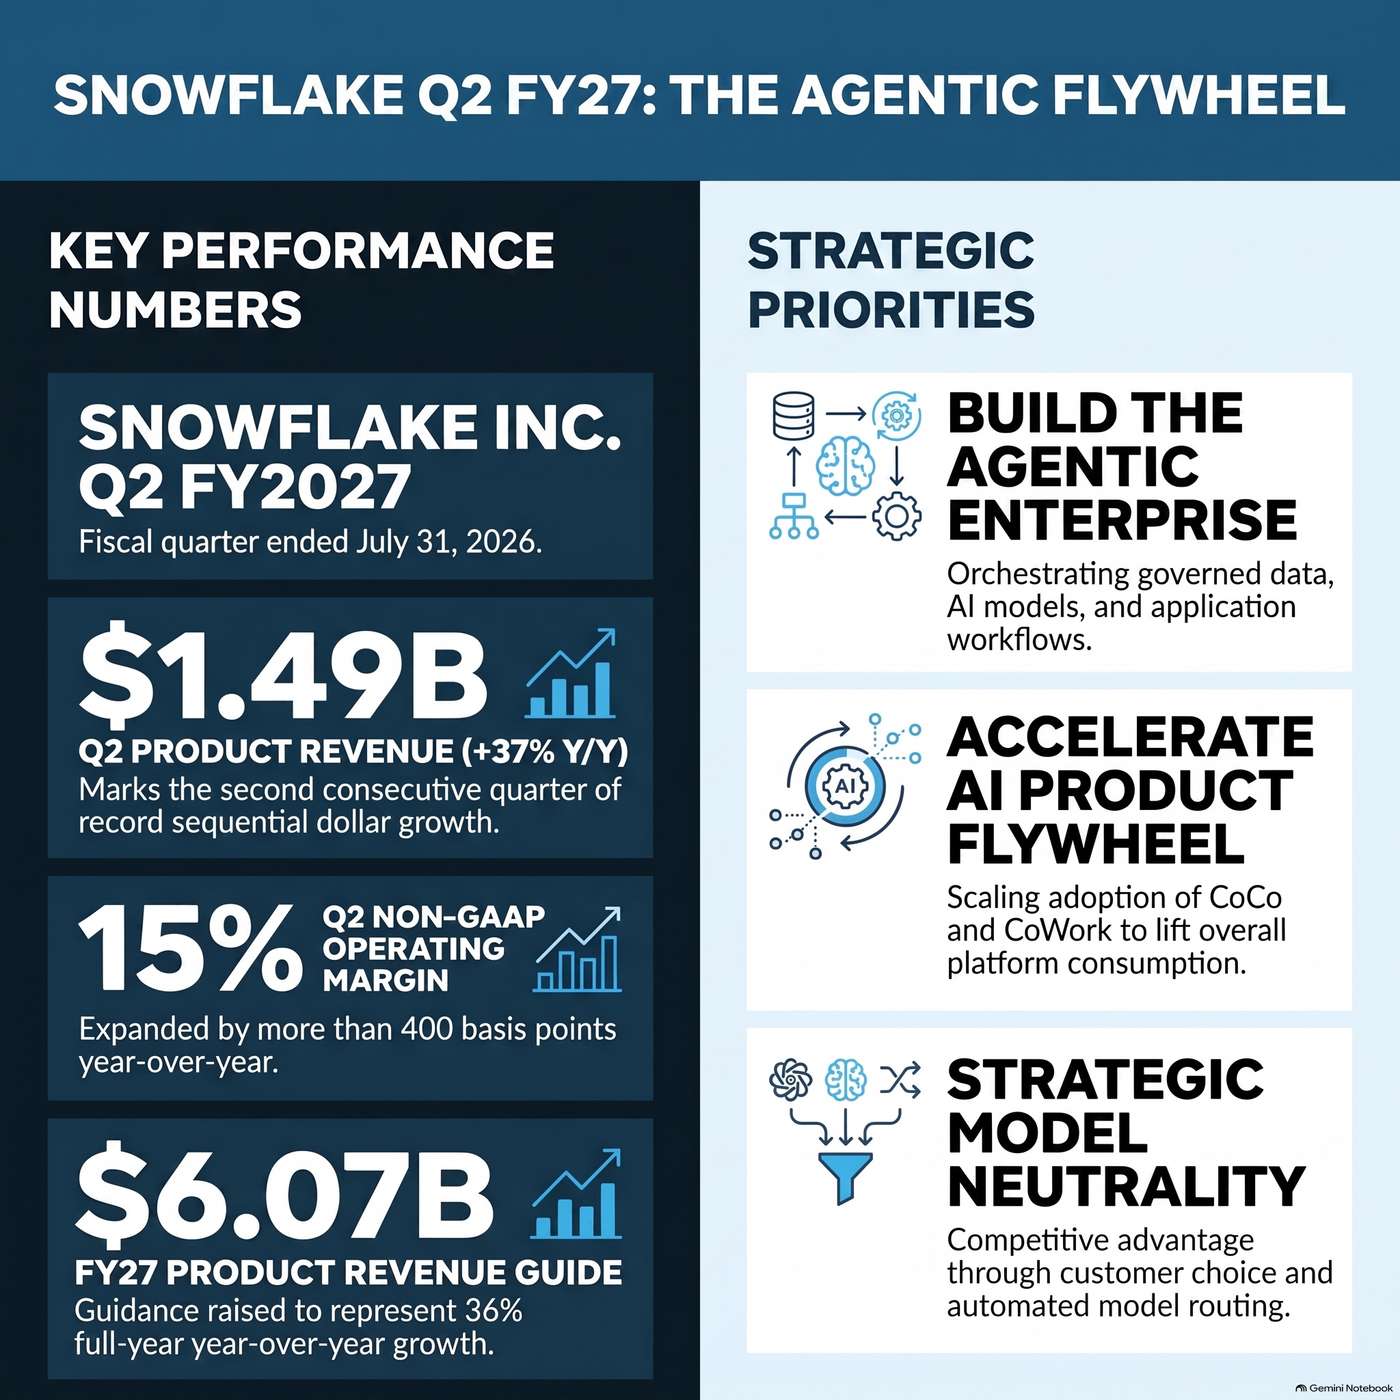 Snowflake Inc. (SNOW) Announced Q2 2027 Earnings on September 2, 2026, Reporting "Product revenue came in at $1.49 billion with growth accelerating to 37% year-over-year" 04.09.2026 17minFinancial Results For the second quarter of fiscal 2027, Snowflake reported product revenue of $1.49 billion, representing 37% year-over-year growth, which marks the company's third straight quarter of product revenue acceleration.Remaining performance obligations grew 30% year-over-year to reach $9 billion, with approximately 54% expected to be recognized as revenue in the next 12 months.The company achieved a net revenue retention rate of 126% and expanded its non-GAAP operating margin by more than 400 basis points year-over-year to 15%.Additionally, Snowflake ended the quarter with $4.3 billion in cash, cash equivalents, short-term, and long-term investments.Business Updates and Product Announcements Management highlighted strong traction in transitioning organizations into what they call the Agentic Enterprise.Their first-party AI products are seeing rapid adoption, with CoWork expanding to 5,800 accounts, representing nearly 11% quarter-over-quarter growth, while CoCo surpassed 9,100 accounts after adding more than 2,000 net new accounts in the quarter.Snowflake also introduced Cortex AI Gateway, which dynamically routes tasks to appropriate models with built-in cost and governance controls, integrating technology from the Natoma acquisition.Internally, management has deployed CoCo and CoWork across marketing, sales, and finance, including automating prospecting for over 125,000 contacts and leads.Forward Guidance For the third quarter of fiscal 2027, Snowflake expects product revenue between $1.588 billion and $1.593 billion, representing 37% to 38% year-over-year growth, with a non-GAAP operating margin of 15.5%.For the full fiscal year 2027, the company raised its product revenue guidance to $6.07 billion, representing 36% year-over-year growth, which includes approximately 1 percentage point of growth from Observe.Full-year non-GAAP operating margin guidance was increased from 13.5% to 14.5%, while the non-GAAP product gross margin is expected to be 74%, reflecting a higher revenue mix from fast-growing AI workloads that carry lower contribution margins.The company reiterated its full-year non-GAAP adjusted free cash flow margin guidance of 23%.
-
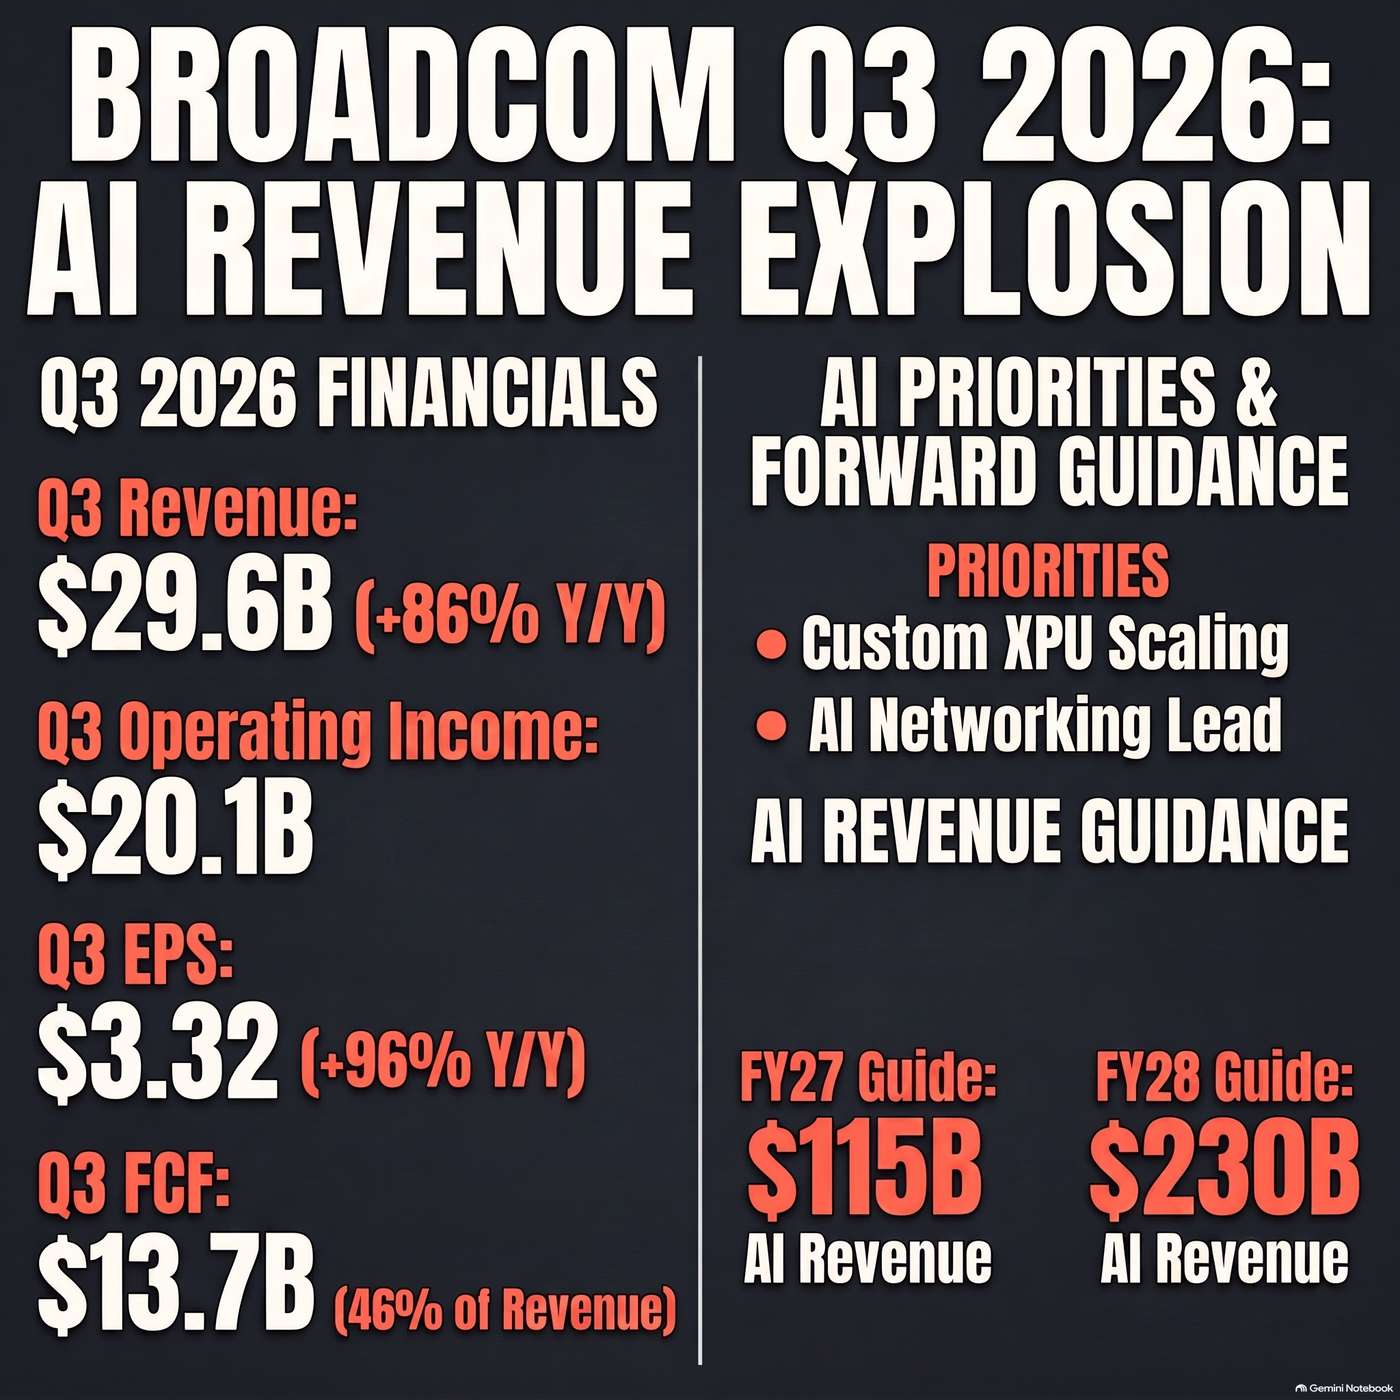 Broadcom Inc. (AVGO) Announced Q3 2026 Earnings on September 2, 2026, Reporting "Consolidated revenue was a record $29.6 billion for the quarter, up 86% year-on-year" 04.09.2026 21minBroadcom reported consolidated revenue of a record $29.6 billion for the third quarter of fiscal year 2026, representing an increase of 86% year-on-year.Gross margin for the quarter was 75% of revenue, which was down 210 basis points sequentially as AI semiconductor revenue was a greater proportion of the total revenue mix. Q3 operating income was a record $20.1 billion, representing an increase of 92% from a year ago.Operating margin reached a record 68% of revenue for the quarter.Non-GAAP EPS was $3.32 for the quarter, up 96% year-on-year.Free cash flow in the quarter was a record $13.7 billion, which represented 46% of revenue.The Semiconductor Solutions segment generated record revenue of $20.8 billion, which was up 127% year-on-year, with gross margin for the segment at approximately 67% and operating margin at 61%. AI semiconductor revenue reached $16.7 billion for the quarter, which grew 221% year-on-year.Infrastructure software revenue was $8.8 billion, representing a 29% increase year-on-year, with sustained ARR growth of 15% year-on-year.During the quarter, management highlighted substantial updates to its custom silicon and networking portfolio.Broadcom delivered the Ironwood TPU v7 in high volume to both Google and Anthropic, and started production shipments of the next-generation TPU version 8i to Google.The company also shipped Jalapeno, OpenAI's first-generation custom accelerator, which is optimized for inference workloads.For Meta, Broadcom expects production shipments of the custom MTIA accelerator in the fourth quarter. In networking, Broadcom taped out Tomahawk 7, the industry's first 200 terabit per second Ethernet switch. To support enterprise AI deployment, Broadcom announced the VMware Private AI Cloud.Financially, the company established the AI XPV platform in partnership with Apollo and Blackstone to enable more than 20 gigawatts of compute infrastructure by the end of 2028, and closed a first tranche of $35 billion in June for Anthropic's 1 gigawatt deployment.For the fourth quarter of fiscal 2026, Broadcom provided guidance expecting consolidated revenue of approximately $34.8 billion, which is up 93% year-on-year, with an operating margin of approximately 66%.Fourth-quarter semiconductor revenue is guided to approximately $26.1 billion, up 136% year-on-year, driven by expected Q4 AI semiconductor revenue of $21.7 billion, up over 236% year-on-year. Q4 consolidated gross margin is expected to be approximately 73%, down from 78% a year ago due to the increasing proportion of custom XPUs in the revenue mix.For the full fiscal year 2026, management expects AI revenue to reach $58 billion, representing a 186% increase year-on-year.Looking further ahead, management expects fiscal 2027 AI semiconductor revenue to double to approximately $115 billion, and fiscal 2028 AI semiconductor revenue to double again to approximately $230 billion, while targeting to exceed $30 in earnings per share in fiscal 2028.
-
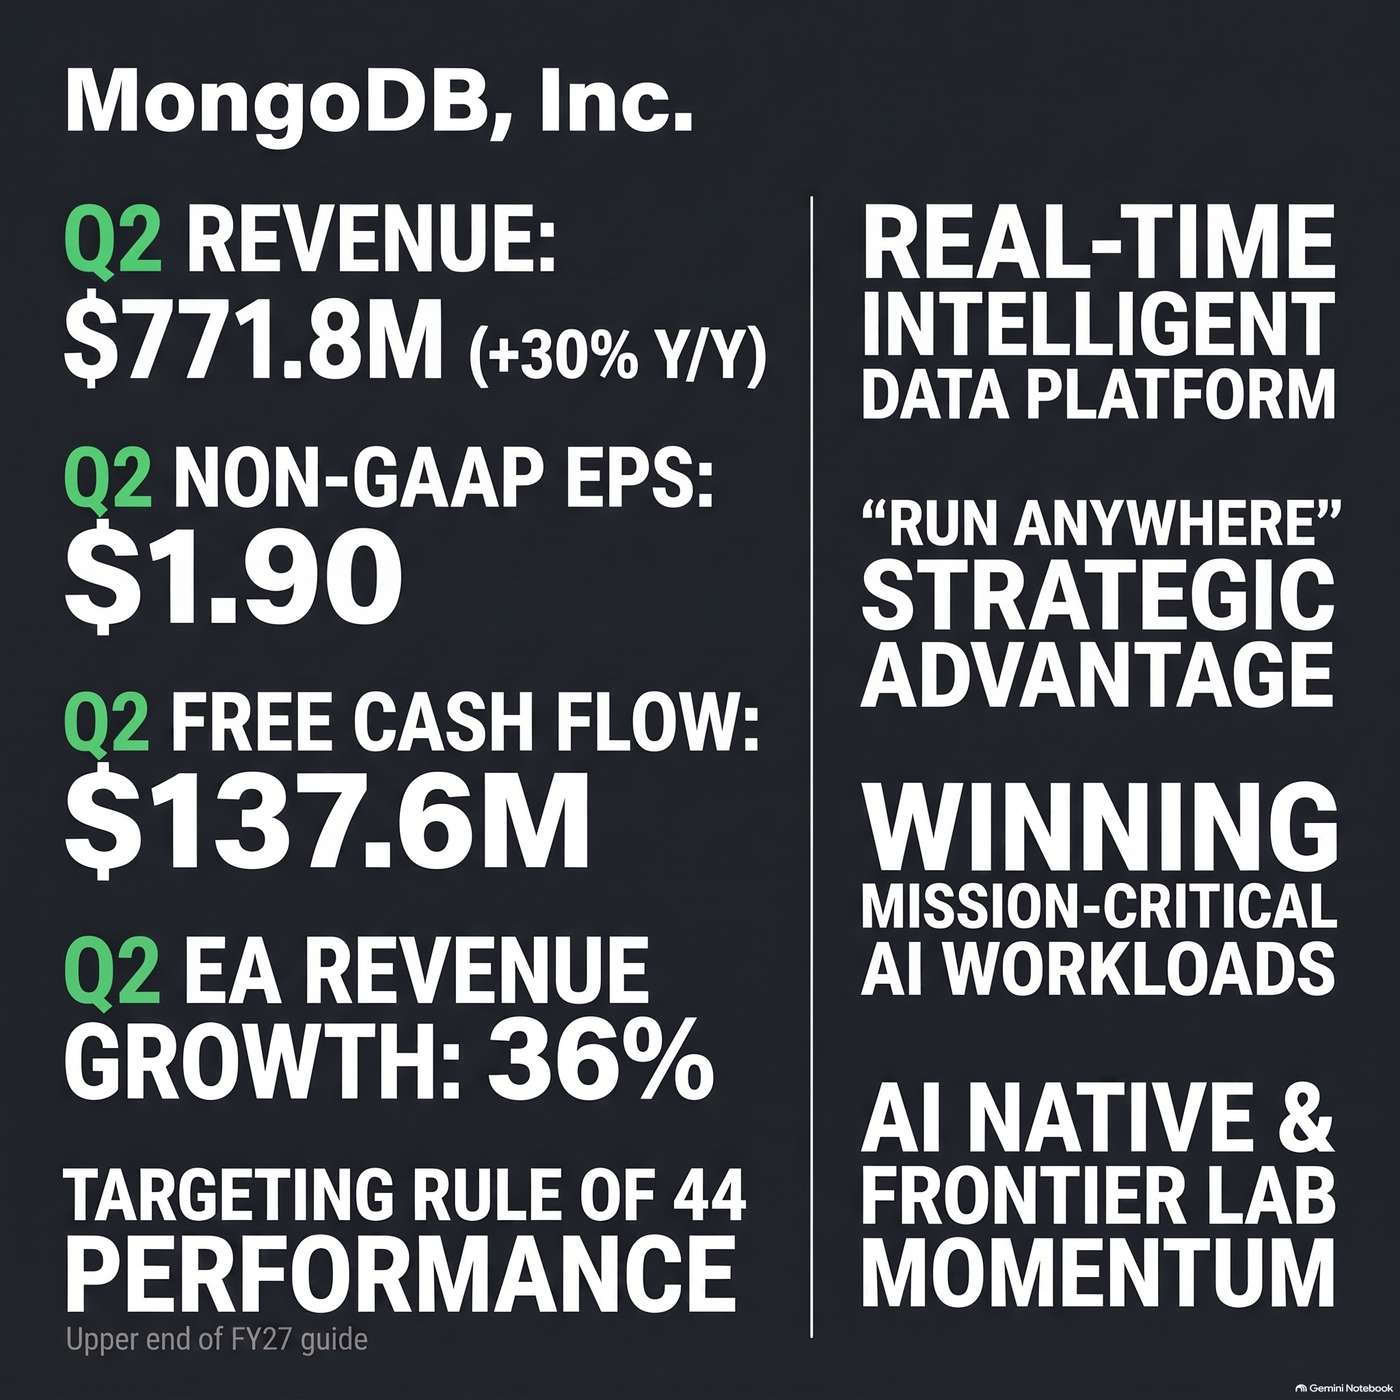 MongoDB, Inc. (MDB) Announced Q2 2027 Earnings on September 1, 2026, Reporting "Total revenue in the second quarter was $771.8 million representing 30% year-over-year growth" 04.09.2026 16minMongoDB reported strong financial results for the second quarter of fiscal year 2027.Michael Berry stated that "Total revenue in the second quarter was $771.8 million representing 30% year-over-year growth" compared to 24% growth in the year-ago period.Atlas revenue grew approximately 29% year-over-year, marking the sixth straight quarter of year-over-year dollar growth, adding a "record $127 million in the quarter". Chirantan Desai reported that "EA and other had a standout quarter, growing 36% year-over-year due to widespread strength driven by our run anywhere capabilities", while Michael Berry noted that EA and other revenue grew approximately 30% year-over-year.The company delivered a non-GAAP gross margin of 75.9% and non-GAAP income from operations of $185.9 million, resulting in a non-GAAP operating margin of 24%.Second quarter non-GAAP net income was $162.6 million, or $1.90 per share.Operating cash flow was $141.9 million and free cash flow was $137.6 million, bringing first-half free cash flow to $335 million.In terms of business updates, Chirantan Desai highlighted that MongoDB is "emerging as the real-time intelligent data platform for modern application in the multi-cloud and AI era." The company ended the quarter with 70,600 total customers, adding a sequential record of approximately 2,900 net new customers.Desai pointed out that "Voyage customer count nearly doubled quarter-over-quarter" and "Atlas Vector Search adoption continues to outpace the growth of the rest of the company, showing our strong early momentum for AI workloads." Additionally, total company net ARR expansion rate increased to 122% from 121% in the prior quarter. To expand its developer reach, MongoDB launched a managed Model Context Protocol Server, allowing developers and agents to connect directly to MongoDB when using tools such as Claude Code, Codex, Grok Build, Cursor, and Devin.For the third quarter of fiscal year 2027, management expects total revenue of $756 million to $761 million, representing 20% to 21% year-over-year growth.Non-GAAP income from operations is projected to be $152 million to $156 million, with non-GAAP net income per share of $1.57 to $1.61.For the full year fiscal 2027, MongoDB raised its guidance, expecting total revenue of $2.99 billion to $3.03 billion, representing growth of 21% to 23%.Non-GAAP income from operations is expected to be $616.3 million to $636.3 million, with non-GAAP net income per share of $6.39 to $6.58.Michael Berry noted that full-year Atlas revenue growth is expected to be approximately 27% and that "EA and other is projected to grow at a double-digit rate for the full year" at approximately 11% growth.Operating margin is expected to expand by approximately 250 basis points, and full-year free cash flow conversion is anticipated to be at the upper end of the 80% to 100% target range.On the product and partnership front, MongoDB launched Search and Vector Search capabilities on Enterprise Advanced during the second quarter.Desai noted this addresses customer interest in taking a consolidated approach to building artificial intelligence in governed, self-managed environments. In addition, MongoDB introduced Automated Voyage Embeddings in Atlas for one-click Vector Search setup, launched the voyage-code-4 model purpose-built for code, and released an upgraded Reranking API. A key partnership integration with Claude was highlighted, featuring Anthropic's Chief Commercial Officer Paul Smith, who commented that a new managed MCP Server allows developers to "explore query and manage their MongoDB data without ever leaving Claude."📈 Would you like me to draft some social media tweets or a brief analysis of the analyst Q&A from this Q2 call to accompany these show notes?
-
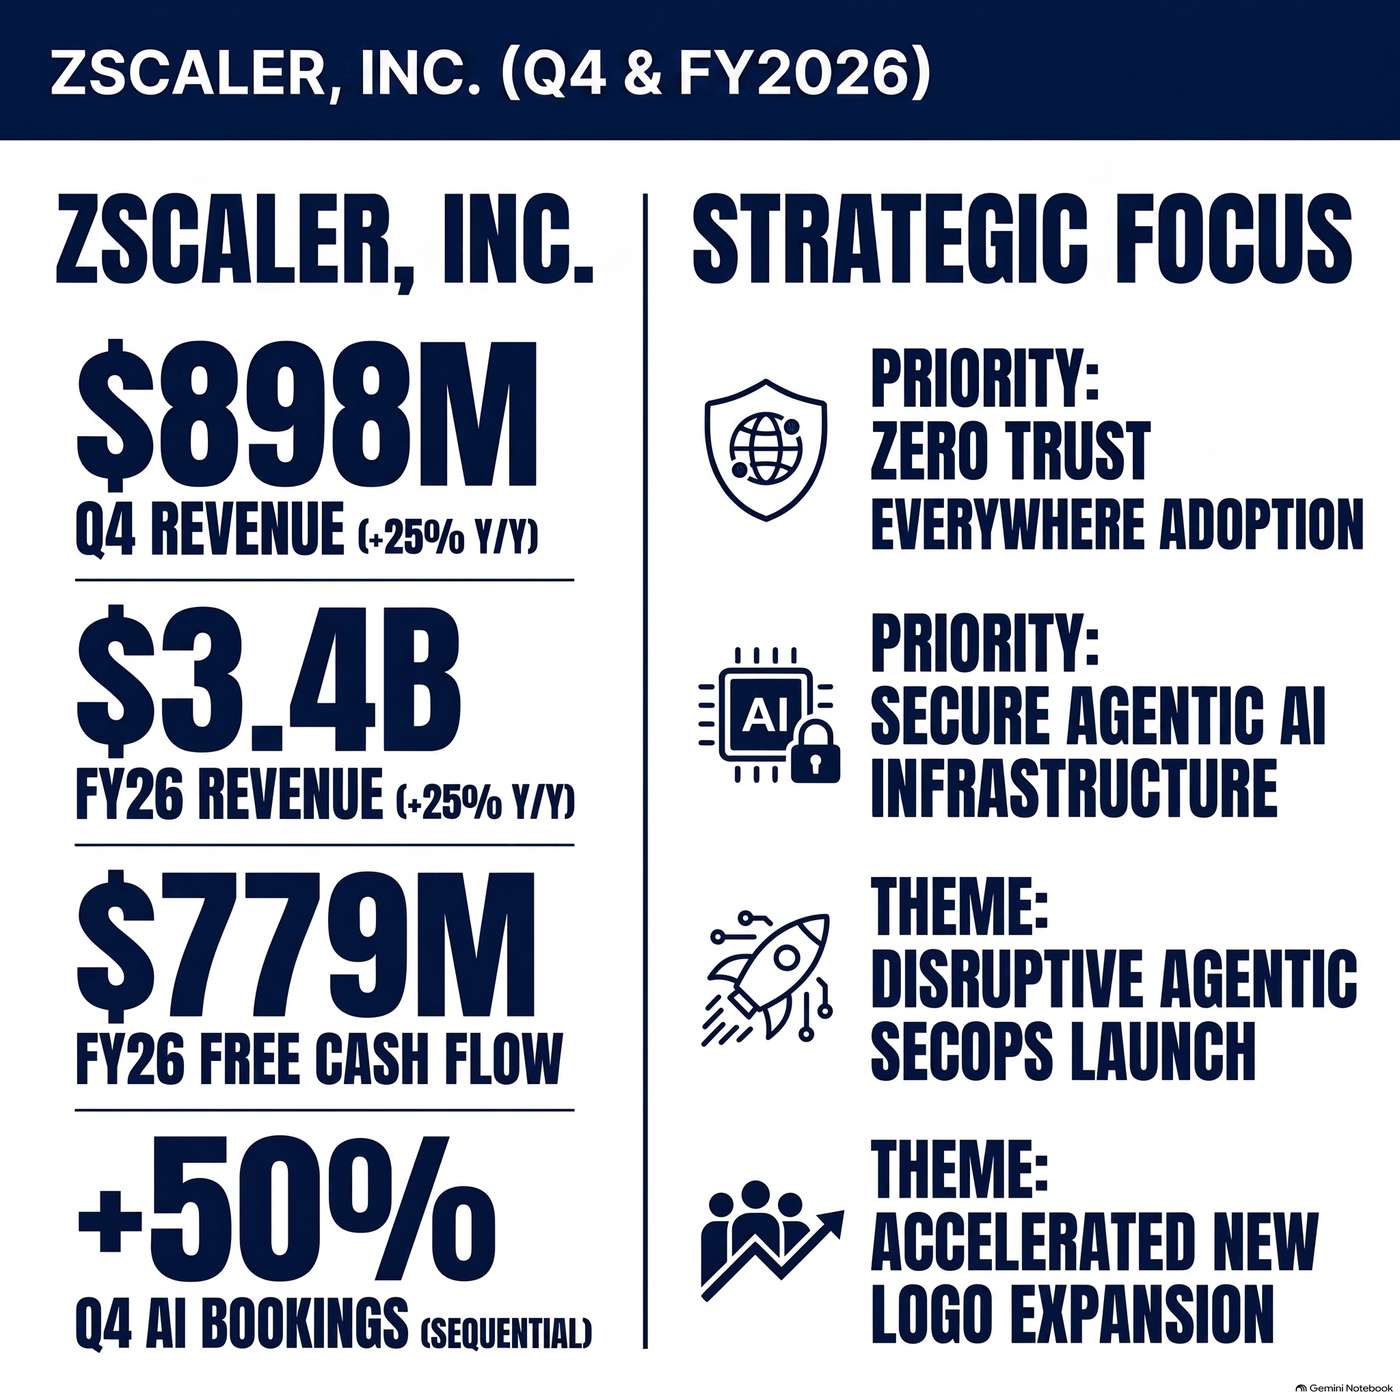 Zscaler, Inc. (ZS) Announced Q4 2026 Earnings on September 3, 2026, Reporting "Q4 revenue was $898 million, up 25% year-over-year" 04.09.2026 13minZscaler, Inc. reported financial results for the fourth quarter and full fiscal year 2026.For the fourth quarter, revenue was $898 million, representing an increase of 25 percent year-over-year and 6 percent sequentially.Non-GAAP operating income for the fourth quarter was $218 million, up 37 percent year-over-year, with a record non-GAAP operating margin of 24.3 percent and non-GAAP gross margin of 80.2 percent.For the full fiscal year 2026, revenue reached $3.4 billion, growing 25 percent year-over-year, and total annual recurring ARR reached $3.8 billion, also up 25 percent.Full-year non-GAAP operating margin was 22.9 percent, and full-year free cash flow was $779 million, representing a free cash flow margin of 23 percent.The company ended the fiscal year with approximately $3.5 billion in cash, cash equivalents, and short-term investments, against $1.7 billion of debt.In terms of strategic updates, Zscaler announced a workforce restructuring affecting approximately 3 percent of its employees to strategically reallocate resources to support AI and growth initiatives.This action is expected to result in restructuring charges of approximately $30 million to $33 million.The company highlighted strong adoption of its Zero Trust Everywhere platform, exiting the fiscal year with more than 950 Zero Trust Everywhere enterprises, up from over 700 in the third quarter.Zscaler’s Z-Flex procurement program continues to show momentum, generating over $770 million in total contract value during the fourth quarter and more than $1.7 billion for the full fiscal year.The company discussed its upcoming Agentic SecOps solution, which integrates Zscaler’s in-line telemetry with Red Canary’s managed detection and response experience, launching on September 9. Additionally, Zscaler highlighted an expanded partnership with Carahsoft to penetrate commercial and SMB segments, and extended its Zero Trust Cloud solution by offering a managed service through Google Cloud.For the first quarter of fiscal 2027, Zscaler expects revenue of $935 million to $939 million, representing approximately 19 percent year-over-year growth, and non-GAAP operating profit of $215 million to $217 million.For the full fiscal year 2027, the company guided for revenue of $3.908 billion to $3.938 billion, reflecting year-over-year growth of 16.6 percent to 17.5 percent, and total annual recurring ARR of $4.396 billion to $4.426 billion.Non-GAAP operating profit for the full year is projected to be between $924 million and $932 million, representing an operating margin of approximately 23.7 percent, and free cash flow margin is expected to be approximately 23 percent to 23.5 percent.Management noted that capital expenditures are expected to remain elevated in fiscal 2027 due to higher component pricing, particularly for memory, storage, and processors.
-
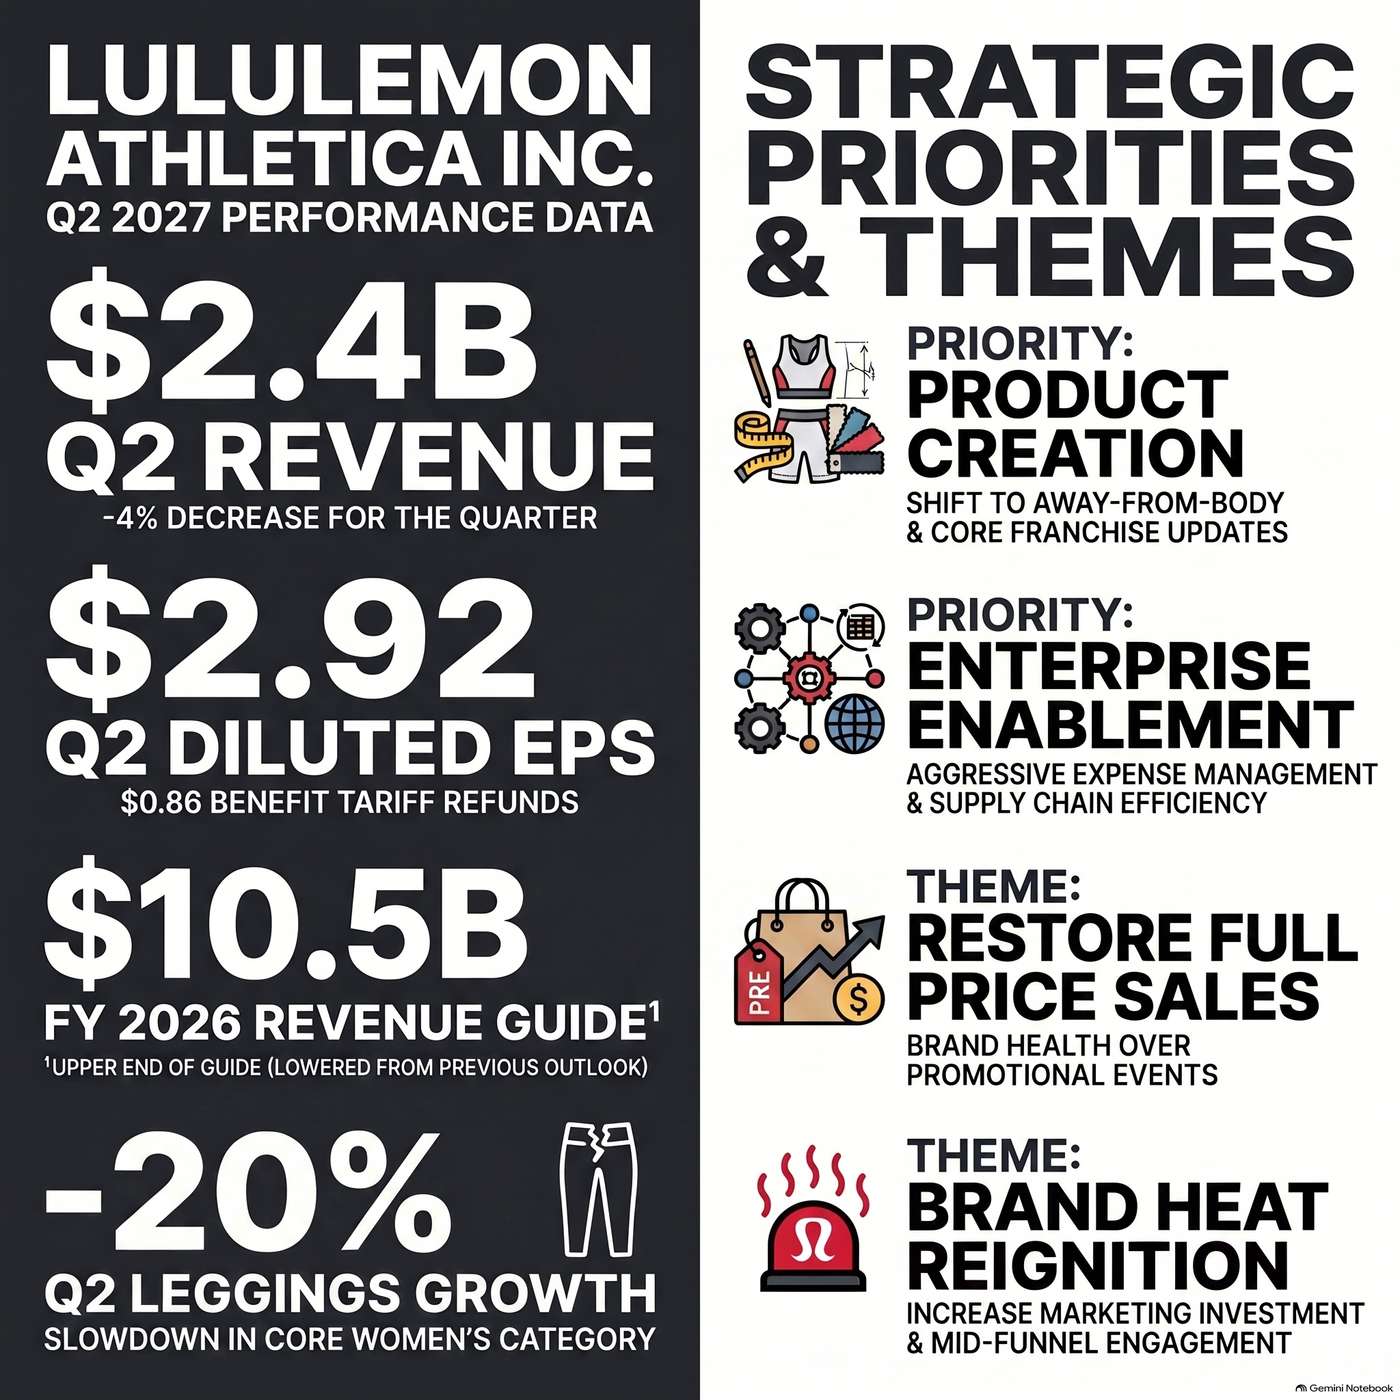 lululemon athletica inc. (LULU) Announced Q2 2026 Earnings on September 3, 2026, Reporting "total net revenue decreased 4% or 5% in constant currency to $2.4 billion" 04.09.2026 19minFor the second quarter of 2026, interim Co-CEO and CFO Meghan Frank reported that "total net revenue decreased 4% or 5% in constant currency to $2.4 billion" for the quarter and "comparable sales decreased 10%" for the quarter.She stated "gross profit for the second quarter was $1.46 billion, or 60.5% of net revenue" and "operating income for the quarter was $454 million, or 18.8% of net revenue", which included a "$134.5 million pretax benefit from IEEPA tariff refunds" for the quarter.She also noted "net income for the quarter was $329 million, or $2.92 per diluted share, compared to $3.10 for the second quarter of 2025" and "inventory at the end of Q2 is $1.7 billion, a decrease of 1% on a dollar basis".Management discussed their action plan focused on three pillars: "product creation, product activation and enterprise enablement", with the goal of "returning to full price sales growth". To optimize North America store channels, the company has "decreased SKUs by 15%" to ensure a less dense presentation and is leveraging its chase capabilities by "chasing approximately 20% more volume this year relative to last year". On expenses, they are taking an "aggressive stance on expense management", moderating head count growth, and planning "approximately 35 net new store openings this year", down from forty last quarter. In addition, the company is preparing for its "incoming CEO, Heidi O'Neill, joins us next week" to evaluate their strategy and action plans.In products and brand activations, the company saw leggings sales decline "approximately 20% in Q2" but found "good traction in several of our away-from-body styles" including the "Groove Wide-Leg", the "Align Foldover Jogger", the "Breezily", and the "updated Dance Studio Pant". Men's category performance saw "strength in Metal Vent Tech tees and our golf tops" for the quarter, supported by storytelling campaigns around elite ambassadors "Lewis Hamilton and Min Woo Lee". On brand activation, the company celebrated the return of the "SeaWheeze Half Marathon and Festival" in Vancouver with nearly 10,000 runners, as well as the launch of its yoga "summer series" across 70 cities. In China Mainland, they launched the "Together Feels Better" campaign and highlighted tennis ambassador "Guo Hanyu", who became "the first Chinese athlete in our ambassador roster to win a Grand Slam tennis title during Wimbledon".For the third quarter of 2026, the company expects revenue for the quarter to be "in the range of $2.29 billion to $2.32 billion, representing a decline of 10% to 11%" and earnings per share for the quarter "in the range of $0.93 to $0.98 versus EPS of $2.59 a year ago". For the full year fiscal 2026, management lowered its guidance and now expects full year revenue "in the range of $10.35 billion to $10.5 billion, down 5% to 7% relative to 2025". Full year diluted earnings per share are expected "in the range of $9.48 to $9.73 versus EPS of $13.26 in 2025", and the company anticipates full year capital expenditures "to be approximately $680 million to $700 million".
-
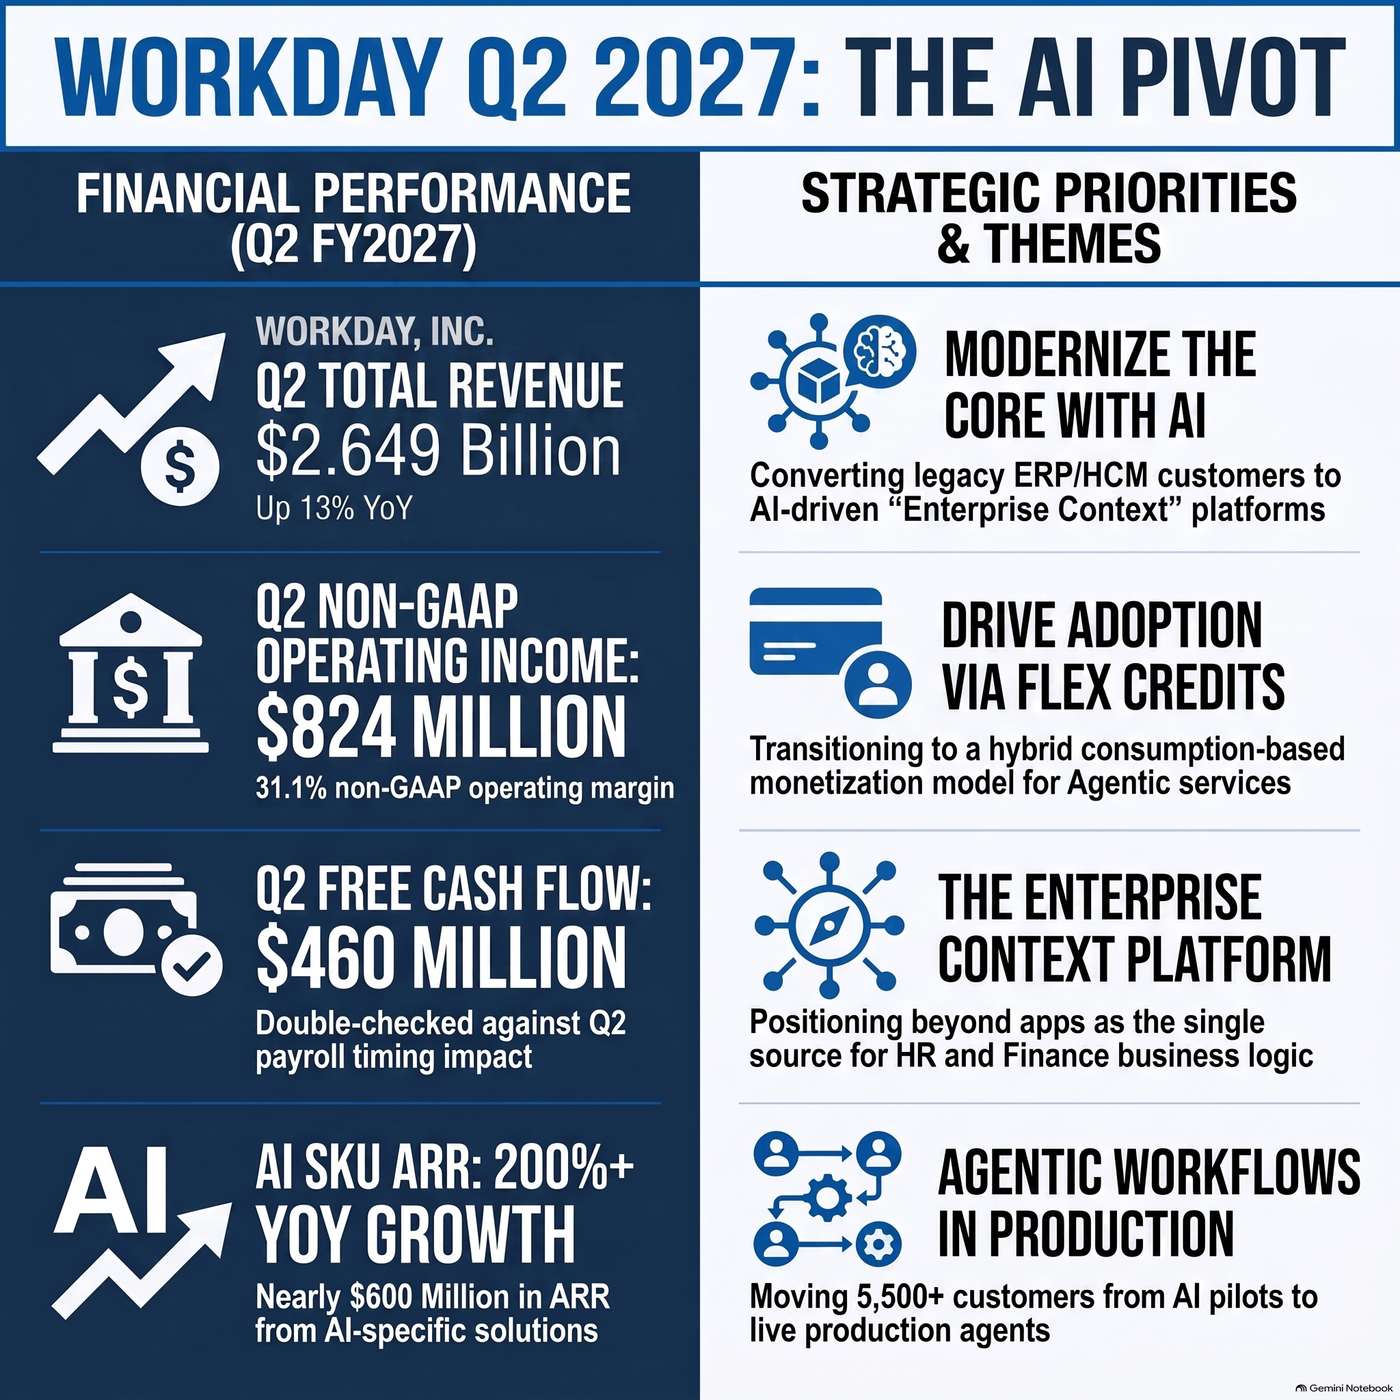 Workday, Inc. (WDAY) Announced Q2 2027 Earnings on August 27, 2026, Reporting "Subscription revenue in Q2 was $2.471 billion, up 14%" 27.08.2026 21minWorkday, Inc. reported its second quarter fiscal year 2027 results.Subscription revenue in Q2 was $2.471 billion, up 14%.Professional services revenue was $178 million, resulting in total revenue of $2.649 billion, growth of 13%.Non-GAAP operating income was $824 million for the quarter, representing a non-GAAP operating margin of 31.1%.Operating cash flow totaled $520 million in the quarter, and free cash flow was $460 million.The company's 12-month subscription revenue backlog, or cRPO, ended the quarter at $9.03 billion, up 14.2%.Total subscription revenue backlog ended Q2 at $27.4 billion, up 8% from a year ago.Gross revenue retention was 97% for the quarter.The company also completed its $5 billion share repurchase plan six months ahead of target by repurchasing $1.3 billion of shares in Q2, and the board approved a new $4 billion open-ended share repurchase program.Chief Executive Officer Aneel Bhusri highlighted that AI products alone drove more than $100 million of new ACV, which accounted for more than 25% of all new ACV closed in the quarter.Management emphasized rapid customer adoption, noting that "more than 5,500 customers are using one or more of our organic agents," representing an increase of "more than 35% from last quarter." Furthermore, Gerrit Kazmaier stated that the company achieved "nearly $600 million in ARR from our AI SKUs," which is up more than 200% year-over-year and up over 20% from last quarter.Management focused heavily on driving adoption and transition to the "Flex credit consumption model." In medium enterprise, Rob Enslin noted that customer volume increased "more than 5x over Q1."For forward guidance, Workday increased its FY 27 subscription revenue outlook to a range of $9.94 billion to $9.95 billion, representing a growth of 13%.For the third quarter of fiscal year 2027, the company expects subscription revenue of approximately $2.515 billion, growth of 12%, and third quarter cRPO growth of 11% to 12%.Workday increased its full-year FY 27 non-GAAP operating margin guidance to 31%, with Q3 non-GAAP operating margin expected to be approximately 30%.The company expects FY 27 capital expenditures of approximately $270 million, resulting in full-year FY 27 free cash flow of $3.18 billion.Additionally, management expects the non-GAAP operating margin to expand by "at least 2 percentage points next year."During the quarter, Workday announced that Adaptive Decision Intelligence entered general availability on July 31, with 170 customers having already purchased it.The company launched Sana Enterprise and combined Sana Learn with its core learning management system, which more than tripled the overall learning business quarter-over-quarter.Workday also introduced Sana Agent Builder, which allows users to create custom agents in natural language. In partnerships, Cisco joined as a launch partner for Agent Passport, bringing Cisco AI Defense to protect agents in production.The company formed new relationships with KPMG U.S., Danske Bank, BWX Technologies, and Guidehouse.
-
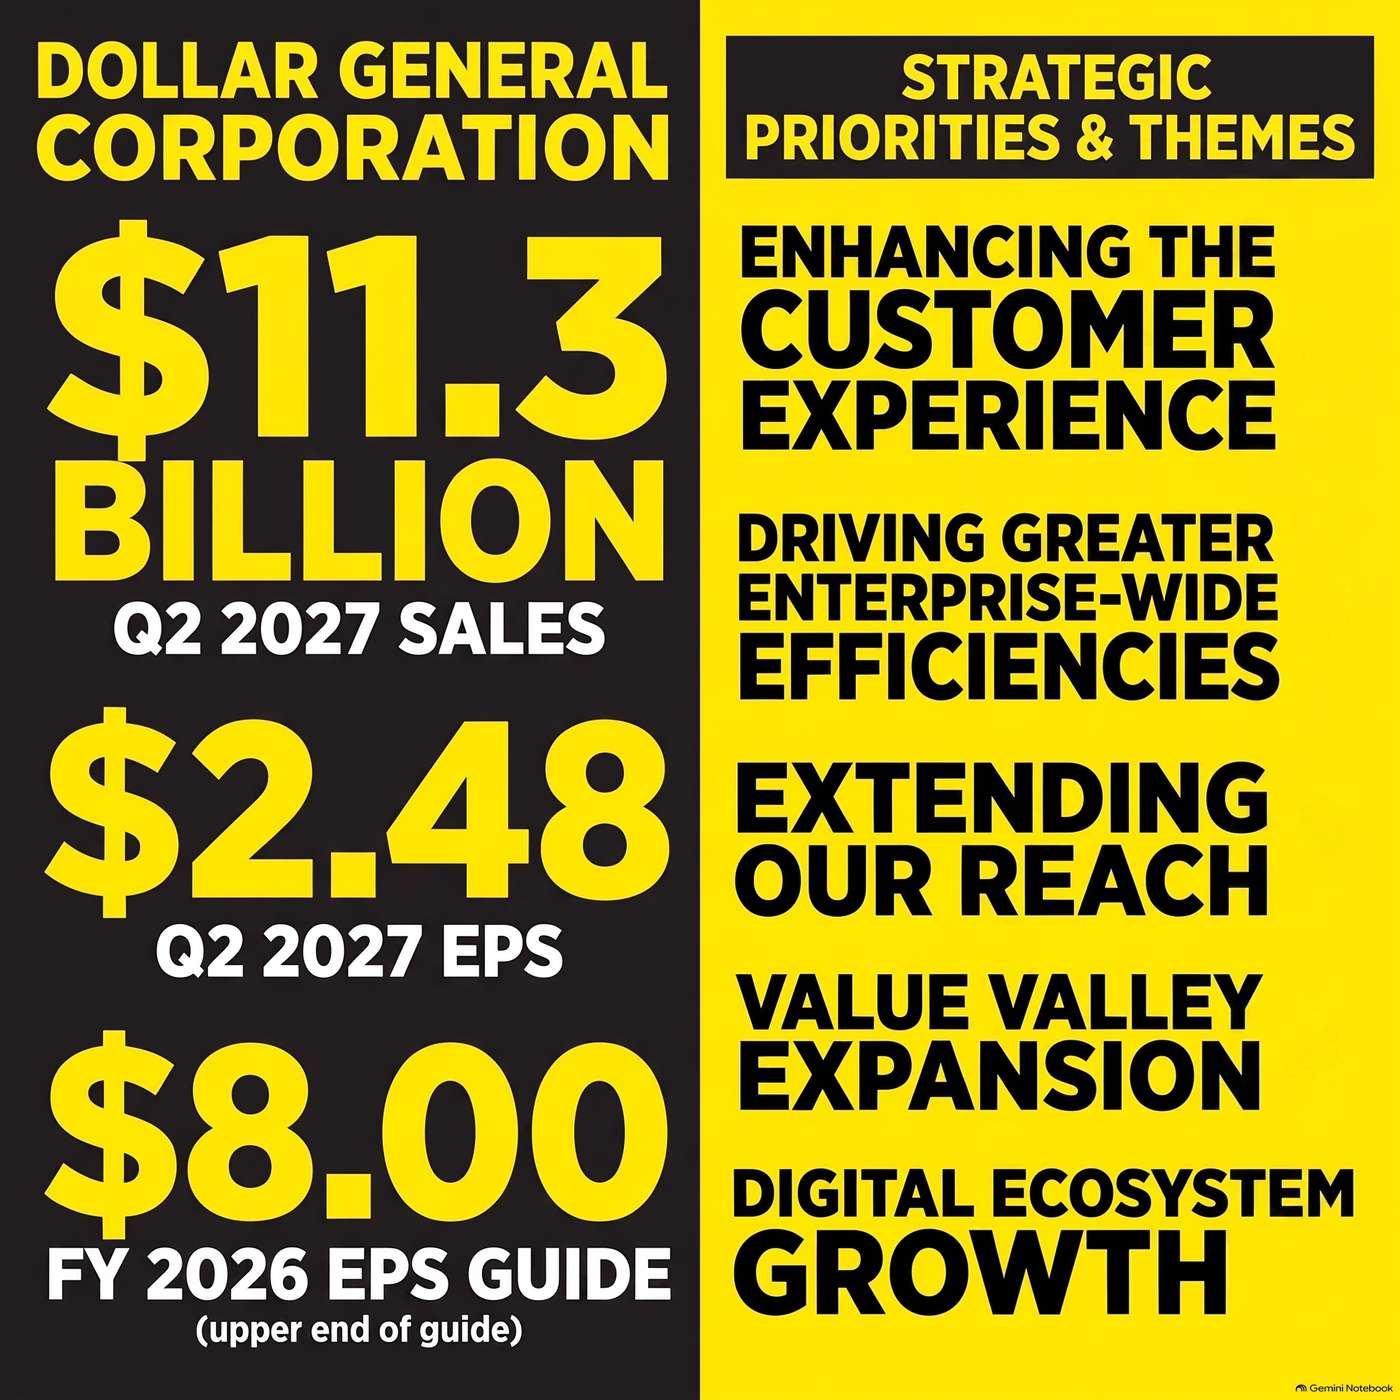 Dollar General Corporation (DG) Announced Q2 2026 Earnings on August 27, 2026, Reporting "Net sales for the quarter increased 5.2% to $11.3 billion" 27.08.2026 20minFor the second quarter of 2026, Dollar General reported that "Net sales for the quarter increased 5.2% to $11.3 billion" compared to net sales of "$10.7 billion in last year's second quarter". Management stated that "Same-store sales increased 3.5% during the quarter" which was driven by customer traffic growth of "2%" and average basket growth of "1.5%". "For Q2, gross profit as a percentage of sales was 32.6%, an increase of 127 basis points", and "Operating profit for the second quarter increased 29.2% to $769 million". Net interest expense was "$42.9 million" and the effective tax rate was "24.2%". Finally, "EPS for the quarter increased 33% to $2.48". The company also reported that year-to-date they "generated significant cash flow from operations of $1.5 billion".Management highlighted progress on their four strategic growth pillars: "enhancing the customer experience, elevating our brand, driving greater enterprise-wide efficiencies and extending our reach". To elevate their brand, the company made significant progress on store remodels, completing "1,324 Project Renovate remodels and 1,422 Project Elevate remodels through the end of Q2" toward full-year goals of executing 2,000 and 2,250 of these remodels, respectively. On the digital front, executives noted that collective delivery offerings have generated "a strong sales incrementality rate of approximately 80%". Within their store footprint, they expanded their dollar off-shelf display presence in "more than 9,000 stores" and noted that the "Value Valley offering once again significantly outperformed the chain average in Q2 with comp sales increases of more than 16%".Due to strong performance, Dollar General raised its full-year outlook.For fiscal 2026, the company now expects "net sales growth in the range of 4% to 4.3%", "same-store sales growth in the range of 2.5% to 2.9%", and "EPS in the range of $7.80 to $8". This updated EPS range includes "the approximate $0.25 Q2 benefit from tariff refunds after related reinvestments" and contemplates "up to $700 million of share repurchases in the back half of the year", which they plan to resume in the third quarter.They also expect "modest SG&A deleverage in 2026" as they continue to invest in key initiatives.In product and partnership updates, Emily Taylor discussed the expansion of their Retail Media Network, noting they had "approximately $170 million in annual volume" at the end of last year and plan to pilot "subscription and loyalty" at the end of this year with a full rollout in 2027.Todd Vasos highlighted that the $1 price point consists of "over 2,000 items across the store at or below the $1 price point", including the rotating "Value Valley offering" of "more than 600 rotating items". The company expanded its delivery reach "through multiple avenues, including our myDG Delivery offering as well as through third-party partnerships of DoorDash and Uber Eats". Additionally, the company opened "1 Mi Super Dollar General in Q2, bringing us to a total of 22 stores in Mexico".
-
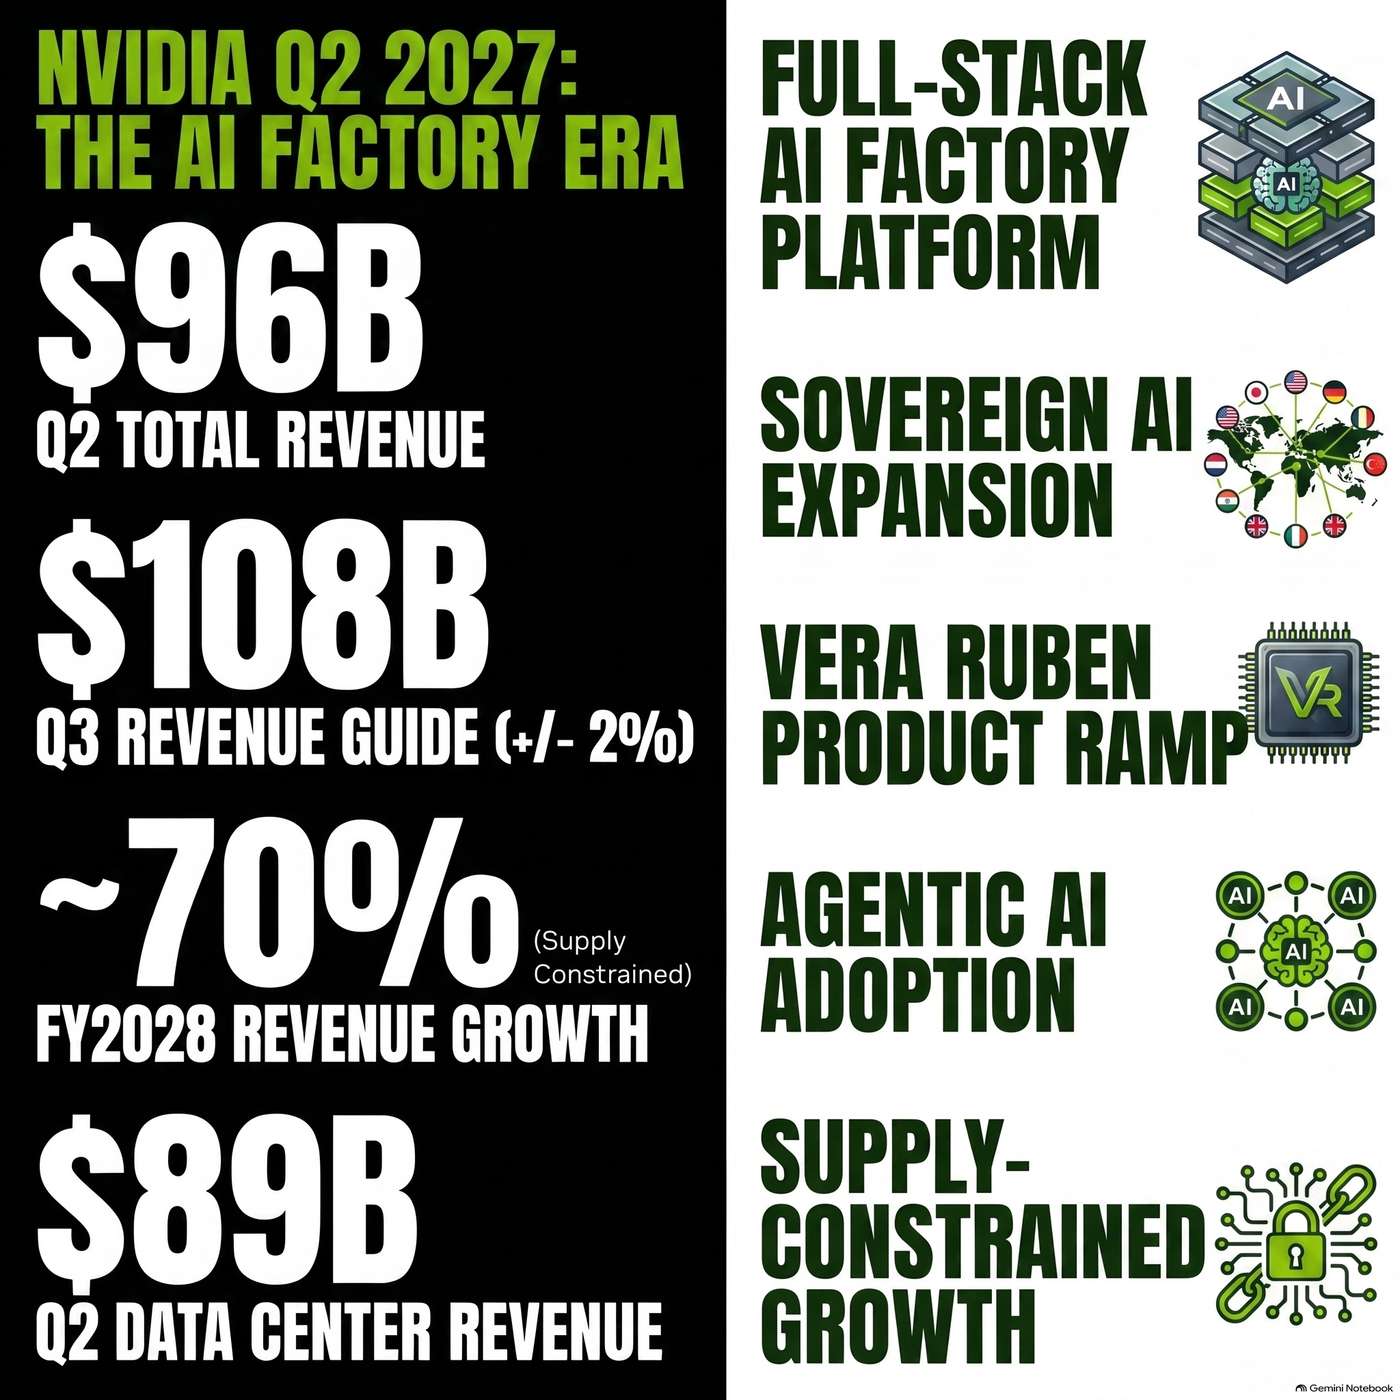 NVIDIA Corporation (NVDA) Announced Q2 2027 Earnings on August 26, 2026, Reporting "Total revenue of $96 billion more than doubled year-over-year as growth accelerated for the fourth consecutive quarter" 27.08.2026 20minNVIDIA Corporation reported financial results for the second quarter of fiscal year 2027.Executive Vice President and Chief Financial Officer Colette Kress announced "record revenue, operating income and EPS". Total revenue for the second quarter was reported as "$96 billion," which "more than doubled year-over-year as growth accelerated for the fourth consecutive quarter". The Data Center segment generated quarterly revenue of "$89 billion," which "increased 18% quarter-over-quarter". Within Data Center, hyperscale quarterly revenue was "$49 billion," which "grew 13% sequentially". AC I&E quarterly revenue was "$40 billion," representing an increase of "25% sequentially and 138% year-over-year". For the second quarter, both GAAP and non-GAAP gross margins were reported at "75%". GAAP and non-GAAP operating expenses for the second quarter were "up 10% and 11% sequentially". On the balance sheet, inventory increased to "$32 billion," and days of sales outstanding was reported as "60 days". During the second quarter, the company returned a record "$26 billion to shareholders," consisting of "$20 billion through share repurchases and $6 billion through our quarterly dividend of $0.25 per share".In terms of key business updates, management highlighted significant expansion in partnerships and product development.The company announced an expanded partnership with AWS, which is deploying "an additional 2 million GPUs starting this quarter through the second quarter of fiscal '29 along with Vera, CPUs, some integrated with Ruben, other standalone" and AWS will adopt NVIDIA's "full physical AI stack, Omniverse, Cosmos, Isaac, and Jason to power its fleet of warehouse robots". Furthermore, to support the build-outs of Frontier AI labs, NVIDIA announced partnerships with "6 of the world's leading infrastructure capital providers, Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to establish financing platforms that will raise over $500 billion of third-party capital". The company also secured land power shell capacity through a partnership with SoftBank Energy to exclusively host NVIDIA compute at their Portsmouth Campus, with the initial deployment "expected to support 4.25 gigawatts of AI factory capacity" to be utilized by OpenAI. In hardware, production shipments of "vera ruben" commenced "earlier this month". Additionally, NVIDIA announced that "Grok 3 LPX, our first rack scale LPU system is in full production" and expects to ship them "in volume later this quarter". Standalone production of the next-generation "Vero CPU" is also underway, and Grace CPU revenue exceeded "$5 billion" on a trailing 12-month basis.For the third quarter of fiscal year 2027, NVIDIA expects total revenue to be "$108 billion, plus and minus 2%". Sequential growth is expected to be driven primarily by "ACI and E," and management projects that "verarubin" will account for "about 20% of data center revenue in Q3". GAAP and non-GAAP gross margins for the third quarter are expected to be "74% plus or minus 50 basis points". Management expects gross margins to "bottom in Q4 in the 71% to 72% range before settling at 72% to 73% in fiscal year '28, as executed price increases take effect in Q1". For the full fiscal year 2027, GAAP and non-GAAP tax rates are expected to be "between 16% and 18%". In terms of preliminary outlook for the full fiscal year 2028, the company expects revenue to grow "approximately 70% year-over-year" under a supply-constrained outlook where supply is expected to "remain a bottleneck, at least through the end of fiscal year '28".I can also draft other podcast variants if you want to focus on a different thematic angle.
-
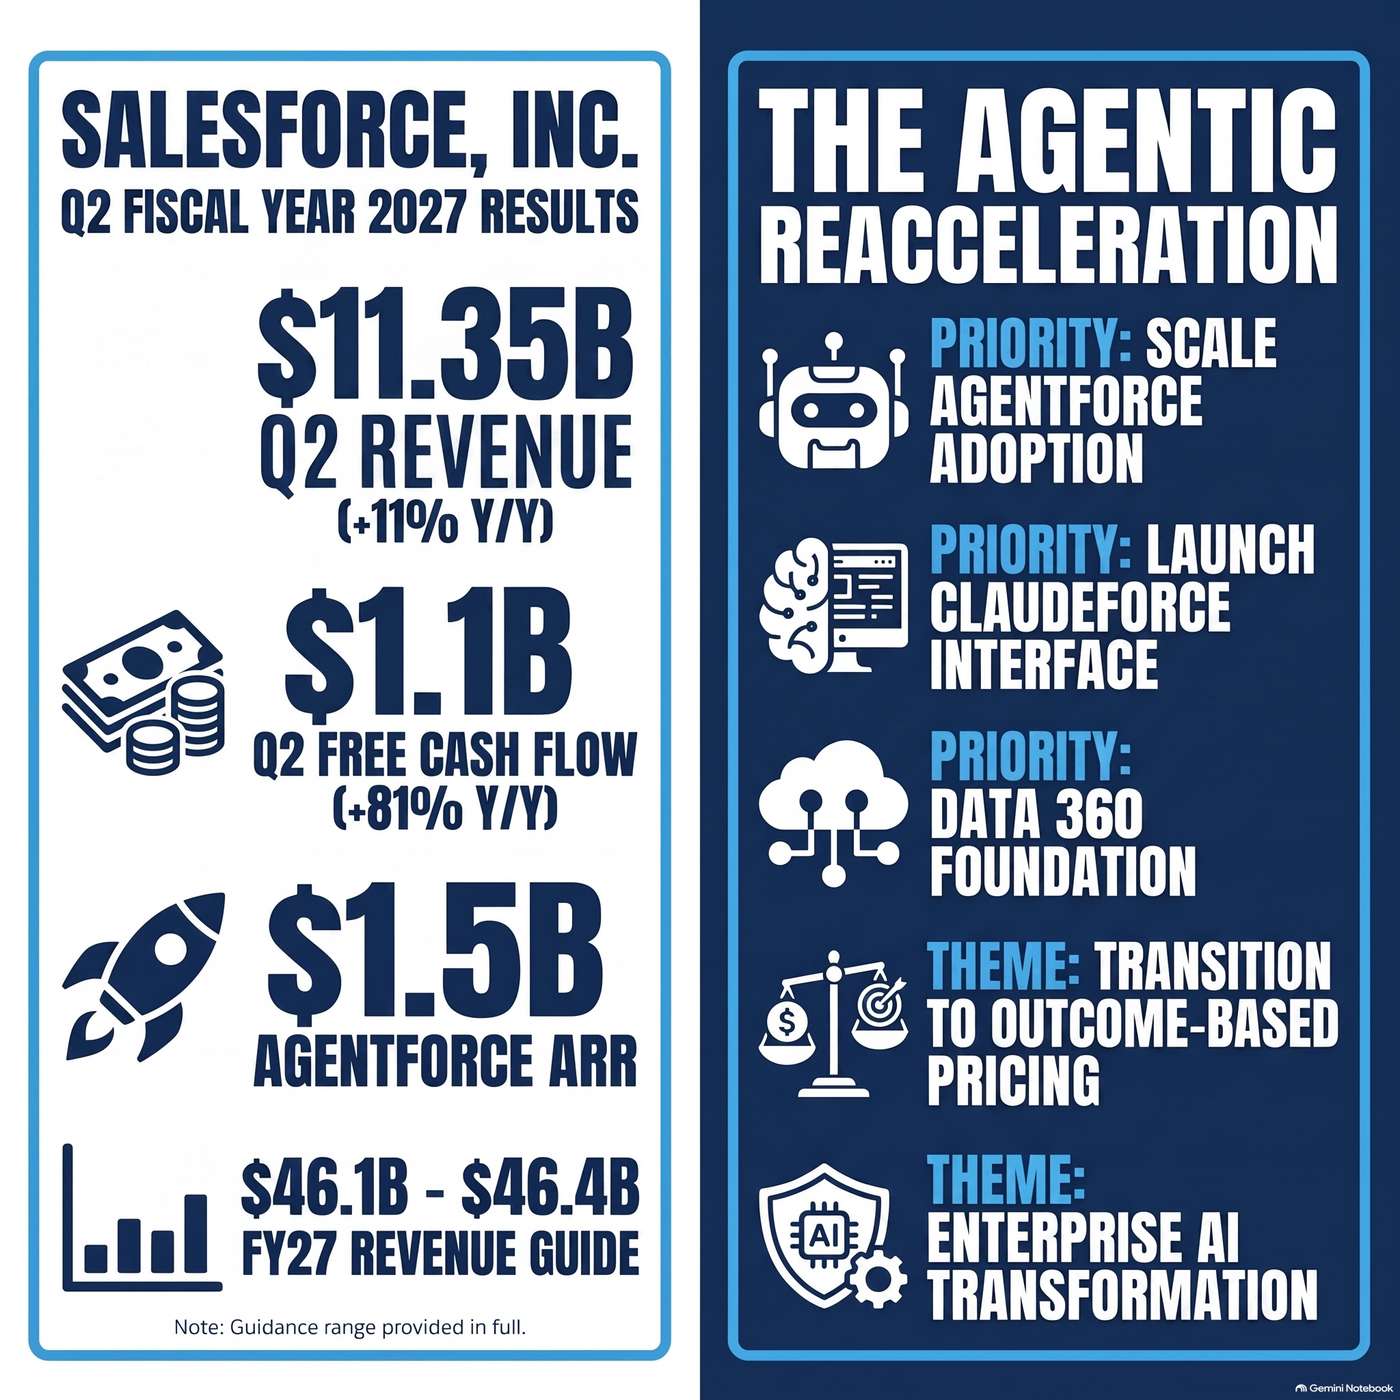 Salesforce, Inc. (CRM) Announced Q2 2027 Earnings on August 26, 2026, Reporting "Q2 revenue came in at $11.35 billion" 27.08.2026 21minSalesforce delivered record second-quarter financial results. Q2 revenue came in at "$11.35 billion", which was up 11% year-over-year.Subscription and support revenue was "$10.82 billion", up 12% year-over-year in nominal and 11% in constant currency.Current remaining performance obligation ended the quarter at "$33.5 billion", up 14% in constant currency.The company achieved a Q2 non-GAAP operating margin of "34.1%" and a GAAP operating margin of "20.5%". Free cash flow for the quarter was "$1.1 billion", representing an increase of 81% year-over-year.Additionally, the company continues its "$25 billion accelerated share repurchase" program, expecting to repurchase at least 14% of shares outstanding through this program thus far at an average price of "$176 per share".Management highlighted strong AI and product momentum, particularly with Agentforce, as "Agentforce ARR reached $1.5 billion". This growth was driven by Slack bot and Headless launches, alongside continued AI demand. In Q2 alone, customers drove "3.2 billion AW use", representing a 97% quarter-over-quarter increase in Agentic Work Units.Additionally, the company announced "Claudeforce", a combination product developed with Anthropic that brings together Anthropic's Claude model with Salesforce's data and workflows.Premium Slack upgrades have tripled since the launch of Slack bot, which is driving "8.1 million hours of annualized productivity gains" for Salesforce's own employees.CEO Marc Benioff refuted concerns over the "SaaSpocalypse", stating that net new annualized contract value (AOV) growth is "the strongest in 4 years". He noted that seats across Agentforce, sales, service, and Slack grew year-over-year, while attrition was "near its lowest level ever". The company completed a multibillion-dollar agreement contract expansion with the U.S. Army Human Resources Command, which expects to drive "up to 55 million Agentforce conversations every single month". On the organizational front, management announced that Miguel Milano was promoted to "Chief Operating Officer" during the quarter.Looking ahead, Salesforce expects third-quarter revenue to be between "$11.42 billion to $11.5 billion", representing approximately 11% to 12% growth in constant currency, with Q3 CRPO growth expected to be approximately 14% year-over-year in constant currency.For the full fiscal year 2027, the company raised its revenue guidance to "$46.1 billion to $46.4 billion", reflecting a 100 million dollar organic performance raise and a 200 million dollar expected contribution from the anticipated closings of Contentful and Fin, partially offset by a 100 million dollar FX headwind.Full-year non-GAAP operating margin guidance is held at approximately "34.3%", and GAAP operating margin is updated to approximately "20.1%", while operating and free cash flow growth is expected to be approximately "4% to 5% year-over-year".
-
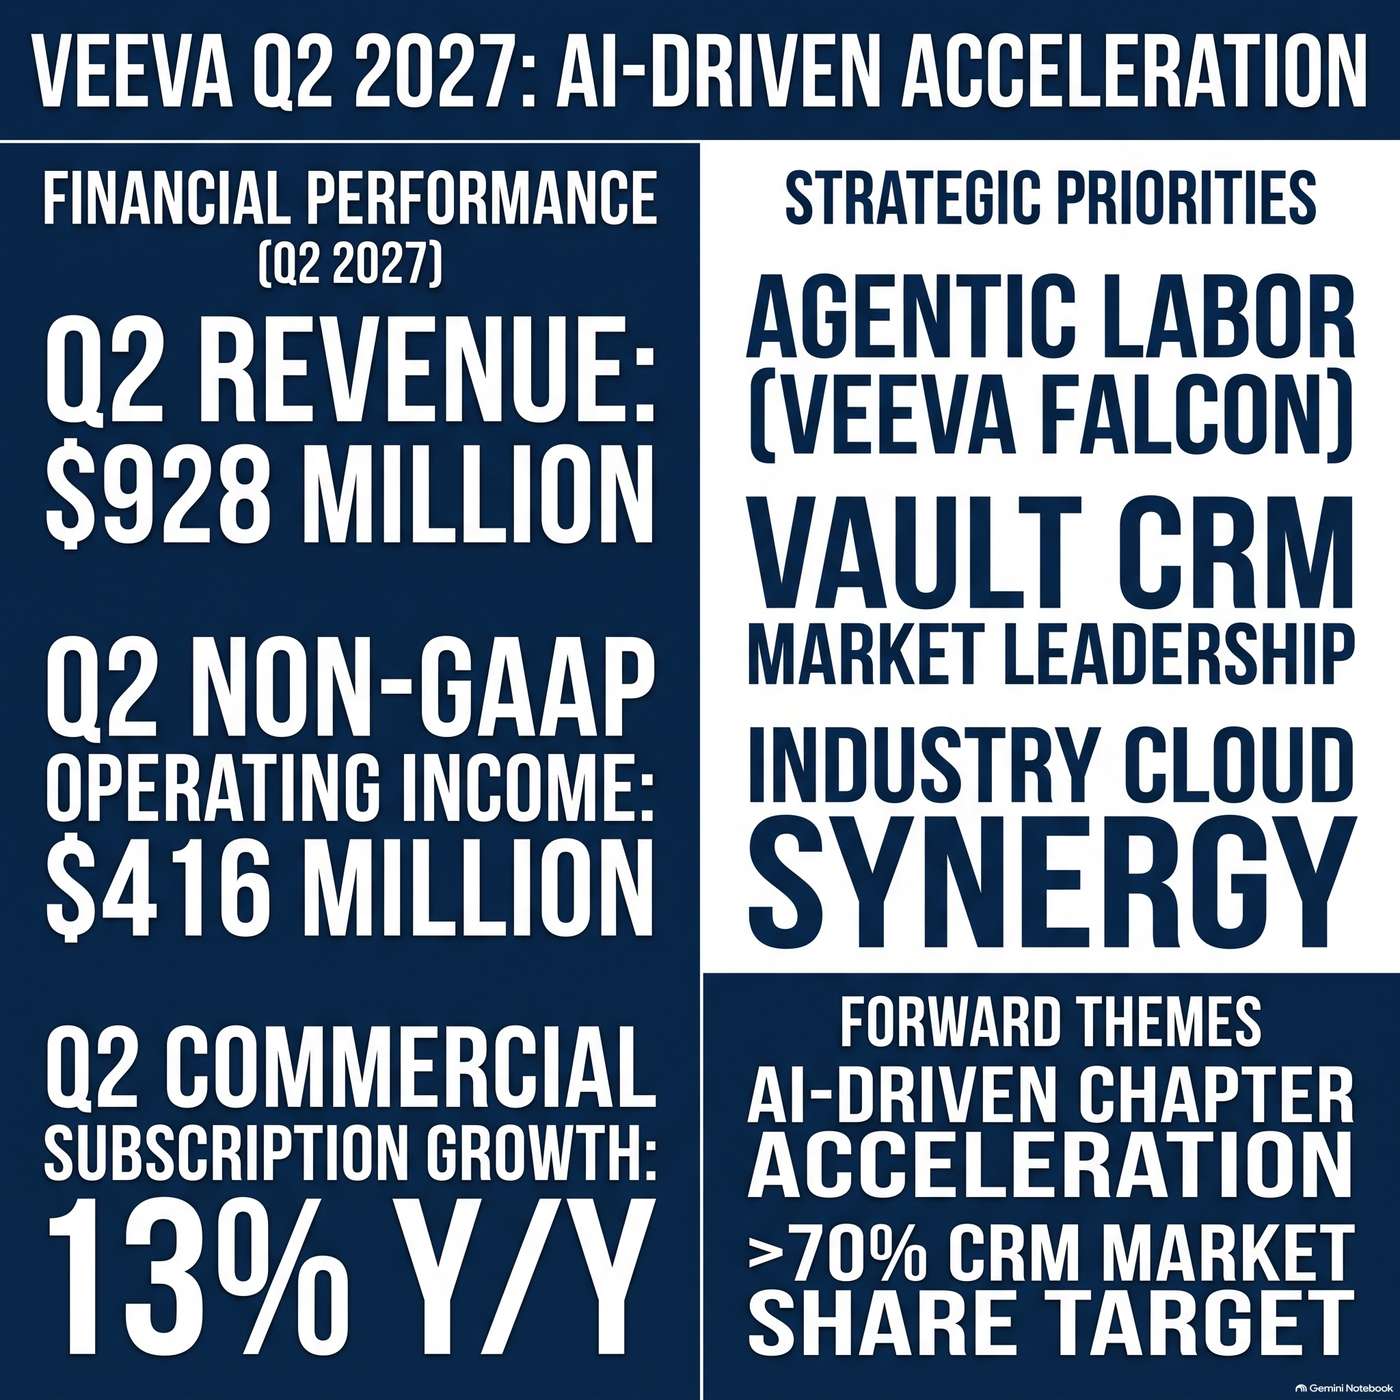 Veeva Systems Inc. (VEEV) Announced Q2 2027 Earnings on August 26, 2026, Reporting "Total revenue in the quarter was $928 million" 26.08.2026 18minVeeva Systems Inc. reported fiscal 2027 second quarter financial results, which delivered results ahead of guidance.For the quarter, management stated that "Total revenue in the quarter was $928 million, with non-GAAP operating income of $416 million." Management also highlighted that the quarter represented their best CRM quarter ever. In commercial subscriptions, revenue grew about 13 percent year-over-year, which was in the double digits even when backing out the Crossix business.During the call, management focused heavily on the rapid acceleration of their artificial intelligence initiatives, particularly with Veeva Falcon.Described as providing "agentic labor," Veeva Falcon represents a new business model that delivers digital labor rather than traditional software, with interest from customers described as very high.Management also discussed Aspen, a rapid start-up initiative within Veeva targeting horizontal CRM in a new way built on modern technology with simple, predictable pricing of 50 dollars per user per month.Additionally, Vault CRM showed strong performance with over 180 customers live, including major wins like Biogen and Regeneron, as the company prepares for CRM win backs ahead of the end of the 2029 backstop date.In other key business updates, the company highlighted the one-year anniversary of its partnership and settlement with IQVIA, with management expressing high satisfaction with the collaboration's progress. In R&D, management noted a "changing of the guard" as they transition from older products like eTMF and CTMS to newer growth areas like EDC and safety applications.The Data Cloud segment added 14 customers, showing steady progress.Looking ahead, management raised its fiscal 2027 full-year guidance, noting that all updated expectations have been factored into the full-year targets.Management also reiterated confidence in its long-term trajectory, remaining on track for its 2030 goals.
-
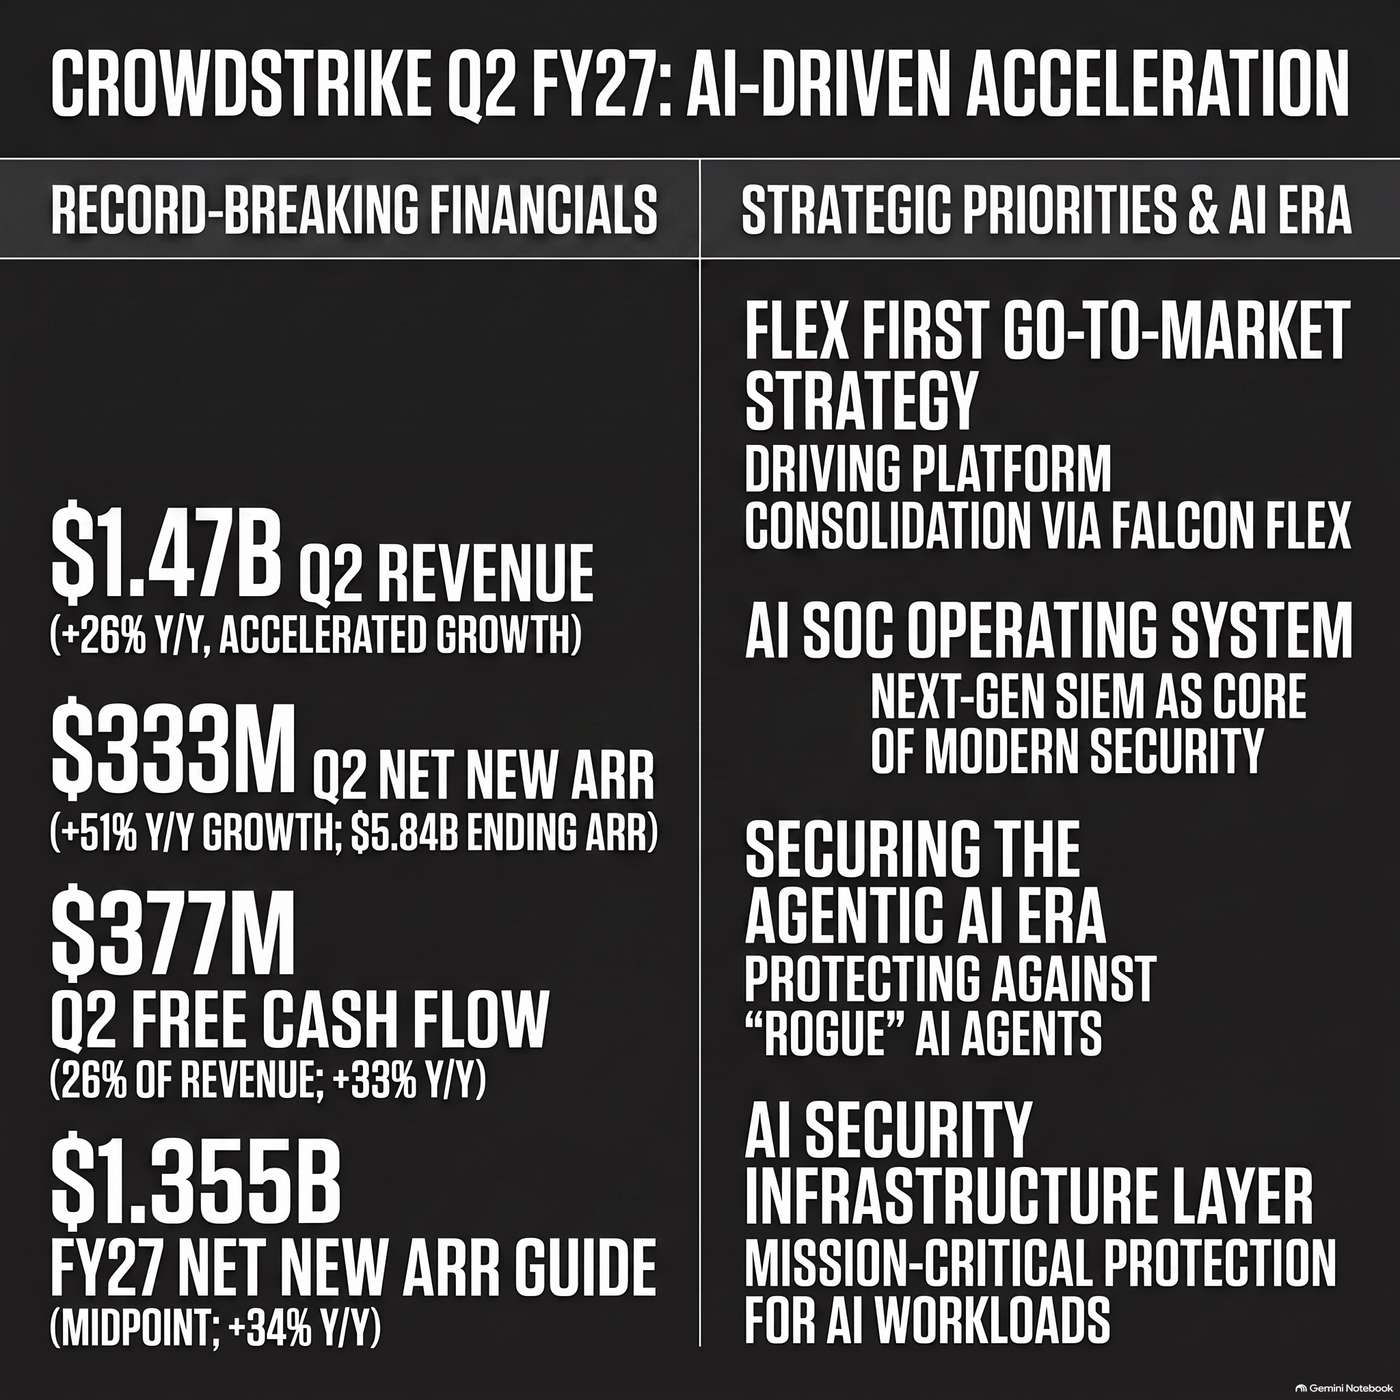 CrowdStrike Holdings, Inc. (CRWD) Announced Q2 2027 Earnings on August 26, 2026, Reporting "total revenue growth accelerated for the fifth consecutive quarter, reaching $1.47 billion, up 26% year-over-year" 26.08.2026 24minCrowdStrike Holdings, Inc. reported total revenue of $1.47 billion for the fiscal second quarter of 2027, representing 26% growth year-over-year, with second quarter subscription revenue reaching $1.40 billion, up 27% year-over-year.The company delivered a record second quarter with net new ARR of $333 million, representing 51% growth year-over-year, which brought ending ARR to $5.84 billion at the end of the quarter.Second quarter non-GAAP operating income was a record $372 million, or 25% of revenue, growing 46% year-over-year, while second quarter non-GAAP net income attributable to CrowdStrike reached a record $323 million, or $0.31 per diluted share.Additionally, GAAP net income attributable to CrowdStrike was $5 million for the second quarter, and the company generated record second quarter free cash flow of $377 million, or 26% of revenue.Management highlighted the strong momentum of their Flex First strategy, noting that ending ARR from accounts that have adopted the Falcon Flex subscription model surpassed $2.29 billion at the end of the second quarter, growing 101% year-over-year.Customers converting from standard subscriptions to Flex delivered an average ending ARR uplift of more than 40%.Chief Executive Officer George Kurtz highlighted endpoint as the epicenter for AI adoption, noting that the endpoint business accelerated for the fourth consecutive quarter. In addition, the AI detection and response offering, AIDR, grew rapidly with ending ARR nearly tripling compared to the first quarter of fiscal 2027.Next-gen SIEM ending ARR surpassed $695 million at the end of the second quarter, growing 60% year-over-year, and identity ending ARR grew 34% year-over-year to more than $585 million at the end of the second quarter.On the partnership and ecosystem front, the company's Project QuoteWerks has united more than 25 partners, collaborating on nearly $400 million of total contract value pipeline.CrowdStrike's GSI business grew nearly 50% year-over-year, and the company transacted more than $600 million in second quarter deal value through cloud marketplaces, representing over 30% year-over-year growth, including early wins on the Microsoft marketplace.Notable product updates included the upcoming sell-out Fal.Con conference in Las Vegas and the announcement of the acquisition of XM Cyber's technology assets, which is expected to close in the second half of fiscal year 2027.For the fiscal third quarter of 2027, CrowdStrike expects total revenue to be in the range of $1.523 billion to $1.529 billion, third quarter non-GAAP income from operations in the range of $373 million to $376 million, and diluted third quarter non-GAAP net income per share attributable to CrowdStrike of approximately $0.31.For the full fiscal year 2027, the company raised its net new ARR outlook to $1.355 billion at the midpoint, representing expected growth of approximately 34% year-over-year.Full year total revenue is expected to be in the range of $5.991 billion to $6.011 billion, with full year non-GAAP income from operations expected to be between $1.497 billion and $1.508 billion, and full year diluted non-GAAP net income per share in the range of $1.25 to $1.26.
-
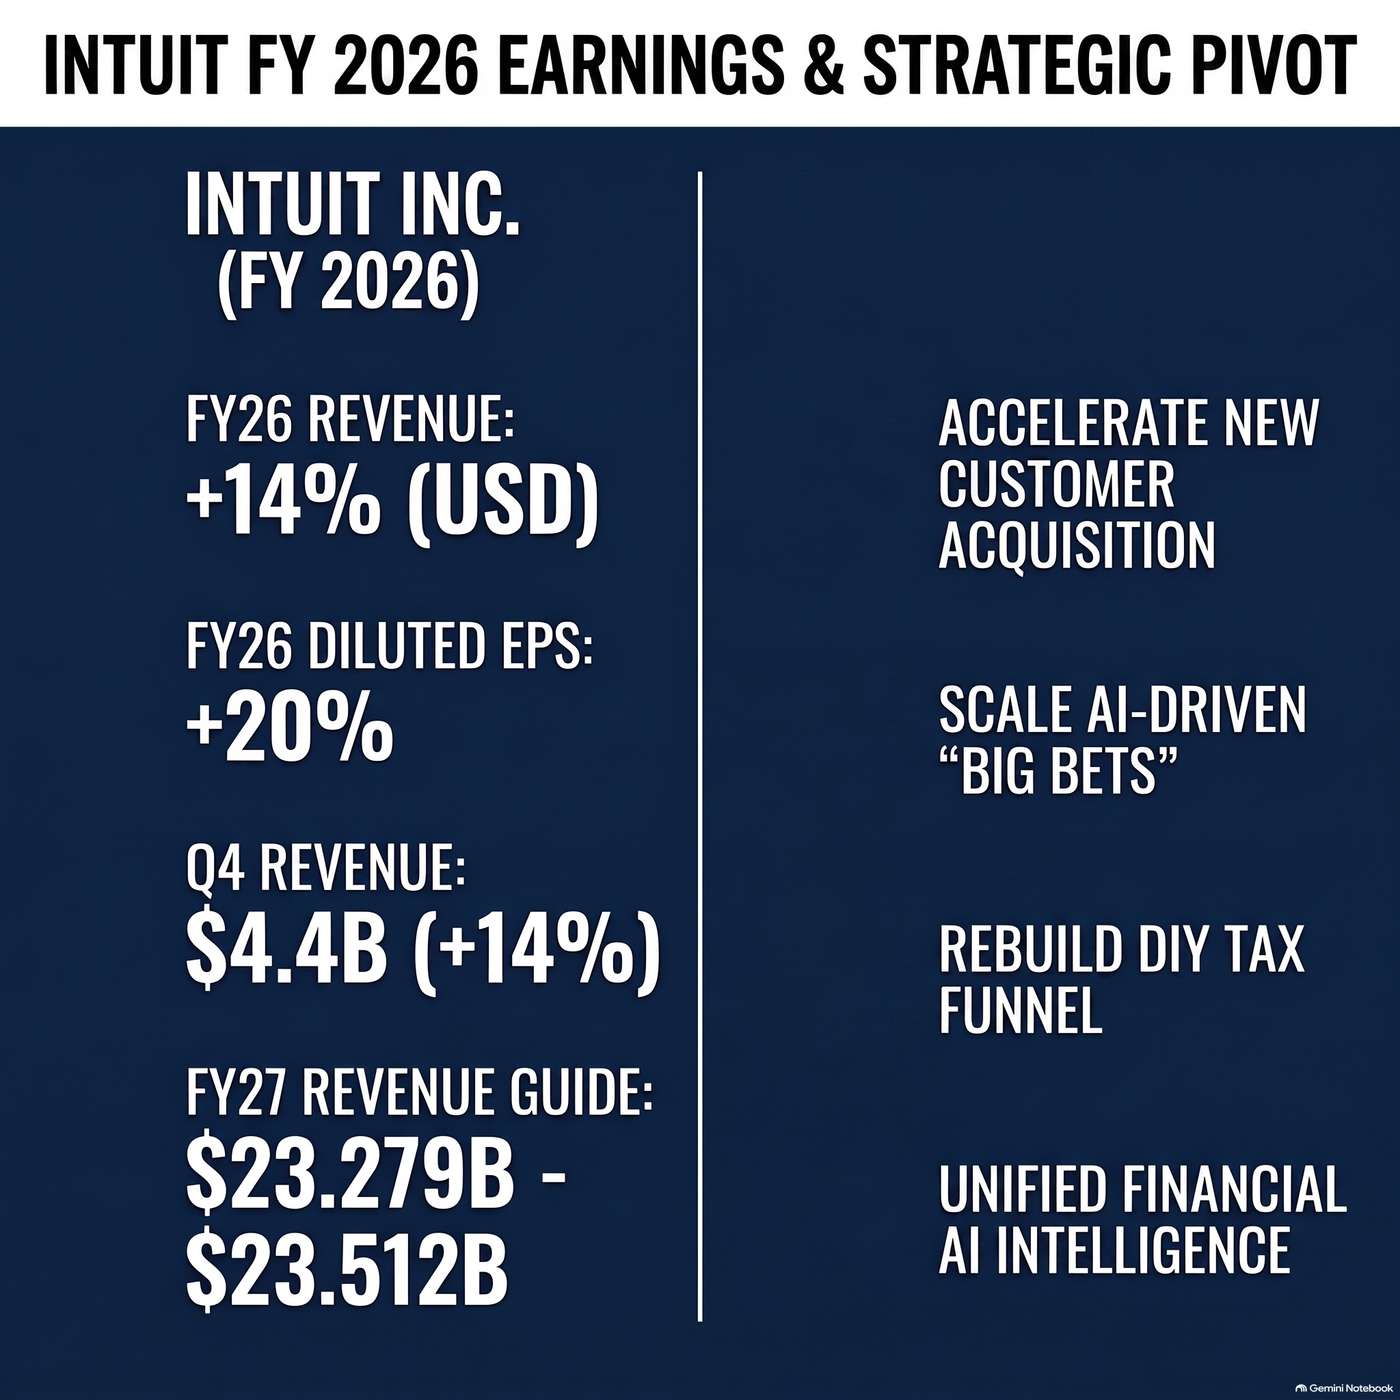 Intuit Inc. (INTU) Announced Q4 2026 Earnings on August 25, 2026, Reporting "revenue of $4.4 billion, up 14%" 25.08.2026 19minIntuit Inc. reported solid financial results for the fourth quarter and full fiscal year 2026.For the fourth quarter, total company revenue was 4.4 billion dollars, representing an increase of 14 percent year-over-year. GAAP operating income for the quarter was 475 million dollars compared to 339 million dollars in the prior year period, and non-GAAP operating income was 1.4 billion dollars, up 43 percent. GAAP diluted earnings per share was 1.34 dollars, down slightly from 1.35 dollars last year, while non-GAAP diluted earnings per share grew 47 percent to 4.03 dollars.For the full fiscal year 2026, total company revenue grew 14 percent, with both GAAP and non-GAAP diluted earnings per share expanding by 20 percent.Within its business segments, Global Business Solutions revenue grew 16 percent for the year, and Consumer segment revenue grew 11 percent, driven by a 37 percent full-year increase in TurboTax Live revenue.Credit Karma full-year revenue increased 20 percent, while Mailchimp revenue for the fourth quarter was down slightly year-over-year.In terms of strategic direction, CEO Sasan Goodarzi highlighted that while the company's big bets of assisted tax, money, and mid-market collectively grew 34 percent to represent 30 percent of total revenue, there is an urgent need to accelerate customer acquisition.Total online paying customers grew 3 percent year-over-year, which represents a deceleration. In response, Intuit is shifting its execution and investments to focus on direct new-to-the-franchise customer growth. To address the consumer tax segment, where Intuit lost quality do-it-yourself (DIY) customers to low-cost alternatives, the company is deliberately adjusting its DIY pricing strategy and accepting lower initial DIY average revenue per customer to rebuild its funnel.Operationally, Intuit is making two major reporting changes effective August 1, 2026: Mailchimp will be managed as a separate reportable segment, and share-based compensation expenses will no longer be excluded from non-GAAP financial measures.Management pointed to several product and platform milestones.Widening the front door, the recently introduced QuickBooks Free offering has already reached more than 20,000 customers who are active or have converted to paid versions.Intuit Enterprise Suite annualized revenue surpassed 145 million dollars in the fourth quarter, showing a four-fold increase from the prior year, with mid-market new-to-the-franchise customer additions growing over 30 percent.The industry-specific Construction Edition drove 19 points of growth in QuickBooks Online Advanced customer additions within the construction vertical.Additionally, Intuit launched the AI-native Intuit Accountant Suite this month, which brings together practice management, bookkeeping, and tax workflows.Looking forward, Intuit provided guidance for fiscal year 2027, expecting total company revenue to range between 23.279 billion dollars and 23.512 billion dollars, representing growth of 9 to 10 percent.Deceleration in revenue growth is primarily driven by desktop ecosystem, TurboTax, and Credit Karma.Global Business Solutions segment revenue is projected to grow 13 to 14 percent, while Consumer segment revenue growth is expected to be 4 to 6 percent, with TurboTax growing 2 to 3 percent due to lower initial DIY pricing.For the full year, GAAP diluted earnings per share is expected to be 20.12 dollars to 20.36 dollars (growth of 22 to 24 percent), and non-GAAP diluted earnings per share is expected to be 22.88 dollars to 23.12 dollars (growth of 23 to 24 percent). Over the longer term, Intuit aims to return to a double-digit revenue growth rate, with segment target three-year compound annual growth rates of 10 to 15 percent for Global Business Solutions and 4 to 8 percent for the Consumer segment.Since Mailchimp is transitioning into a separate reportable segment starting next year, I could chart its standalone revenue trends versus QuickBooks Online to highlight their relative performance scales before the formal segment separation.
-
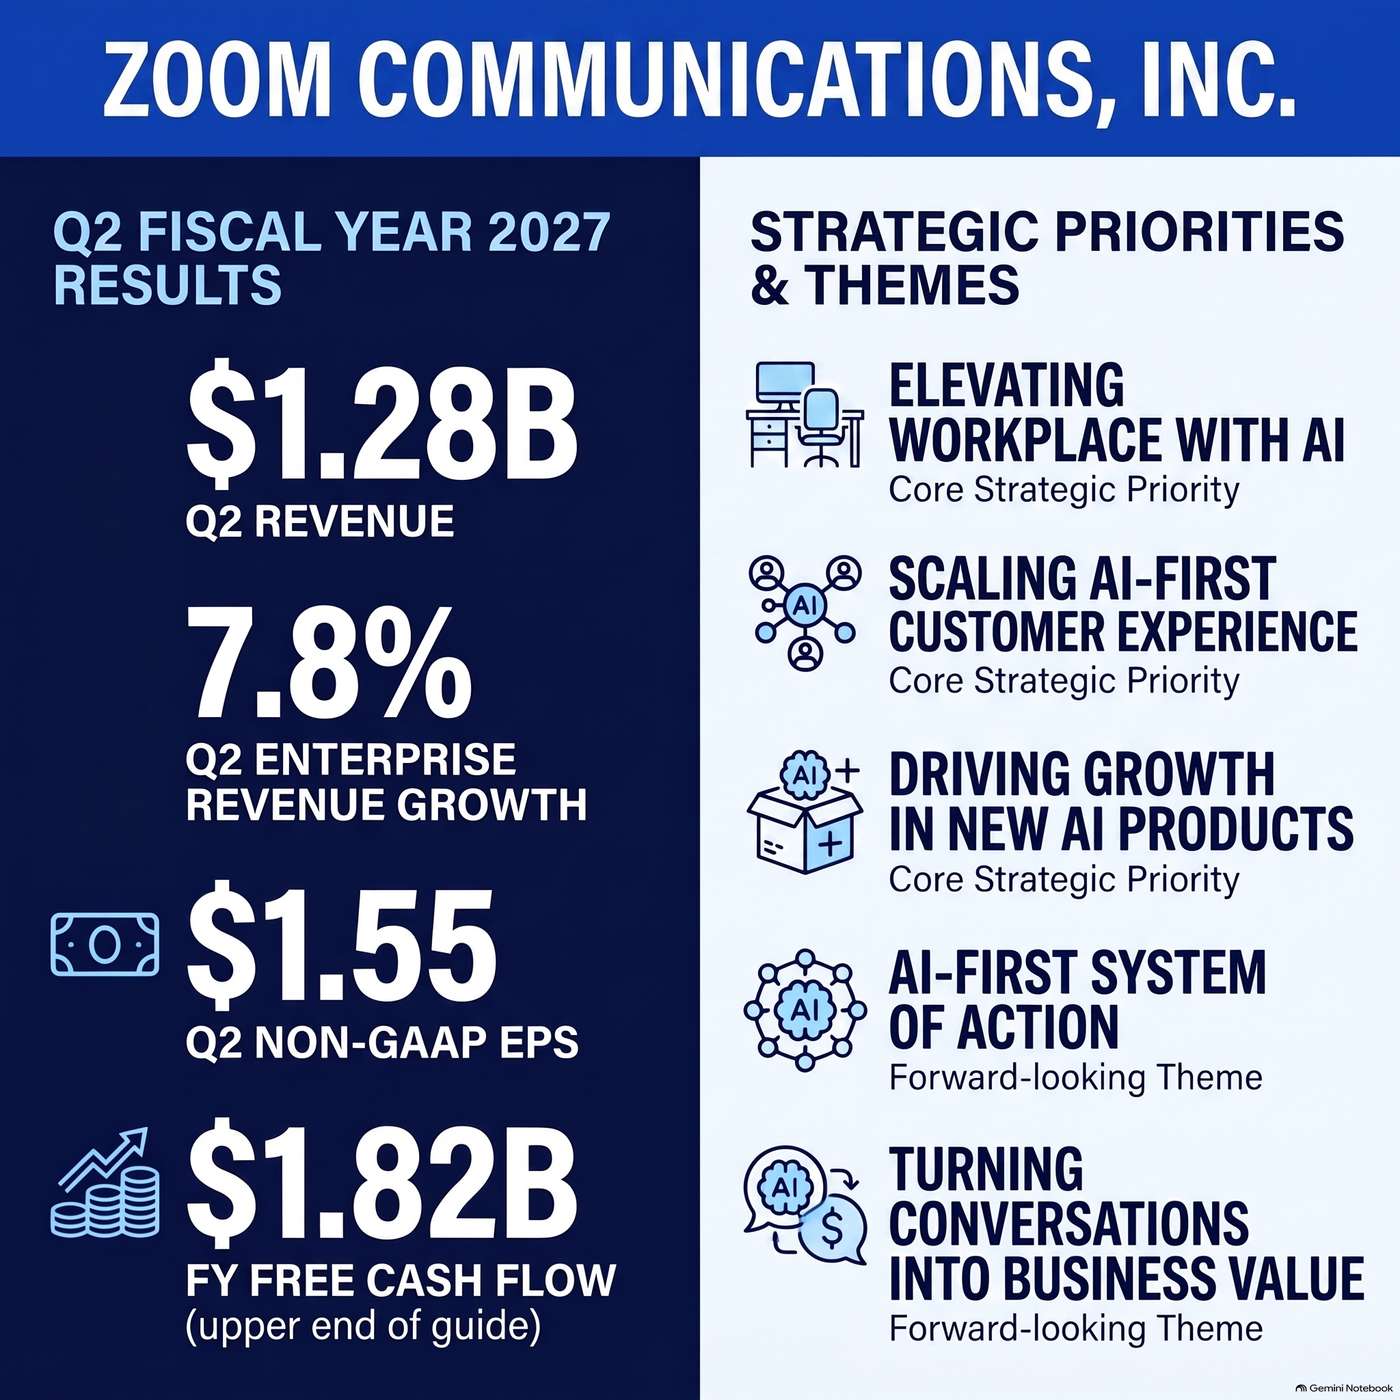 Zoom Communications, Inc. (ZM) Announced Q2 2027 Earnings on August 25, 2026, Reporting "total revenue grew 4.9% year-over-year to $1.28 billion" 25.08.2026 21minZoom Communications, Inc. reported its second quarter fiscal year 2027 financial results, noting that "total revenue grew 4.9% year-over-year to $1.28 billion" or "4.7% in constant currency." The enterprise business led this expansion with "enterprise revenue growing 7.8% year-over-year," which represented 62% of Zoom's total revenue.Non-GAAP gross margin for the quarter was 79.1%, while non-GAAP income from operations grew 1% year-over-year to $510 million, yielding a non-GAAP operating margin of 40%.Non-GAAP diluted earnings per share for Q2 was $1.55 on approximately 300 million diluted shares.Zoom generated Q2 operating cash flow of $495 million and free cash flow of $472 million, ending the period with $7.2 billion in cash, cash equivalents, and marketable securities.The company also repurchased 3.7 million shares in Q2 for approximately $352 million.Founder and CEO Eric Yuan highlighted that the "enterprise acceleration was driven by our focused execution against our 3 priorities of elevating workplace with AI, scaling AI first customer experience and driving growth in new AI products." In Workplace, licensed monthly active users of AI features grew 125% year-over-year. In customer experience, "Zoom CX ARR continued to grow at a high double-digit year-over-year rate" and marked "a record for the number of 7-figure ARR deals," with paid AI included in nine of the top ten Zoom CX deals.Zoom Virtual Agent customer count grew more than 250% year-over-year, and Zoom Phone annual recurring revenue continued to grow in the teens.Workvivo also reached a significant milestone, surpassing $100 million in ARR.Product developments featured the June release of Zoom Mate, which brings "productivity tools, agentic search and agentic workflows" to users.Zoom also expanded its sales orchestration offering with the mid-July acquisition of Common Room, which was noted as "Zoom's largest acquisition to date," adding buyer intelligence alongside Zoom Revenue Accelerator, which grew its paid customer count by 41% year-over-year. To optimize cash flow, Chief Financial Officer Michelle Chang explained that the company chose to "simply extend in 1 of our data centers, the useful life of the asset by 2 years," which reduced capital expenditures for the year and supported an upgraded free cash flow outlook.For the third quarter of fiscal year 2027, Zoom expects revenue in the range of $1.275 billion to $1.28 billion, non-GAAP operating income between $510 million and $515 million, and non-GAAP earnings per share of $1.46 to $1.48.For the full fiscal year 2027, the company raised its guidance, expecting total revenue in the range of $5.085 billion to $5.095 billion and non-GAAP earnings per share of $6.08 to $6.12.Full-year non-GAAP operating income is guided to be in the range of $2.065 billion to $2.075 billion, and full-year free cash flow guidance was raised to a range of $1.78 billion to $1.82 billion.
-
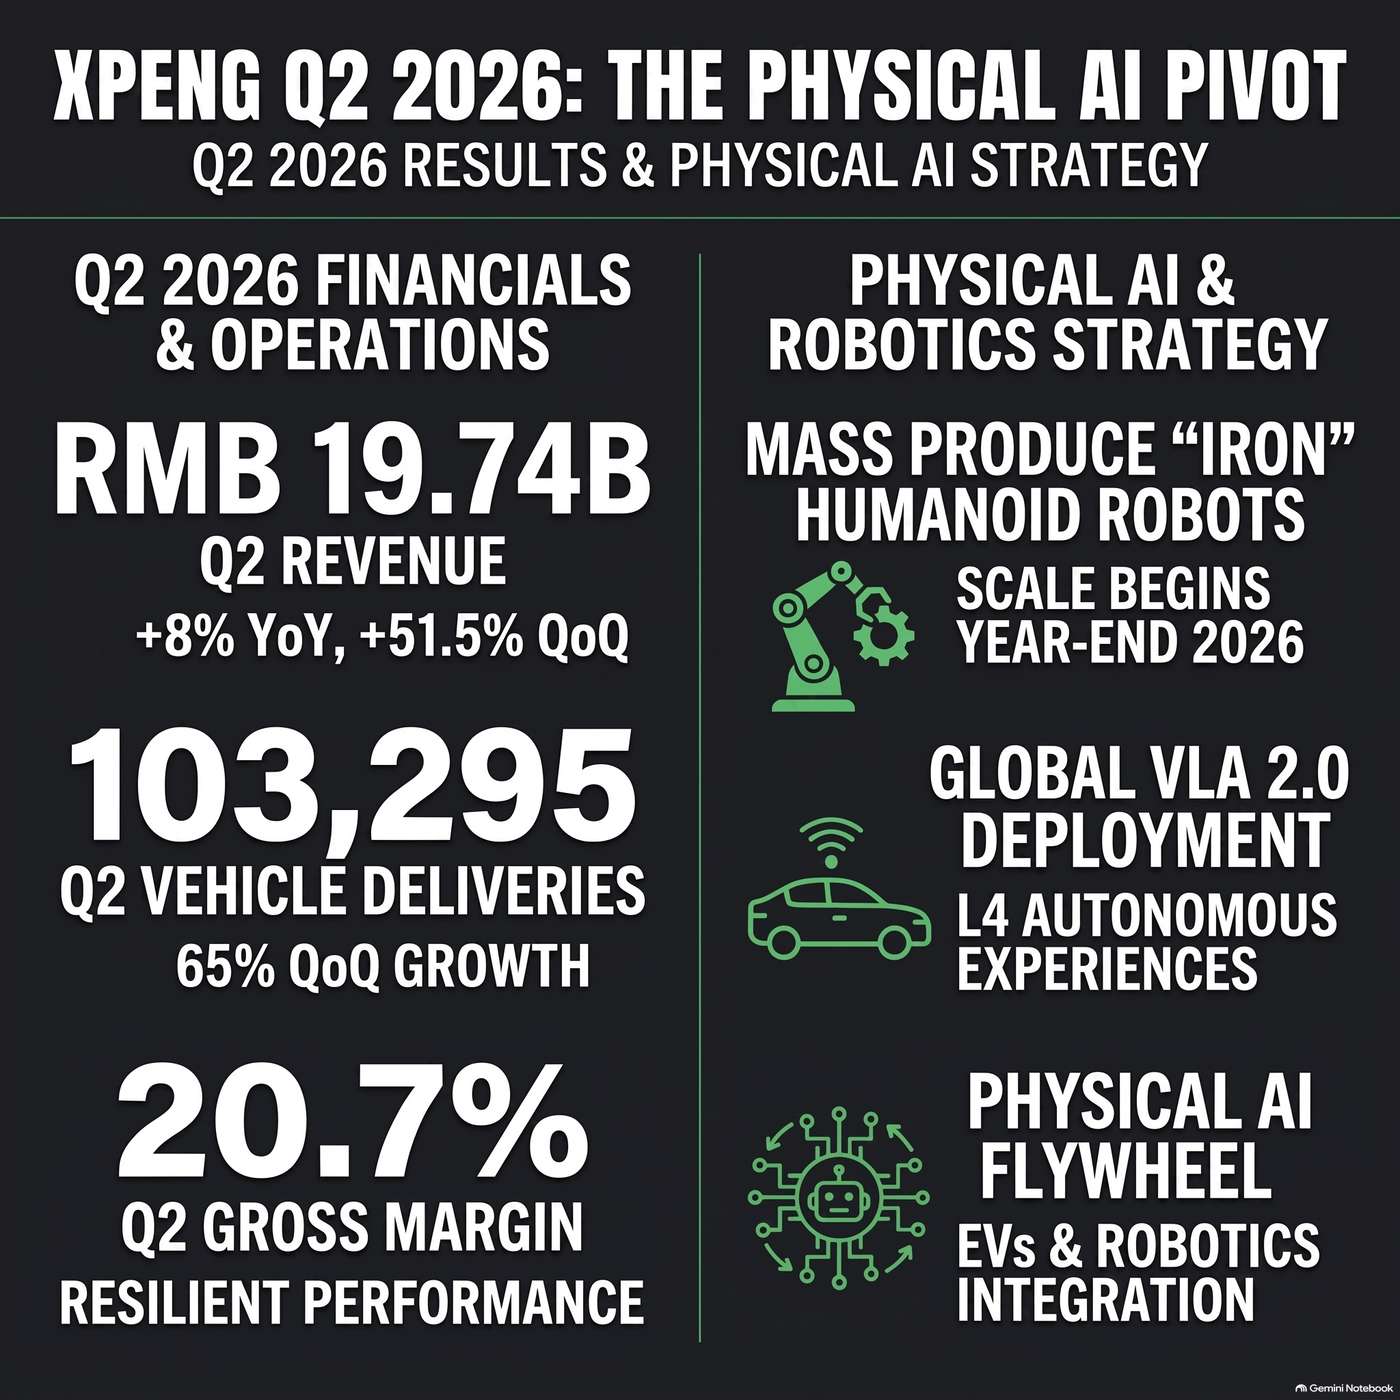 XPeng Inc. (XPEV) Announced Q2 2026 Earnings on August 24, 2026, Reporting "total revenues were RMB 19.74 billion for the second quarter of 2026". 24.08.2026 20minXPeng Inc. reported total revenues of "RMB 19.74 billion for the second quarter of 2026", which represents "an increase of 8% year-over-year and an increase of 51.5% quarter-over-quarter". Revenues from vehicle sales were "RMB 17.05 billion for the second quarter of 2026", which was "an increase of 1% year-over-year and an increase of 55% quarter-over-quarter". Revenues from services and others reached "RMB 2.7 billion for the second quarter of 2026", representing "an increase of 93.9% year-over-year and an increase of 32.6% quarter-over-quarter". The company's gross margin was 20.7% for the second quarter of 2026, while the vehicle margin was 12.1% for the second quarter of 2026.Loss of operations was "RMB 1.14 billion for the second quarter of 2026" and net loss was "RMB 1.34 billion for the second quarter of 2026". The company's cash position as of June 30, 2026, was "RMB 40.48 billion".Management highlighted a strong focus on its transformation into a "global leader in physical AI" and robotics, noting that the "technological challenges and level of innovation required for advanced general purpose of humanoid robots are far greater than those for smart EVs by at least 20 times". XPeng announced the first round of financing for its robotics business, which "raised over USD 900 million at over USD 6.2 billion post-money valuation". To leverage group synergy, Co-Founder, Chairman and CEO He Xiaopeng took on the role of CEO of the robotics business since June. On the automotive side, the company's vehicle deliveries reached 103,295 units in the second quarter, representing "up 65% quarter-over-quarter". International operations represented a major growth engine, with overseas quarterly deliveries exceeding 20,000 units for the first time in the second quarter, representing an increase of "81% year-over-year".In terms of product and technology milestones, XPeng announced plans to roll out a major upgrade to "VLA 2.0" at the end of August, featuring a "3.5x" parameter count increase in its undeviced model and a "300% improvement in perception sensitivity". The pre-installed mass-produced Robotaxi powered by VLA 2.0 has completed "more than 2,000 internal test orders in Guangzhou", with the goal of beginning passenger operations without a safety operator in the car next year.Additionally, the development of the mass-produced version of the humanoid robot, IRON, is progressing toward scale production by year-end, with "initial commercial deployments in XPeng stores and campuses". For the third quarter of 2026, XPeng expects deliveries to be "approximately 115,000 to up 121,000 units", representing "quarter-over-quarter growth of 11.3% to 17.1%". Third quarter revenue is expected to be "approximately RMB 21.7 billion to RMB 23.4 billion", representing "quarter-over-quarter growth of 9.9% to 18.5%".📊 I can map out these Q2 2026 metrics against the previous Q1 2026 and Q4 2025 results to build a visualization of XPeng's sequential financial and delivery trajectories.
-
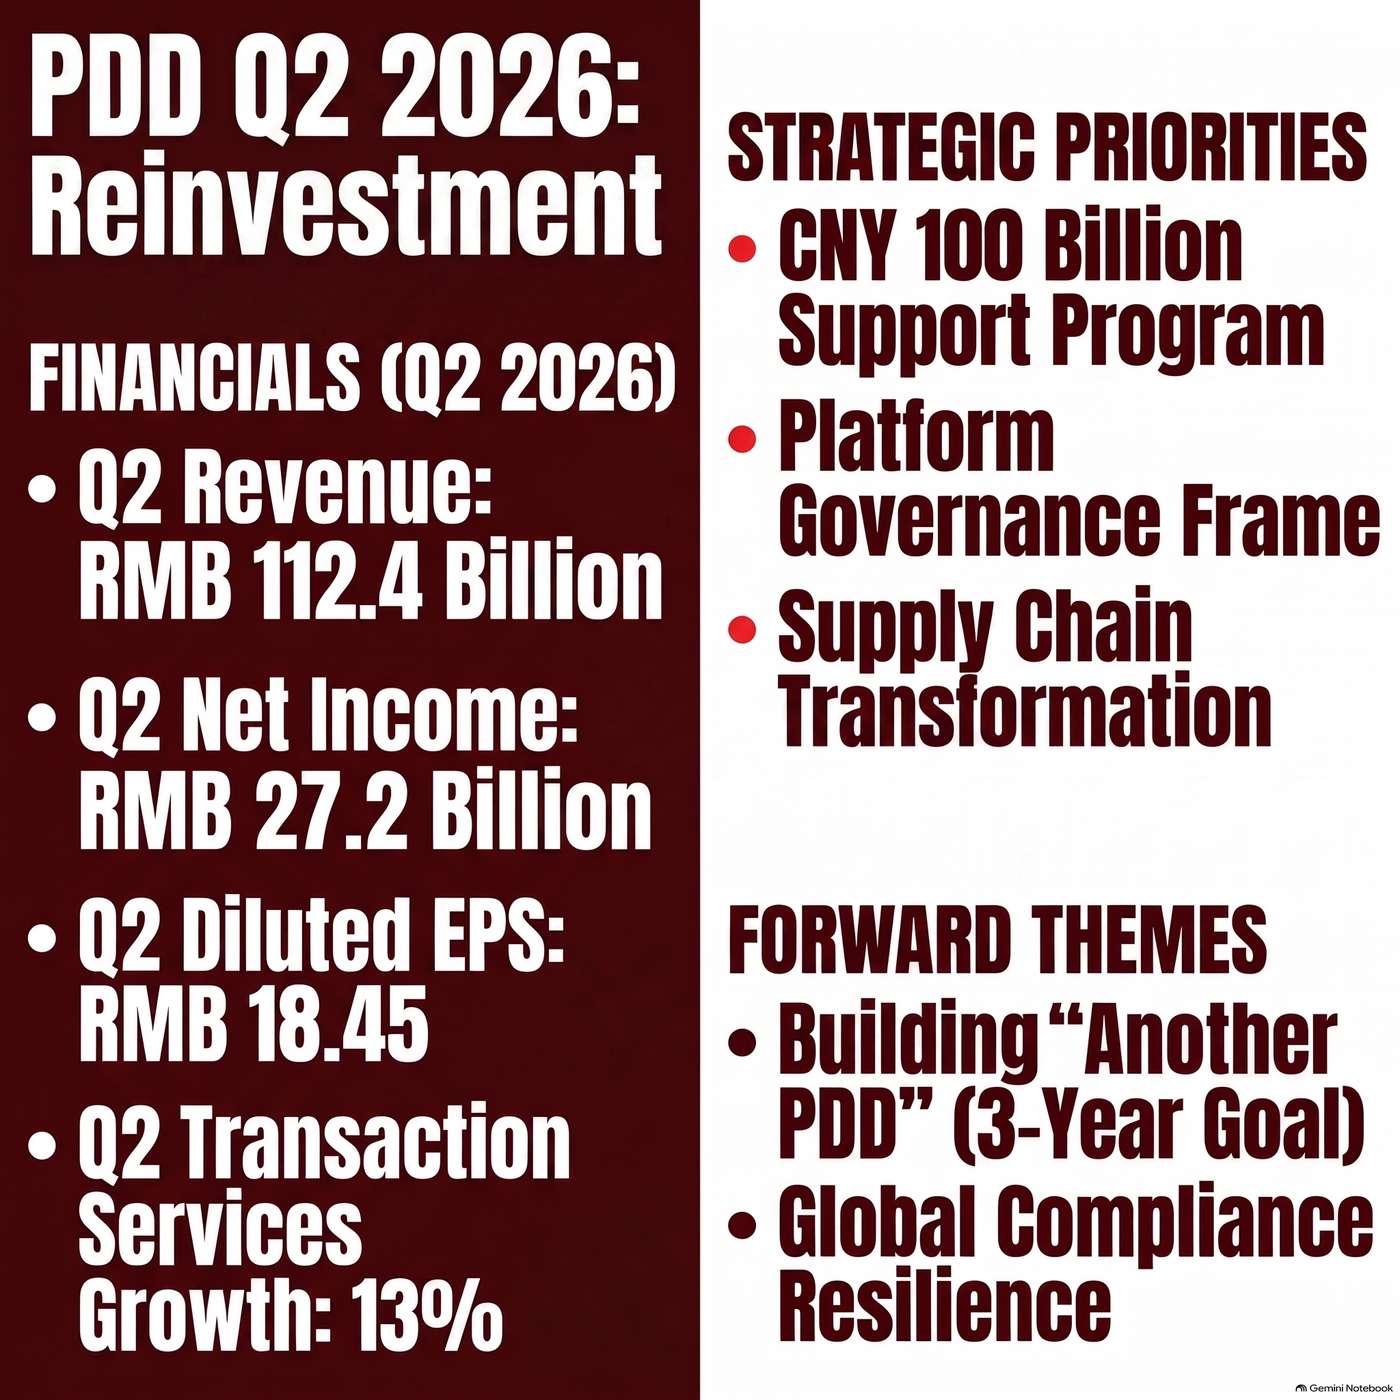 PDD Holdings Inc. (PDD) Announced Q2 2026 Earnings on August 24, 2026, Reporting "total revenues increased 8% year-over-year to RMB 112.4 billion" for the Quarter 24.08.2026 19minIn the second quarter of 2026, PDD Holdings Inc. reported that total revenues increased 8% year-over-year to RMB 112.4 billion for the quarter.This growth was mainly driven by revenues from transaction services, which were RMB 54.7 billion for the quarter, up 13% from the same quarter last year.Revenues from online marketing services and others for the quarter were RMB 57.6 billion compared with RMB 55.7 billion in the same quarter of 2025. On a GAAP basis, operating profit for the quarter was RMB 27.8 billion, representing an 8% increase year-over-year from RMB 25.8 billion in the second quarter of last year.Non-GAAP operating profit for the quarter was RMB 29.1 billion, representing a non-GAAP operating profit margin of 26% compared to 27% for the same quarter last year.Net income attributable to ordinary shareholders was RMB 27.2 billion for the quarter, compared to RMB 30.8 billion in the second quarter of last year, while non-GAAP net income attributable to ordinary shareholders for the quarter was RMB 28.5 billion. As of June 30, 2026, the company held RMB 156.4 billion in cash, cash equivalents and short-term investments.Management outlined key strategic priorities under their new decade of high-quality development, emphasizing their goal of "building another PD over the next 3 years". Under the CNY 100 billion support program, the company significantly increased spending on platform governance, expanding its trust and safety teams and launching over 150 comprehensive compliance measures by June. To support upgrading of traditional industries, PDD established a dedicated company in the new area, purchased an office building to focus on intelligent technologies, and set up a data processing service center to help manufacturers move up the value chain.Through the 2026 total premium product initiative, the platform supported agricultural regions by helping them raise cultivation standards and improve logistics, such as promoting the golden diamond variety of agricultural produce.The company's free shipping to villages program, launched six months ago, has established last-mile delivery networks across more than 10 provinces and municipalities, reducing logistics barriers in remote western regions and rural communities.Additionally, management provided an update on their first-party brand business, describing it as an important extension of supply chain capabilities, though they acknowledged that the initial rollout has taken longer than originally expected.No specific numerical forward guidance was provided during the call, though management addressed several near-term challenges and long-term outlooks.Regarding the global business, executives discussed recent regulatory shifts, such as the EU's temporary customs duty on low-value cross-border consignments introduced in July.Management noted that in the short term, cross-border orders in affected markets will experience lower fulfillment efficiency and higher costs, which will have a considerable impact on those parts of the business.However, they emphasized that short-term volatility will not alter the long-term direction of their global business, and they plan to accelerate the build-out of local warehousing and fulfillment infrastructure to increase resilience.Domestically, the company remains confident in the long-term potential of the Chinese consumer market, with plans to continue focusing on supply chain bottlenecks and merchant support to drive organic growth.📊 I can generate a set of promotional tweets for this latest quarter to help you share these results, highlighting the supply chain investments or the short-term regulatory challenges.
Samankaltaiset podcastit


Suosittu maassa
Tämä podcast esiintyy myös näiden maiden podcast-listoilla.
