
Paul Krugman Podcast
Paul Krugman
0
Paul Krugman, Nobel Prize-winning economist and New York Times columnist, shares his insights on economics, politics, and current events. The podcast covers topics such as economic policy, inequality, trade, and the global economy. Krugman offers analysis and commentary based on his expertise and research.
Jaksot
-
 Henry Farrell and Abe Newman on Weaponized Interdependence 12.09.2026 47min. . .TRANSCRIPT: Paul Krugman in Conversation with Henry Farrell and Abraham Newman(recorded 9/10/26)Paul Krugman: So, it’s a world full of choke points. Weaponized interdependence is a term I think coined by Henry Farrell and Abe Newman. Certainly I learned it from them. And there’s a big conference—not including them for some reason—taking place at the European Central Bank a few days after we record this. And so I thought I would talk again with my two favorite international relations people (although now I’m thinking of some friends who will be upset by my saying that.) But anyway, hi guys.Both: It’s great to be here.Paul Krugman: There was a seminal 2019 paper by the two of you, and then a book called Underground Empire. Anybody want to tell me what you meant by that? And let’s talk about the history, and then this weirdly more weaponized moment than anyone expected that we’re living in.Henry Farrell: Maybe I’ll take a first stab at it.So really, where this came from was that we had finished a long book looking at fights between the United States and European Union over privacy. And as part of that, one of the things we had looked at was the SWIFT system, which is a system which you use when you’re making bank transfers. It’s a messaging system that makes sure that the money gets to the right place, and that everything gets reconciled properly at the end of the day.And so Abe pointed out after we had finished this, he said, “Well, nobody’s written anything about SWIFT, and there’s something interesting and important with geopolitics going on.” And I was working with a statistical physicist who does a lot of work on networks and network dynamics, and so he thought that we could come up with something on this.And so we began to write. And we began to figure out that there was something really going on, which I think had been going on in plain sight for a number of years, but which nobody had really been able to put their finger on in such a way that they could actually sort of crystallize what the phenomenon was. And this was what we called “weaponized interdependence.” And the idea behind it was very straightforward. You know, we’ve been living for decades in a highly interdependent global economy, and the ways in which both political economy people in international relations and, I think, most economists had thought about it was in terms of the enormous efficiency advantages that flow from this. Because, if you think about interdependence in terms of trade theory, even in terms of the simple benefits of specialization that Adam Smith talked about a couple of centuries ago, the more interdependence you’re able to use, the better you’re able to achieve various outcomes collectively.But we began to think about the ways in which this relied upon all of these really boring-seeming networks, such as SWIFT, and the ways in which these networks had increasingly and quietly become a target of international coercion, especially at that stage coming from the United States.So we argued that if you had two conditions—one, a network which had some degree of centralization, so that there were some kinds of choke points in the network; and secondly, you had some great power which had a means of putting pressure on the actors that were in charge of those choke points—that you would begin to get the conditions where a weaponized interdependence could begin to happen. That is, that that great power could begin to weaponize that choke point against others.And then our argument was that this could also set a longer dynamic in train, because our fundamental sense was that this was not an equilibrium. This was not something that was sticky and was static unless the weaponizing power was extremely careful, and that the more that a power like the United States sought to weaponize choke points against its adversaries—and here the U.S. used a dollar clearing system as a means of cutting Iran and other countries out of the global banking system; it began increasingly to use other forms of technology and also semiconductor supply chains after our work began—the more that we saw a power doing that, the more that other powers were likely either to look to defend themselves or to retaliate against us. And this, we think, is a world that has come into being.Krugman: So if you were looking at SWIFT, that’s an interesting case, among other things, because the bureaucracy is formally based in Belgium. But that doesn’t really matter, right?Abraham Newman: No. I mean, with many of these things, there are Americans that sit on the corporate board, and often that’s the way that the U.S. or anybody that’s weaponizing—they look for, like, a legal channel in order to influence the operations of a company. And so first, it was just like the personnel. But at the time that they were doing this, SWIFT also—they had a data center in the United States where they mirrored all of their data, in Virginia. And so that was also just easy pickings for the Bush administration at the time, as they were trying to kind of deal with the response to 9/11.Krugman: What you were focused on very much was the U.S. trying to weaponize its control of financial and, I guess, information networks, largely against Iran, but also to some extent against China. And so this starts out as a U.S. initiative, right? So in some sense, you know, who started the fire? We did.Newman: I think it’s important, as Henry was talking about, that the source of this power is often about that: the key platforms, infrastructures of the global economy are centralized. They’re not flat. You know, we were told this vision was like “the world is flat,” but actually, you know, look at even my iPhone: it’s not flat. Those products and platforms were often American companies. And so in many domains, what the U.S. kind of realized—and in our book, Underground Empire, we kind of chart how after 9/11, different U.S. bureaucracies start to see these places in the international system where they can either exclude actors, like with SWIFT—say you can’t have access—or they use it to monitor, to surveil. We call it the Panopticon. And that’s what you see in the Snowden revelations. And so it’s both the development of markets, that markets are centralizing around U.S. companies and products, and then also that the U.S. government has this legal jurisdiction over them.Farrell: And the final thing to add to that is just that there’s also an institutional change that happens as well. And this is really connected with September 11th, 2001, because before that, you know, SWIFT manages to push back relatively successfully against U.S. efforts to try and get into its data. Mueller and other people—of course, Mueller is famous for his efforts to try and figure out what Donald Trump did, but at the time, he was in the FBI. And so he tries to get SWIFT to provide information, sort of via subpoena, and SWIFT’s response, crudely speaking, was, “We don’t do subpoenas.” And they are able to call on their friends in the U.S. Treasury, and Treasury sees part of its job at the time as being protecting the global financial system against the depredations of the United States national security state.And then suddenly, after September 11th, that is completely reversed. Treasury radically revises its understanding of its self-interest as being—instead of trying to protect the global financial system—it begins to start looking at the global financial system, thinking, “What are the ways in which we can enhance U.S. power to defend against these actors, these terrorists?” And over time, as happens in every bureaucracy, this begins to creep. It begins to expand until the U.S. is willing to go after lots and lots of different actors, including, most recently under Trump, officials in the International Criminal Court.Krugman: Okay, I want to come back to all of that. But when I read Underground Empire, the focus was, first of all, largely on U.S. actions, and largely on these kind of high-tech, you know, 21st-century choke points. As it’s turning out, there’s a lot of other kinds of choke points in the world, right? Strait of Hormuz, most obviously, but Chinese rare earths. So the potential for weaponizing interdependence seems to be a lot bigger than I think even I realized when I first read your book.Newman: I mean, one of the things that Henry and I have been talking about and warning people is that, you know, it creates an escalatory dynamic where people say, “Okay, if you’re going to weaponize these choke points, then we’re going to look for ways to do it ourselves.” And with the Chinese rare earths example, China had weaponized their rare earths back in 2010, but they had done it in what I would say is like a much more traditional trade war kind of way. It was about market access, and it was saying, you know, “If you do this, we’ll block it.” But what happens is that they learn from the way that the U.S. uses these tools to kind of create their own system of weaponization.And so what the U.S. had done is they had used export control systems in order to clamp down on Chinese access to semiconductors. And the legal system was that the U.S. has an Entity List. It’s basically a no-go. “You need licenses if you’re going to sell to these operators.” And it gives the U.S. extraterritorial power because they say, “Look, Taiwan or, you know, TSMC, if you’re going to make these chips with U.S. intellectual property, then you need permission to sell it to China.” And so the U.S. extends its ability to weaponize interdependence through basically intellectual property networks. And so physical goods, chips—this isn’t just about information or finance. It’s about physical goods. They get restricted.What China does is they then implement the same system. They create their own Entity List. They basically say, “If you use Chinese intellectual property to make your machine tools to process rare earths, you’re going to be on these lists.” And so yes, they use just market access—like, you can’t sell these batteries or these magnets—but then they also say, “If you use our processing technology to do this, we’re going to limit your access.” In the latest round of back and forth, China is really copying and then escalating these dynamics.And I think that part of it is just a norms thing. And that’s why I sometimes say, like, there’s weaponized interdependence, which is the tool; like, the choke points part; but there’s also the vibe, which is: these are now increasingly acceptable. Of course, the Strait of Hormuz was a choke point. Everybody knew that. But nobody was willing to do it because it had been seen as kind of against the norms of the economic system. And as actors like the United States and China do this, it becomes more acceptable. You know, Iran has now weaponized the Strait of Hormuz, and everybody’s like, “Oh, what do we do?” because up until this point, it was just not in the realm of what people thought you could do.Krugman: How much do you think it was that there was a norm, and how much of it was that the U.S. was just such a hegemonic power that no one else even dared to do it? I haven’t made up my own mind on that. But it’s one of those things I’ve been thinking about a lot.Farrell: So I think that our sense is that there is an enormous amount—and much more, I think, than academics who study this imagined, because we love models, and models make a lot of assumptions. So very often models assume that decision-makers have complete information about the world. And of course, anybody who knows an actual real-life decision-maker knows that this is not true.So I think one of the things that really comes through from our research in the United States, but also other people’s research elsewhere, is that people very often don’t do this because they don’t know about it, because it’s difficult to coordinate sort of different parts of the bureaucracy together to get something done unless there is some perceived terrible threat. Or because they sort of know that it’s possible, but they don’t know about what kinds of unexpected repercussions it might have, and they’re worried that it might go very badly wrong.And I think there’s a final thing here, which flows from—you had a piece on your Substack about weaponized interdependence where you’re talking about it primarily in terms of trade, and you talk a little bit about how you can threaten to use weaponized interdependence or you can actually use it. And I think a lot of the assumptions that you would have—and this is if you do think about things very rationally—is that a lot of the active use of weaponization, you would imagine, would happen off the equilibrium path; that is, that if I look at you as the United States and you’re incredibly powerful, I don’t necessarily want to weaponize against you unless I absolutely have to. And this creates an equilibrium where nobody actually sort of does the forceful stuff, but everybody behaves as if the forceful stuff is options in the background.So trying to figure out what is happening in any particular case is really hard. But if you look at, for example, rare earths, Jessica Chen Weiss and Gloria Xiong had a piece in the current issue of Foreign Affairs, which looks at this, and it suggests that this really was a really haphazard process, just the same as in the United States. In the U.S., our experience is from talking to policymakers, people are not trying to create a grand system. Instead, they are improvising in response to particular crises. They’re trying to figure out what will fix the crisis, and then they’re trying to do that, not necessarily thinking about the precedent that it will set. And China, it seems, according to Jessica and Gloria’s account, seems to be doing very much the same kind of thing.So there’s a lot of messiness, there’s a lot of improvisation. And the final thing I would say is that, if we look at the world of weaponization, as you say, there seem to be choke points everywhere. And also there are all sorts of ways in which the choke points are connected to parts of the economy where things can go very badly wrong. So you can think about this as being a complex system, and the standard way that people think about the world and complex systems is that if you do stuff, sometimes unexpected stuff happens. And the more that we see actors looking to weaponize without any very good maps of how and what they are doing or what kinds of unexpected repercussions might happen, the more we can expect not simply increased risks of tension and worry, but also people screwing up, doing dumb stuff.And here you can think about the other side of the Strait of Hormuz, is that clearly the Trump administration thought that this was going to be a super quick operation: go in and sort of bomb the hell out of Iran. The people will revolt, and glory: Donald Trump is able to pat himself on the back and go back and pour a couple of bottles of ketchup onto his well-done burgers, and eat his dinner and watch TV. And of course, this isn’t what happened.So I do think that the more that we’re in this world, the more that we find ourselves in a world where really unexpected things can happen, and where policymakers don’t have the strategic knowledge, and they also don’t have the sense of how the system works, that would really allow us to create the kinds of stability that, for example, businesses and ordinary citizens who want to live their lives without having to pay whatever ridiculous amount it is for diesel... You know, that is a world that is very far away from us right at the moment.Krugman: By the way, I’m not sure that even now everybody knows about rare earths and what they are, but these are these sort of almost trace metals that are actually weirdly critical to electronic technology these days—magnets and things. And I’m not sure that the Chinese particularly have the world’s dominant deposits, but they’ve invested, and it’s apparently really expensive and extremely environmentally destructive to process them. And so China just dominates the production of these things. And the Chinese can say, “Oh, no rare earths for you.” And that is at least as influential as the United States saying, “No banking transactions for you.” Right?Farrell: So the Trump administration discovered.Krugman: Yeah. I try not to interject myself here too much, but I do have a story for you. A very old story, which is that I was in the Reagan administration, sub-political level, Chief International Economist at the Council of Economic Advisers. Chief domestic economist was a guy—what was his name? Summers… Larry Summers. Don’t know what happened to him. But anyway, the main virtue of that for me was sitting behind the table at interagency meetings, being the guy sort of passing those slips of paper to Marty Feldstein, my principal, saying, “Don’t forget to mention that.”And there was a discussion that I remember, which was about the first of the gas pipelines from Russia to Germany. And two things were doubly relevant to this discussion. One was that the Americans were worried that the Soviet Union would be able to weaponize gas supply as a threat to the Western European economy, which was actually totally right, it turns out. But the other thing was that there was then talk of sanctions on third parties—that we were going to sanction anybody, any company that’s doing anything to help this construction. And I think it was the guy from the U.S. Trade Representative’s office that said, “We can’t do that. That’s illegal. That’s illegal under all our international agreements.” Which, of course, now we’ve learned that the fact that something is illegal under agreements doesn’t matter all that much, but it does say that there were norms that we just didn’t do that sort of thing back then, and all those are gone.So anyway, sorry, moving forward. So, what we’re seeing right now, I’m actually having my doubts because the Strait of Hormuz—obviously, that’s a choke point, more of a literal choke point than these financial ones. And it’s weaponized interdependence in a form that is much more literally weaponized than any of us had in mind. I’m not even sure how in the end, if that’s ending up being the decisive factor. I don’t know if you have any thoughts. I mean, it’s really not your field nor mine.Newman: Well, I mean, I would just say I think one of the points that Henry and I try to think about is: what’s the difference between more traditional forms of economic coercion—you know, market access restrictions or embargoes—and then the kind of things that we talk about in the book, which is these network-based types of coercion. And, you know, our argument is that the more traditional forms, which I think the Strait of Hormuz is, as a traditional kind of choke point, is that there are often then just questions of substitutes, and that increasingly actors are engaging in circumvention, they’re changing traffic patterns. There’s also the changes in the global economy and their ability to create... I mean, you’ve talked about this in your posts before about efficiency and the less dependent we really are on these systems.But when it comes to things like the U.S. dollar clearing system, because it’s a network-based platform, it’s very difficult to switch. And, you know, there are people who said that the overuse of these tools will erode these systems over time, but that’s more of a long-term game than a short-term game. And so at least at one level, I think there are ways that these kinds of approaches, once you get technical, they can help you think about the difference between, let’s say, just embargo-based kind of actions and then these kind of more weaponized interdependence actions.Krugman: Yeah. I mean, Hormuz is a good example of how weaponizing in this way can be a kind of a wasting asset, right? That more oil is finding its way around the Strait. The ships are getting better at running dark through the Strait. That’s happening a bit with the dollar as well, right? You’re probably tracking this more than I am, even though it’s in some way more up my alley. But we are seeing not a replacement of the dollar, but more bypasses out there.Newman: So that’s, I think, the key question, like everybody then asks: “Well, who’s going to create their own hub, their own network?” And sometimes that is what people are doing. But actually it’s very difficult. Like if you think about the dollar, the two alternatives are the yuan or the euro, and they’re both domestically hamstrung, for a whole bunch of reasons. So it’s very difficult for people to really put trust in the yuan or the euro basically because of politics.But that doesn’t mean that people are not doing other things that are warping the global economy. And so if you think about, whether it’s crypto on the dollar, or if you think about the shadow fleets in terms of the oil, you’re getting what Henry and I often call dark spaces—places in the global economy that are allowing for bad actors to do bad things, and that will undermine the whole point of the full faith in credit, the kinds of things we want in a solid, stable, and chaos-free global economy. And so you can have bad stuff happening even if China or the EU doesn’t replace the dollar with their own reserve currency.Krugman: The coercive ability of the U.S. also gets much eroded, even if only a few percent of world commerce is undertaken using these Chinese clearance systems or using crypto. The fact that those things are now out there and bigger than they were makes it a lot easier for somebody to adjust when, you know, the U.S. tries to cut somebody off by saying, “No, we’re gonna exclude you from all dollar-based banking transactions.” And they’re going to say, “Oh, that’s a pain, but at a 3% discount I can go through this other route.” Right?Farrell: Yeah, I think that’s right. And I think that there are two things that are happening here. One is that the indiscriminate threat, you know, the Donald Trump approach of threatening, “The world will fall on your head today, and tomorrow we will have the awesomest deal ever.” This is a terrible way of doing things. And it also speaks to what you had in your Substack this morning—we’re recording this on Thursday—the Scott Bessent “speak bigly and carry a soft stick” approach, which turns out also not to work particularly well, because, you know, the real value to the United States in this is not when you have to apply this stuff, which is pretty costly and which, as you say, involves using a rapidly obsolescing asset, because the more that you use this, the more that you encourage other actors to figure a way around it.But it is when you’re able to rely on this without actually having to threaten other actors all that much. So you see the United States, during the period when it was really at the peak of its power, what it used to do was it would go after big banks. There’s an article by these two political economy people in international relations—Early and Preble—where they called this whale hunting. So instead of going after lots of little actors, they would go after, say, HSBC or another enormous bank, and they would sort of extract billions of dollars’ worth of fines from the bank. And the idea was to terrify the rest of the banking system into submission, to get all of these other banks to actually apply internal controls, create internal bureaucracies such that they would not mess around or screw around in the future.And this is what the Biden administration also was trying to do, which you would think is the rational approach, as it was trying to do this with crypto. So you saw this in the settlement they reached with one of the big crypto exchanges, Binance, which has been involved in all sorts of rather sketchy-seeming activities. The CEO has to go to jail for a short period. And clearly they’re trying to do the same thing with crypto. They’re trying to domesticate crypto and force crypto to adopt all of these internal financial controls so that they get sucked into the system that the U.S. controls.But now we are in a world where, of course, anything goes. And I think the interesting thing about the United States is that at the moment it’s losing credibility on two fronts. First of all, by making big, enormous, empty threats, which 70 or 80% of the time it doesn’t actually deliver on. And secondly, by bringing into the heart of the system crypto, which is really sort of a set of pipelines around the traditional U.S. dollar which make it far, far more difficult to monitor who is sending money to whom.And of course, that means that if you’re trying to do what U.S. diplomats used to do, which is to go to other countries and say, “Well, you know, we all have a shared interest in making sure that we’re in control of the system, so that everybody knows where our money is going; the terrorists, drug dealers, and so on aren’t able to swap money easily”—you don’t have that credibility anymore. And this really, I think, is leaking away U.S. power in ways which are going to reverberate long after Donald Trump has departed the scene.Krugman: Yeah, I’ve been saying for a long time that I don’t think crypto has much of a real future because there are basically no legitimate uses for it. And the problem is, I think that the second part of that was right, but the first part may have been misunderestimating the extent to which illegitimate uses matter in today’s world.Farrell: Well, I should also plug, Abe and one of his colleagues, Stacie Goddard, had this article which more or less argued that we can think about this as that one of the possible ways in which the world is moving, or the Trump people would like to move it, is towards a neo-royalist system in which you more or less have clans of different actors sort of coordinating together and sharing up the proceeds. And that world is a world where crypto is definitely very, very useful for concealing the flows through which things actually happen. And so, if you really want to have nightmares, I think William Gibson’s The Peripheral—it’s a portrait of a world that looks exactly like that, where that is the sort of major organizing principle of global politics. That’s the kind of world that you might end up in if we aren’t able to push back.Krugman: One thing, just coming back to the policymakers and the extent to which they really don’t know what they’re doing—that’s the other thing I learned during my one year in the U.S. government: the extent to which—and the Reagan administration was a collection of philosopher kings compared with the current management, but still—the extent to which people just didn’t know what they were doing. And one thing that strikes me right now is that particularly the Trump administration, their notion is that what’s important is being able to sell into a market, as opposed to being able to get stuff. Are you still seeing that out there?Newman: I mean, let me say, this world that we’re talking about, the world of weaponized interdependence, is in many ways very uncomfortable for a lot of policymakers. And that’s kind of where Henry started with: you know, Treasury was not built originally to manipulate markets in order to target coercion. So first, there’s just the level-setting of that: the bureaucracies were not structured for this purpose.Then you start to add objectives. So if you think about, like, traditional trade wars, it’s often about trying to rebalance trade flows. But here we’re thinking about objectives: they start with counterterrorism, then we go to nonproliferation, then it’s about sovereign encroachment with Russia, all of a sudden it’s about technology restrictions on China. And now you get, you know, “Colombia, if you don’t take our deportees, we’re going to put sanctions on you.” So the objectives that these policies are trying to obtain are shifting.And then the third part is, this is really fine-grained manipulation of market relations. And so in the book we talk about this: there’s a sanction that was put on Russia to kind of cripple one of the oligarchs, Oleg Deripaska. He has an aluminum empire. And when the U.S. sanctions them, it basically threatens this factory in Ireland. (And now, a disclosure: Henry’s Irish. But that’s not how we came across this one. You know, we don’t have any stocks or shares in that aluminum factory.) But this factory is like the only place in Europe that makes a very fine-grained aluminum that is used in German car production. So there are these ripple effects through the market because markets are very complex. And the Obama administration—they had to roll back these sanctions because it was having these unanticipated consequences.What I think is as dangerous as all the things we’ve talked about is just the undermining of the bureaucratic state. You know, the whole DOGE process, the idea that we should take apart these bureaucracies that understand the markets at the same time that we’re basically unleashing a whole new arsenal of weapons on the world. I think Henry came up with this phrase: it’s like taking apart the engine while you’re flying at 30,000 feet. You know, it’s like we need a very sophisticated set of tools in order to do, basically, economic war, and instead we’re taking the whole thing apart as we’re flying. And so I think both of us are very worried that it’s not just new problems addressed by new agencies that aren’t used to it; we’re also taking away their expertise.Krugman: Yeah. One of the things about the Tom Friedman world, the world of extreme interdependence, is that there’s just so many interdependencies you don’t realize are there, and that a DOGE-ified federal government is not going to know are there. I mean, we just saw Trump say, “No more Bombardier jets from Canada,” apparently completely unaware that a large part of Bombardier’s operations are in Kansas.Newman: We’re not in Kansas anymore.Krugman: The other thing that’s been striking me, and I think you’re getting at this a lot, is that there are so many choke points out there that in this world of extreme cross-border flows, the extent to which even what might seem to be minor players turn out to have choke points, to control particular things. I don’t know how much you’re looking at the absurd Canada stuff.Farrell: Yeah.Krugman: And what strikes me there is just, you know, Canada has a tiny economy. It’s polar bears and Mounties. How much can Canada matter to the United States? And then once you start to look, you see there are all of these things that actually, for the moment, are only made in Canada, and we don’t have domestic alternatives.Farrell: So I think that there are two ways in which you can look at this. And one of the ways, I think, unfortunately, is the way which is prevailing. In a certain sense, a world of interdependence, crudely speaking, is almost necessarily going to be a world of choke points, because if you combine interdependence with the ordinary kinds of things that you, for example, wrote about—40 years ago was it? Geography and Trade?Krugman: Yeah.Farrell: The ways in which things cluster together in one of these—Krugman: But that was only 35 years ago.Farrell: Okay. Yeah, yeah. But that’s kind of naturally the way that production happens. And it’s also the way that a lot of other nonphysical networks happen as well, because you want to build a monopoly, because you want to make things just more efficient or whatever—networks tend to become choke points.And so then I think the result is that we’ve moved from a kind of Thomas Friedman “the world is flat,” “everything is awesome” kind of view in which we completely cut out all of the geopolitics—we think politics is irrelevant because nobody would go to war against another country if they also have McDonald’s, and all of these theories—into a world where, I think, pretty well the opposite is happening. So we have these sort of policymakers now, squirrely-eyed, looking at the world, looking at every sort of possible external dependency as if it’s a massive threat.Abe and I have a piece with Yeling Tan coming out in Foreign Affairs, so I don’t want to talk too much more about this, but this is its own sort of illusion, its own set of problems. And so I think really where we need to get to is to figure out ways to actually sort of accept a certain amount of risk, a certain amount of geopolitical difficulty, a certain amount of messiness, build forms of redundancy which minimize those risks without necessarily getting away from them completely—because you can’t get away from them completely—and try and build a form of globalization which is more robust than the form of globalization that we have at the moment.But getting there from where we are at the moment, especially given the politics, not just in the U.S., but also in China, also in Russia—less so in Europe, but Europe has its own pathologies—it’s really hard to see how to get there.Krugman: Yeah. I mean, I have seen the paper, and I guess I should not step on it too much either. But I’ve seen your draft, and I think this is more my phrase than yours, but “choke points arms race,” where everybody starts basically investing in duplicative capacity, has industrial policies, maybe tariffs, to make sure that you have domestic capacity in all kinds of things, which can be highly inefficient. That’s part of what you’re talking about, right?Newman: Yes. And maybe I’ll go back to the conclusion of Underground Empire, where we talked about some of these same things. It’s easy to focus on the weapons. You know, that’s what happened when nuclear weapons were first getting invented: it’s like, “Oh, look, this is amazing. We can blow up huge things.” And then everybody’s like, “Well, then I need to have the weapons.” But what you really then quickly come to learn is that it’s about a strategy. It’s not about the weapon. It’s about trying to figure out: how does this fit into a broader set of objectives?And right now, just very simple things like risk assessments—Yes, there are a lot of choke points. Everybody’s looking for the choke points. But actually there’s a lot of things in the global economy that aren’t choke points. There’s a great piece by Guillaume Beaumier where he basically says, “Look, in the semiconductor supply chain, there’s multiple choke points, there’s multiple networks. It’s not like there’s just one set of these networks.” And actors control different pieces. So ASML, the Dutch company that makes the lithography, the etching systems—they sit in the Netherlands, whereas the software part is in the United States, and of course the production is in Taiwan. So who has the advantage? And that’s where really policymakers in our world focus less on these choke points and more on how do you manage a world where there are these interdependencies?And the first cut should be to say, “Here’s all the places where there’s not a risk. Here’s the places where we should be, you know, less worried.” And that simple risk assessment system hasn’t happened. Henry and I have been talking with people at the European Commission, and they’ve threatened to make this risk assessment for about five years, and it’s still not out. So, creating the norms, creating just basic structures—how do we identify what are the risks of having these choke points in place? I think it’s an easy first step.The other thing that I think is really important to emphasize is the danger if we don’t. If we look at the kind of choke point arms race, these things aren’t just economic. These are increasingly being intertwined with kinetic wars. And you see that very clearly in Russia and Ukraine. There’s a ground war happening, but at the same time, different types of economic levers are being used, whether it’s the price cap or it’s the sanctions regime. And what I get very worried about is when you have the U.S. negotiating, like, “Give us a big deal with Europe on a trade level,” and all of a sudden, the flip side is, “If you don’t, we’re going to cut you off from the arms that you need to do your war in Ukraine.” And up until about five years ago, these were very separate, or people were thinking of them as alternatives. It’s like, you can weaponize interdependence or you can do these military kinds of things. But increasingly what we’re seeing is that the carrots and sticks are being combined in, I think, increasingly dangerous ways.Krugman: Yeah. One of the things that worries me a little bit on all of this is how much, at least as I understand it, the drones are very heavily Chinese components. So the two sides are basically blowing each other up with lots of Chinese inputs. We kind of know who China supports, but in a limited way in this war. But they haven’t really applied that kind of leverage.Farrell: There are just risks everywhere. Nick Mulder has this fantastic book which came out maybe four or five years ago called The Economic Weapon. He is a historian who worked with Adam Tooze. And so his argument is that we used not to distinguish between economic war and actual war nearly as much as we do right now, that this was a somewhat artificial set of sort of legal changes which happened after World War I, and that the risk of slipping from the one to the other, or having the two intersect with each other, is much greater than you might think.Equally, I think Abe is right: we want to focus on the ways in which you can build forward, rather than just being sort of paralyzed by the multitude of different threats. And one thing I’m really interested to see here is what is happening between Canada and the European Union. It’s clear that they are building something together. We’re going to hear some announcement in the next few weeks. You can wishcast enormous amounts onto these kinds of decisions; they’re always much more disappointing in practice than the hopes that you attach to them. But I think that this is the first moment where we are seeing a really concerted effort by, you know, one major-ish country plus Europe—which is not a country; it is a power, nonetheless, economically—to try and put something together which can provide some kind of a neutral system for building up.In the worst-case scenario, this will just turn out to be a series of vaguely worded platitudes which will turn into nothing. But you could also see ways in which, for example, people in the European Union who are trying to escape their trap—which is that the member states dominate national security, so that it’s impossible to get agreement on important things—you could see ways in which some of the people who want to try and escape that trap could try to start using broader, sort of minilateral-type arrangements like this as a way to try and build something, and build some sort of more secure and robust means of coordination which actually might turn into something in the longer term. And who knows? Perhaps a future U.S. administration might actually be willing to enter into these things. You know, pigs could fly. It could happen.Krugman: Well, I mean, for all of the exasperating things about the EU, Europe did succeed in creating both essentially a demilitarized continent, and the economic weapon has also basically been largely defanged in Europe. You don’t see the Germans having a dispute with the French and threatening to cut off their supply of, of whatever, diesel motors or something like that. So, I guess these things can happen.Newman: Well, I think they definitely have defanged it internally. But a lot of times Europeans are like, “Oh, this is just China and the United States. China and the United States are messing everything up, and they’re weaponizing interdependence. And we’re these nice guys, and we’re about peace and trade and whatever.” But if you look at the Russia sanctions, how did that actually happen? Who froze the Russian central bank assets? You know, the 300 billion Euros—it’s mostly the Europeans. And so if you’re in Beijing and you watch that happen, you’re pretty clear that Europe has the power and capacity to be quite interventionist in the economic world.And so I just think we should always remember that Europe has a lot of tricks up its sleeve as well, and is an incredibly powerful economy. Their problem in some ways is, in U.S.-European relations, they’re so dependent on U.S. security guarantees, it’s difficult for them to push back when Trump makes the ask, because they need our weapons right now.Krugman: Okay. I actually have a beef with some of the research papers that I’ve been reading. There’s quite a lot of discussion of potential weaponization of economic relations between China and the United States, and some about possible Chinese weaponization against Europe. But no one ever seems to talk about what the Europeans could do. And yet the European Union is a huge economy with a lot of technology. There must be stuff.Farrell: There is. And part of the problem, again, it’s institutional. So, as we say, when the United States really got its act together on this was when the different parts of the U.S. began to coordinate towards a common set of objectives, a common understanding of the strategic situation. Europe has not gotten there yet, and it is really hard.And the fundamental, basic flaw that Europe has: it was exquisitely well adapted to deal with the Thomas Friedman world—that is, to deal with a world in which everything is about sort of markets and trade. And the European Union builds up its own form of power: it’s very, very good at using regulations to shape its internal market and then looking to impose those standards on the rest of the world. But we’re now in a world where markets and security are entangled. And that is a world that is absolutely godawful for the EU to deal with, because its market capacities are at the level of the EU, and so too its trade negotiating capacities. But the national security stuff is all at the level of the member states.And this more or less forms a chaos for difficulty in coordinating for lots and lots of different member states with their particular national interests, each of which to squabble and to fight and to say, “No, we don’t want to do this because we are urgently dependent on China in X, or we depend completely on the United States in Y.” And so as a result, the European Union has had and will continue to have enormous difficulty in actually coordinating. Again, because the national security stuff happens at the level of the individual states, and the economic stuff happens at the level of the European Union. So all of these are problems which straddle the relationship between the two, and are inherently difficult for the EU to deal with.The U.S. has very often been able to quietly bang heads together and get consensus in the past, but at this moment the U.S. is instead specifically seeking to divide the EU because it doesn’t like the EU, because it views the EU as a threat to, bluntly speaking, “Western civilization”—however the Department of State is defining that today: white folks, fundamentally, and sort of the awesome things that white folks have created. You know, it becomes really hard for the EU to push back against us because it has internal divisions and it has an external protector which is doing everything it possibly can to fan the flames.And then China also is extremely good at playing the game of, “Well, you want this investment, then do X. But if you take some sort of actions against a Chinese company, we are going to visit hellfire upon your economy in this or that way.”So, I think you’re absolutely right. Paul. The EU is a phenomenal achievement. I think both Abe and I—or at least I am—cautiously bullish that over the longer term, the EU will get its act together. But we all know what Keynes said about the longer term.Krugman: Maybe that’s where we end. In the long run, you guys will help save the world with your book and your work. Thanks for talking today. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Where’s the Beef (Coming From)? 08.09.2026 11minTranscript“Mary had a little lamb, but when she saw it sicken, she sent it off to Packingtown, and now it’s labeled chicken.” Hi, Paul Krugman here. That’s a little ditty that was circulating, I can’t find any original source, around 1905, when Upton Sinclair published “The Jungle” — about the meatpacking industry, one of the sort of founding documents of the progressive movement. The topic today is Donald Trump and beef, because here we are back in Upton Sinclair territory. So you may have seen that last month Trump announced, given that we have high beef prices, that he was going to allow the tariff-free import of 300,000 tons of ground beef.Rather oddly, he didn’t say from where and wouldn’t say from where for a while. And then eventually said, well, from Argentina, Brazil, and other places.There has been a substantial uproar over these imports of ground beef because of concerns about safety. You know, if he won’t even say where it’s coming from or whether the countries involved are going to be practicing food safety, that is kind of an issue. And it turns out it’s not just, you know, not just woke liberal types but ranchers, lawmakers and food safety experts who were very concerned about the plan and were not reassured when Trump said the meat is “very clean and very good.”Okay, little by little details are coming out about how all of this happened. It turns out that the initial plan to allow the beef imports was announced the day after a closed door meeting between Trump and a Brazilian meat packing billionaire who is a major donor to Trump.And they went right ahead and announced the plan, although again without details. There doesn’t seem to have been much discussion of how this would work, of the concerns. After some initial blowback — even ranchers are concerned that people might become worried about the safety of U.S. beef — Trump announced that he was going to also allow farmers and ranchers to process their own beef rather than having to go through the regular meatpacking companies. But it turned out that the ranchers hate that too, because what they want is for people to believe that beef is safe. They want to be assured that there are quality standards being upheld.And now that we have at least some information about the origins of the beef, we are even less reassured. In fact, just the other day, the European Union banned beef imports from Brazil because Brazil was not adhering to EU standards on the use of antibiotics. So there are, in fact, real concerns here about safety.Okay, this is quite a story, and beef is not that trivial a product, but there’s a lot of secondary implications here. The first is that this is a very Trumpian story. It’s got this sort of characteristic combination of raw corruption and raw incompetence. Raw might not have been the best word to use here, but anyway. The corruption: Obviously, this was a decision made because somebody who has given Trump’s campaign and possibly Trump himself money had a meeting with him and got an immediate policy change. So this certainly looks like undue influence. We don’t know exactly how it happened because it was a closed-door meeting.Also, shouldn’t somebody have been in the room to or at least passed on this before it was announced to say, you know, is this a good idea? Shouldn’t there have been somebody from the Agriculture Department, somebody from the U.S. Trade Representative’s Office, but certainly someone from food safety to pass judgment or give some warning?In a normal administration, any kind of decision like this involves a process in which multiple agencies get a chance to weigh in and in which somebody who knows something gets to say, look, there are real problems with this idea. But obviously that didn’t happen here. And basically it doesn’t happen in this administration.This is an administration that does not like experts. Does not listen to expertise. That’s not just a result of particular personnel decisions that Trump made. That is just a defining characteristic. At a fundamental level, they’re just hostile to the idea of expertise in any domain, in pretty much every agency where there’s something to know, where there’s technical stuff that you need to know to make good decisions.The people who actually know things, or the people who are willing to speak up about what they know, have been silenced, purged. That’s across the board. Basically, it’s Hegseths all the way down in this administration.And so in this case, nobody was there apparently to say, this is really not a very good idea. And I think it’s really striking that even Trump thought, well, okay, I can fix this. At least I can mend fences with the ranchers by giving them more leeway to be unregulated themselves. But it turns out that the ranchers want regulation. They want customers to know that the beef that they buy is safe. So just raw incompetence on top of the raw corruption. There’s an even larger issue here. Normally, when we think about, or as we used to think about, left versus right, there is a question about the role of government. How big a role should government play? And ultimately, it’s a values question, normally. It is a question, should it be the government’s business to ensure that citizens are not in dire poverty? Should it be the government’s business to ensure that everyone has access to essential healthcare?And the question of how far in that direction you want to go is the traditional left-right distinction. Obviously, I’m on one side of that, and I think that morally I’m right. I think even in practical terms I’m right, but that is a debatable point. But there are certain roles that government must play. The government needs to provide public goods. The government needs to provide things that the private sector cannot do for itself, which is obviously things like national defense, things like public safety, and it turns out also things like ensuring the safety of the food supply, just like ensuring the safety of the water supply.It turns out that regulation of what goes on in meatpacking plants, regulation of what goes into your food is something that you really want the government to do. Even people in the industries want that unless they are particularly unethical types. The people who are trying to do the business right want those public goods provided because if you don’t have those provided, then people will not trust their products. And this is not something that you can leave up to the private sector. It’s not something where you can do your own research. It’s a very complicated world out there. And the informational burden of trying to figure out whether the people responsible for your package of hamburger are actually following safe procedures, that’s beyond everybody. It’s actually quite similar in a way to public health measures, including, by the way, of course, vaccination. Like I said, it’s all the same story here: This retreat from even the most essential roles of government.So this is not an administration that’s trying to turn the clock back to 1930. It’s not trying to undo the New Deal. It’s an administration that’s trying to turn us back to the 19th century or before. It’s really just trying to undo even the most essential functions of government.They’re not doing this, I think, out of a philosophical concern. I don’t think they have a theory that says that we really don’t need these things. They just don’t think about it at all. They don’t do expertise. They don’t do thinking, really. And a lot of policy is just based upon who last spoke to Donald Trump and who has given him money. It turns out that this is a case in which Brazil — and it appears it’s probably Brazil, there may be some Argentine stuff here, but it’s probably Brazil — Brazil is notorious for not practicing internationally accepted standards on the safety of its meat.And so the last thing you want to do is allow Brazilian ground beef to be admixed. And by the way, none of this would be unique origin. This would be trimmings of beef that get ground up and mixed in with other beef. And basically, if you get a package of hamburger in the United States under this rule, you will have basically no idea where it came from. You’ll have no idea under what conditions the cattle were raised or how the meat was processed. And this is not something that’s in the interest of really anybody except personally this particular Brazilian beef baron who may have a bunch of unsold beef because the Europeans have turned back a shipment. And of course Donald Trump himself presumably is getting some financial benefit personally out of the whole thing. So it’s quite a story. It’s in a way captures all in one place everything that is going wrong, how quickly the United States is descending into kind of pre-modern, pre-development status. We’re just giving up all of the things that make an advanced society and advanced economy work. Okay, that was hard work. And I’m kind of hungry. So I think I’m going to have a piece of hamburger with some iceberg lettuce. Actually, maybe not. Take care. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 From Kakistocracy to Cheatistocracy 31.08.2026 13minTranscriptAt this point, it’s almost a commonplace to say that under DonaldTrump, America has become a kakistocracy, ruled by the worst. But I don’tthink it’s fully appreciated the extent to which we’ve also become a cheatistocracy, ruled by the most corrupt. Today’s commentary is a follow-upon yesterday’s primer, which was about the role of tax evasion both in leading to or contributing to our downward spiral into oligarchy and also as a surprisingly large factor in the budget deficit and therefore in America’s debt problem. Before I get to tax evasion, let me say something about where I’ve been going in my kind of intellectual journey into understanding oligarchy. As an economist, normally my instinct is to think about the invisible hand, to think about market forces, about technology as driving what happens to society. And even now there’s at least some extent to which the rise of kind of garden variety inequality, the rise of the top quintile at the expense of the middle, may be partially explained by the bias of technology towards higher formal skills, although that may be ending now with AI and all of that. But as I began to focus on oligarchy, on the very small number of people who have enormous wealth, enormous income, but the wealth is an even bigger factor — there are a really handful of people who have come to play such a large role.In our society, in our economy, and above all, of course, in our politics— I was forced more or less by the numbers to say this is not about the invisible hand. This is not about market forces. It isn’t even mostly about technology.Yeah, some technologies create winner-take-all markets that make people int he right place extremely wealthy. But the really big factor that’s driven us from the relatively equal society that we were 50 years ago — not obviously anywhere close to truly equal, but nothing like the dominance of a tiny elite that we have now — the really important factor is policy and above all tax policy. We basically stopped imposing progressive taxes that limited the growth of enormous fortunes. And sure enough, as the tax barriers to accumulation of excessive wealth went away, excessive wealth began to concentrate. This is, in many ways, the fundamental story. We got rid of, we ended the Gilded Age with its dominance by, as FDR said, the power of organized money, largely by taxing a lot of that organized money away. And we got back to something which in many ways is worse than the Gilded Age by taking away those taxes and allowing vast fortunes to snowball and buy themselves enormous political power, which allows them to snowball even further. One factor in all of that is the rise of simply not paying taxes that you’re supposed to pay. A lot of it is reductionist statutory tax rates. We tax corporate profits at a far lower rate than we did In the 1950s, we tax top incomes at a much, much lower rate than we did in the 1950s. But what’s also true is that we simply allow people to get away with not paying taxes to an enormous extent, to almost surely a much greater extent than used to be the case.The numbers are big, and in the primer I go through the tax gap. The money owed but not in fact collected is certainly north of $600 billion a year. It is something like 40% or more of the U.S. federal budget deficit. It is a major contributing factor to the accumulation of vast fortunes.What is striking is that far from really making an effort to rein in that tax gap, for the most part politically our system has moved to let it rip, has basically tried to make America safe for tax cheats. This is something that overwhelmingly benefits people with high incomes and large wealth because people with really big incomes, people who are extremely wealthy, for one thing, they just have much more complicated income. It’s much, much harder to track down and audit someone who has multiple businesses, some of which are dummy businesses, some of which may be real, but nonetheless are conduits through which money can move. And only the very wealthy can maintain offshore accounts that enable them to hide income and so on. So tax evasion is something that overwhelmingly benefits people with very high wealth and income. Not all! Not every billionaire is a tax cheat. There are levels and levels. There are some people who just feel that’s not something I want to do.People who feel that it would be wrong. Morality does exist. There are people who feel that their personal losses, should they be caught out cheating heavily on their taxes, would be large. So they care about their reputation.And then there are those who don’t.What’s astonishing is that we have, especially since 2010, especially since the hard right Republicans took control of the House of Representatives, we have moved to largely eviscerate any attempt to control that type of tax evasion. The numbers are really startling, and the IRS has actually put out very useful information. If you are someone with a very high income, the IRS stops counting pretty much at a million or more a year, but presumably it’s even more true further up the scale. In 2011, before the right-wing Congress was able to do its work, more than 7% of tax returns in that range were audited, which is not unreasonable because there’s obviously a lot of possibility for malfeasance there. It’s not saying that 7% of people with incomes of morethan a million were sent to jail. Obviously nothing like that, but we had widespread auditing, which among other things, encouraged people not to cheat on their taxes.By 2019, just eight years later, that number had gone from 7.2% to 0.7%. So almost nobody with high incomes was being audited for possible tax fraud.Now, why was that happening? There had been savage cuts in the funding to the IRS. Very large, at least 25 to 30% adjusting for inflation, something like a 40% reduction in the staff available for enforcement. And as it turns out, auditing the taxes of a very high income person is a lot more expensive than auditing a regular person. An ordinary blue collar worker, middle income, white collar worker who might be failing to declare some income, in many cases, it’s really very hard for them to evade taxes at all. And if they do, it tends to be relatively straightforward to pick apart what’s going on. And so audits of ordinary people are cheap. Audits of millionaires and billionaires, sounding like Bernie Sanders, are very expensive. And so the IRS, with limited resources and wanting to show that it was in fact auditing people, largely gave up on auditing the extremely wealthy. And this is a big number. The amount that we lose to tax evasion is something like the entire budget of Medicaid. It’s something like six times what we spend on food stamps. It’s something like 15 times the amount of money that Elon Musk saved by destroying USAID and killing millions of people in Africa. And yet it has been allowed to flourish.Notice, by the way, that this is all pre-Trump. Now, under Biden, there was a push to rectify the situation, a push to restore enforcement, increase the resources of the IRS, and increase enforcement actions in an attempt to tilt the agency’s priorities back towards where it should be, which is going after the big money. And that was just getting started. It takes a while to ramp those things up.And you know what happened. Of course, Trump’s one big beautiful bill did savage cuts in IRS resources for enforcement.Savage cuts in personnel. We’re now back to a situation where things are worse than they were before Biden started to try to fix it. So this is going to continue.What I find remarkable and interesting — I mean, I wouldn’t say that I’m baffled, but I think it is something that takes some analysis is why exactly.I mean, it’s one thing to favor the interests of the uber wealthy. Okay, we know that’s what the modern Republican Party is, whatever it may claim to be.But it’s another thing to systematically favor the least honest. What this policy does is It basically says if you are an honest billionaire — I’m afraid to name somebody because who knows what may come out in some future set of files — but if you are an honest billionaire, you are disadvantaged by the fact that dishonest billionaires are able to get away with cheating on their taxes. You should be opposed to that, but obviously the party that currently controls Congress, the White House, and the Supreme Court, that party actually prefers dishonest men of great wealth. It’s actually a positive preference for cheaters.I can speculate very loosely. It’s often been observed of Trump, and it’s probably true of some others in his camp, that at a fundamental level, he does not believe that anyone has good motives. And that someone who appears to actually be a decent person who plays by the rules is, by that very token, someone Trump distrusts.He kind of assumes that they must be even worse than he is. Otherwise, they wouldn’t be faking having good intentions, which people like him never have. Maybe there is something going on, something deeper. But in any case, wehave developed a system where not only do we enormously favor the interests of people who already have vast amounts of money, but we literally favor malefactors of great wealth, to use Teddy Roosevelt’s phrase. We literally favor people who not only have enormous amounts of money, but cheat, who don’t pay their taxes, who break the rules. This is not America. The general public still very much believes that people should pay the taxes they owe. We are not a country that valorizes, that rewards, or that honors people who cheat.But we have become a society that in practice does reward people who cheat. What does that do to our social cohesion? What does that do to our sense of ourselves as a nation? I think in some ways the moral decay is worse than the numbers, which is saying a lot.Take care. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Talking Interest Rates with Ricardo Caballero 29.08.2026 42minFor all my interviews and more, subscribe on YouTube.I’m spending a lot of time thinking about high interest rates, both for obvious reasons and because I’m reconsidering some of my own long-held views. So I thought I’d have a long talk with someone who has really studied these issues and now, I believe, may have been more right than I was. This may be even wonkier than usual, but trust me, it’s important.. . .TRANSCRIPT: Paul Krugman in Conversation with Ricardo Caballero(recorded 8/25/26)Paul Krugman: I’m talking today with a very, very serious economist, Ricardo Caballero, who is one of the most important macroeconomic thinkers of modern times. I was going to say of my generation, but actually, I’m an older generation—but of the currently, still vital creative generation. We’ve had discussions about a lot of events over the past 25 years that have involved some disputes that I hope we can get into in a way that people understand. And recent events, including the rise in long-term interest rates, have really brought all of those issues to the fore. So I thought I’d talk with Ricardo, who is the Ford International Professor of Economics at MIT, a position I once held. But anyway, hi.Ricardo Caballero: Hi, Paul. So wonderful to see you again. We still miss you at MIT.Krugman: Well, I miss the days when actually getting at the truth was what mattered, as opposed to dealing with all of the obvious lies. But anyway, I guess there are different stages in one’s life. But so, I will want to get into recent events. But one thing that really struck me is that there’s this long-running discussion basically around interest rates and international movements of capital where there are kind of, as I see it, two rival ways of thinking about it. It could be some of both—but one was about returns to capital and investment opportunities, and one was about people looking for safety and security in assets. And for the most part, I was on one side of that and you were on the other. And I’m starting to think that you were probably right. So, first off, how would you portray this discussion? And maybe we can go back and forth.Caballero: I don’t know whether they’re really different views because, you know, my view at least was always, when I say “a shortage of a store-of-value,” if you will, investment opportunities create those store-of-value opportunities and so on. So I never saw it as very contradictory. I thought there was an imbalance: lots of needs for savings, in particular in a very specific kind of saving—safe saving. And the productive structure wasn’t able to generate enough assets, especially safe assets. And that’s, I think, what led to the sort of “shortage of safe assets” type of literature, and that naturally depresses safe interest rates. If you look at the return on capital, actually, it was fairly stable. It was all absorbed by the opportunity risk premium, if you will. And so you can see returns both on safe and risky capital sort of declining in tandem since 2000, or earlier than that. And then somewhere around 2000, you can see that the safe interest rate keeps coming down, while the return to capital is sort of paralyzed. And what starts widening is the equity risk premium.Krugman: So let me just break in here. A kind of crude, simplistic view—probably my view at a certain point—was that there’s capital and then there are returns on capital. And when we start to see interest rates get really low circa 2000, that’s telling you that returns to capital are going down. And if we see a lot of money coming to the United States, it’s because, well, America had faster population growth than other rich countries, and we were leading the technology revolution. But you’re saying there’s a really big difference between buying stock—corporate investment—and buying U.S. government debt, which is safe. And that the United States was sort of better than the rest of the world at supplying these safe assets.Caballero: Absolutely.Krugman: And just going way back—the financial crisis, which seems to me like yesterday, but was in fact almost 20 years ago—involved all of these exotic financial instruments, the asset-backed mortgage-backed securities, which you interpreted as a response, to a large extent; not just fraudulent, but a response to a real demand. Right?Caballero: Absolutely. I thought there was a shortage of ultra-safe assets. So financial engineering got to work and they created sort of “synthetic safe assets.” Now, they were safe assets from the point of view of idiosyncratic shocks, but they weren’t from the point of view of systemic shocks. And to me, that was quite important in generating the financial crisis.Krugman: Yeah. And so idiosyncratic shocks are like, well, okay: a particular housing development turns out to be a bust, but a collapse of the entire housing bubble is... And so fancy math was used to create assets that were supposedly safe because you were pooling all this stuff. And so, in your view, it wasn’t just that you had evil, fraudulent financial types—though that too—but that they were responding. There basically just weren’t enough Treasury bills and stuff like that out there.Caballero: I mean, they realized there was a spread to be earned by creating these assets, and then there were regulatory failures that allowed them to hold them on their own balance sheets. And I think that’s when the really toxic mixture was developed, because you had these very low-capital-charge assets which weren’t really safe. But you’re right, it was this spread that sort of created the opportunity and then the regulatory arbitrage, if you will, that brought them into the balance sheets.Krugman: Okay. I’m going to be self-indulgent and tell you a quick story. Robin and I bought our New York apartment in early 2009, which turns out to have been perfect timing, although that was purely an accident. We had come into a slug of money courtesy of the Swedes. But as we were looking at places and I was looking at the bookshelves of people who were selling their apartments, and a whole lot of them had books on the Gaussian copula and stuff like that, which, as you know, was a technique that was used to justify the claim that these synthetic assets were safe. And so we were clearly getting a preview: there were a lot of apartments on sale from Wall Street quants who’d been fired because everything was about to fall apart.And so, in some sense, the setting for the financial crisis was that people wanted safe assets, and excessively clever guys on Wall Street invented seemingly safe assets. But then everything went to hell, and we had the financial crisis. And then we had this long period of really, really low interest rates. And your story would be basically, as I understood it, that all of these fake safe assets had been revealed as fake, and now there was a sort of piling into Treasury bills, piling into actually safe assets.Caballero: Indeed, and also partly the supply of sovereign safe assets—Italian bonds and the like—those also went away. And so we had a massive shortage.Krugman: Okay. Now, there was an alternative story. And believe it or not, listeners, we are going to get to where we are now as a result. But there was an alternative story that I guess Larry Summers came out with at first, but I actually had been toying with the same thing, which was that what was actually happening was a real lack of investment opportunities. This was the “secular stagnation” view.Caballero: You know, we were both at that conference. It was IMF, I think, and you may not remember, but that’s when Larry sort of came up with this theory. And you may not remember, but I stood up and I said, “Look, I buy a part of that story. But what you’re missing is that the return on capital hasn’t declined nearly as much as the safe interest rate.” And that’s what I was describing before—the equity risk premium increased enormously. But the return to capital, regardless of whether you measure it with national accounts or return on financial investment, did not decline nearly as much.Krugman: That’s right. So, national accounts being corporate profits divided by the value of corporate assets. And there really wasn’t a big decline in the profit rate.Caballero: Of course, in the recession itself, it did. But I’m saying afterwards it recovered.Krugman: Yeah. By like 2015, the recession is over and basically the interest rate on federal debt is lower than the rate of inflation. And so it’s basically free money for governments to borrow. One interpretation of that is, well, population growth has slowed and technology is maybe not as exciting as we thought it was going to be, and so there weren’t these opportunities. And you were saying that the numbers never supported that.Caballero: I don’t think so. I mean, elements of these stories are obviously correct, but I mean, there’s like 400 or 500 basis points that really came from widening in the equity risk premium.Krugman: By the way, the equity risk premium is when stocks historically pay a higher rate of return than bonds—certainly more than government bonds. And it’s always been a little bit of a puzzle why it’s so large.Caballero: Not for long, though.Krugman: Yeah.Caballero: Not so much now.Krugman: But it was more that people trusted the U.S. government and didn’t quite exactly trust corporate investments. And so that’s why the government was able to borrow so cheaply.Caballero: I think so. And also the demographic cycle helped on that dimension because, you know, older people tend to demand safer assets. So that’s also changing that composition.Krugman: Yeah. I wasn’t even thinking about that. So I have to say, I think we were kind of, in some ways, living in a fool’s paradise where governments can borrow essentially for free—certainly the U.S. government could borrow essentially for free.The case that a lot of us used to justify secular stagnation—and for some reason, the words here are all completely meaningless to a normal human being—but to justify this idea that we just had low returns, a lot of us talked about Japan. Have you spent time on the Japanese story?Caballero: I wrote a paper on Zombie Lending.Krugman: Oh, yes you did. Why don’t you tell us about that? Because that’s also an interesting thing that was a consequence.Caballero: That was a consequence. I mean, essentially, in Argentina, if you have a financial crisis, you just blow up. But in Japan, they had the resources to essentially keep banks alive and the like. And so that led to a process of evergreening loans. And we show that that reduced productivity growth. So it did have a real impact eventually.But there were other things at play in Japan as well. They had a massive financial crisis which certainly took away their mojo. It took many years, and then they responded. The fiscal policy sort of reacted too soon to the incipient recovery. So they fumbled on multiple occasions.Krugman: Yeah. And the story that we used was that, you know, the collapse of fertility happened there first. So there was a shortage of Japanese, which should have reduced returns on investment and maybe led to low interest rates, but maybe that wasn’t even the story for Japan.Caballero: I mean, I think it is part of the story, definitely. I mean, they certainly experienced a very acute demographic cycle. They were not very inclined to allow massive migration. So they had all the ingredients; there is no doubt. But on top of that, you had the financial crisis and this supporting of sort of zombie loans. And so they did terrible things to the productivity environment.Krugman: Given all of that, you might think that Japan would have fallen way behind on productivity. And they have lower productivity than we do, but not...Caballero: Well, labor, because they have lots of capital.Krugman: True. Okay. So this is a vision of kind of the history of the past 25 years as a search for perceived safety, investments where you can’t go wrong, and an abortive attempt to cater to that demand by providing a lot of clever things that looked safe, but weren’t really. And then a collapse of that. And then you enter this long period, because the financial crisis is 2008 and interest rates are still very low, at least as of just three years ago. And now all of a sudden, or so it seems, that’s gone away. So, what do you think happened? We kind of had a glut of safe assets instead of a shortage. What do you think happened there?Caballero: Well, I think it’s a combination of things. I think that first, there’s the COVID shock for sure, that affected the supply of assets all around the world. So now we have a lot more competition than we used to have as well. That’s one aspect. Second, it brought sort of the inflation monster into play. And that also complicated the life of bonds. And then markets became very bullish. So the equity risk premium we’re talking about essentially went away.So, to me, a lot of the movement that we have seen is really the equity risk premium up and down. The question is whether it’s structural or temporary. We also saw a compression of the equity risk premiums right before the dot-com bubble. And so the burst of the bubble also led to lower interest rates. So, in struggling with this, the question becomes: How much of this is structural versus how much of this is just some temporary phenomenon or not? So that’s one issue. That’s sort of the financial issue.And then the second one, which is not unrelated to this issue of the compression in the equity risk premium, is the AI boom. I mean, this is a massive investment and wealth boom, which is very important. So the wealth boom has boosted aggregate demand and that has increased equilibrium interest rates. We talk about the K-shaped economy; I call it financial Dutch disease. We have this enormous amount of wealth creation and therefore the interest rates have to be high. And then anything that is affected by high interest rates is struggling.Krugman: By the way, people won’t know this, but Dutch disease is a very long ago story, but it stuck. This was when the Netherlands discovered natural gas, and suddenly they were selling lots of natural gas, which made the—I guess they still had the guilder then. They still had their own currency. So this made the guilder strong, which actually was kind of devastating for Dutch manufacturing because they weren’t competitive anymore. And so this is a case where good news is actually bad news for large parts of the economy. And actually, I happen to know, the Dutch stopped pumping out the gas a few years back because the land, which was already below sea level, is subsiding further. But we still use that term.So you’re saying when people think the second coming of wealth has arrived because of a new technology, they pile into that, and then they’re not so interested in parking their money in safe government bonds.Caballero: Indeed, yeah. I mean, even without the secondary effect, you still get a boost in aggregate demand that comes from the wealth. Before the productivity of the AI boom arrives, you get the demand. You don’t get the productivity. That requires higher interest rates.Krugman: That’s right. That was very much the opposite, by the way, of what Kevin Warsh has been trying to argue. He’s been saying, “Well, because of AI, interest rates can come down because it’s anti-inflationary.” But the problem is, if the anti-inflationary stuff arrives, that may yet be some years down the pike. And meanwhile all the spending and the wealth that’s driving the stock market valuation... In a way, you’re saying that a lot of what’s happening should be good news, right? We have this technology, which is pretty impressive.Caballero: Yeah, it’s extremely impressive. Yeah, I wrote a little paper. It’s called Speculative Growth and the AI “Bubble.” I’m very optimistic about this technology. Now, whether I’m optimistic about the current valuations, that’s another story. But I’m optimistic about the technology. And I think there’s a good future ahead. But the good future, to get there at a reasonable speed, I think we do need a little bit of bubbly markets. And that’s the nature of the story. But it’s a fragile story because, you know, bubbles are fragile.Krugman: Yeah. And by the way, I don’t know if you saw this, but Stan Druckenmiller, sort of George Soros’s right-hand man and also Scott Bessent’s mentor, published an opinion piece in the Financial Times about how Bessent is all wrong to believe he can bring down long-term interest rates with his little bits of financial engineering, which was an interesting piece and interesting given the source and all that, but it appears, based upon the detectors, to have been entirely written by AI.Caballero: I see!Krugman: It seems Druckenmiller knew what he wanted to say, but couldn’t be bothered to actually write it. So he actually told Claude to write it.Caballero: I’m sure he wanted to blame somebody if it didn’t work well.Krugman: Now, it’s good news, we think. There’s this technology, which is amazing. It really is. I have to say, I’m using it for pretty nerdy stuff like, “Here’s this published table, but it’s a PDF. Can you please convert it into an Excel spreadsheet for me?” You know, that kind of thing. But it’s amazing how much time that saves.But it’s actually having this effect, where suddenly interest rates on federal borrowing are way up. Again, this is going to be a lot of nerdy questions because I’m really trying to scope this out, and I can’t think of a better person to talk to about it. It’s also true that a lot of interest rates beyond that and government debt are also up. Right? So does that make sense? If it’s a search for safety, should we be seeing home mortgage rates also going up by the same or similar amounts? Maybe they are.Caballero: They are in the sense that spreads are being compressed at the moment. So that’s consistent with the fact that there isn’t a lot of concern with risk. And so all the spreads are coming down. That sometimes has to do with “reach for yield” type phenomena. It’s pretty standard. The benchmark rate, which is the Treasury rate, tends to move more than the other ones outside of a financial crisis. But the spreads are being compressed. And mortgage rates are, in fact, rising—not one-to-one, but they are rising.Krugman: Okay. But it’s not one-to-one.Caballero: No. I haven’t checked, but I suspect mortgage rates are not rising one-to-one. But corporate spreads are being compressed.Krugman: Yeah, and that’s actually kind of how you are measuring. Explain to me, because I didn’t quite get it: You have quite a new paper on basically the elimination of the safety premium on U.S. government debt. How did you go about measuring that?Caballero: It’s a combination of things. I mean, the concept I have in the paper is one of the marginal costs of debt issuance. And that has two components. One is the spread, which we’ll discuss—the spread relative to a safe interest rate; think of it as the front-end monetary policy rate. And another one is the cost of rolling over the old debt at the new higher premium.So, my estimate is that these costs have increased by about 110 basis points, of which 50 basis points are the result of an increase in the premium—the spread—and 60 basis points is a result of these rollover costs. And the rollover costs come from the fact that now we have so much more debt that every time you get a little bit more of a spread, eventually when you end up rolling over all the old debt, that is going to cost you a lot more from the point of view of the fiscal deficit.Now, the most commonly understood term is the spread, the premium component. And that has two components. One is the rollover premium, if you will. That one I measured by the Treasury basis trade, essentially. You can probably explain it better than I can.Krugman: Yeah, I’m not sure I can do that either. But it’s essentially from how much more a Treasury bond pays over a swap that doesn’t use the same amount of balance sheet. And we call that the convenience yield, that Treasury bonds would actually sell at a higher price than the implicit price in a swap of corresponding maturity. And the swap is a swap on corporate debt, right?Caballero: No, no, no. It’s on safe interest rates. Just think of a futures contract. It’s the fixed rate of a future, of a swap. So think of a futures contract.Krugman: Okay. But essentially, people were willing to accept a lower interest rate if they were just buying U.S. government debt, rather than doing something more complicated.Caballero: Yeah, actually it’s not necessarily more complicated. But it happens that the Treasury bonds have a lot of other advantages. You could use them for so many things: collateral and so on. And that was worth a lot. And that’s an interesting angle, actually. It was worth a lot also because the marginal holder was a very different holder from the current one—central banks and so on. For a central bank, like the Bank of Japan, it’s not very useful to have duration through swaps and the like. They like to hold the Treasury bonds.Now it’s a bit different. The marginal holder may not be the Bank of Japan. It may be some levered agent in the economy, and for that agent, balance sheet and so on is very important. So if you look across all the maturities, that spread was on the order of -18 basis points before COVID, if you will. And now it’s around, I don’t know, zero.And the other one is the duration component. And if you look across all the maturities, essentially the U.S. didn’t pay much for duration exposure and now it’s paying like 40 basis points for that. So that’s the way you get to 60 basis points.Krugman: So yeah, people are demanding a higher interest rate basically to tie their stock up in long-term stability.Caballero: Yeah, I mean, they’re demanding a higher premium because the safe interest rate goes up for the kind of things we were talking about before—wealth and the like. And the question is, what about on top of that?Krugman: Okay. And so, I should have these numbers in my head, but a few years back, the U.S. Treasury could issue 30-year bonds—so basically lock in financing for the next 30 years—for several hundred basis points, several interest percentage points lower. And it’s now 5-point-something, which is just way, way higher than before. It basically means the federal government was paying hardly more, if anything more, than the inflation rate, and in fact less, and then if you subtract growth in the economy, basically no burden of debt.Caballero: Yeah. I mean, in real terms, we went from zero or negative for the 30-year bond to plus 2% or 2.5%. So it’s quite significant. And what I’m saying is that perhaps maybe one-third of that is a result of the fact that there is a little bit of a glut of all these assets.Krugman: And just going back, what happened was that the United States and other countries that also issue stuff that is perceived as safe just sold a lot of bonds, and a lot of that was because of COVID, right?Caballero: Absolutely. That was a big thing. And nowadays corporates are issuing a lot of bonds as well because we’re in the middle of this investment boom. And so, I think corporates in the U.S. are going to issue on the order of $2 trillion this year. That’s an enormous amount of competition.Krugman: Yeah. And probably people think of Microsoft bonds as being very nearly as safe as U.S. government debt.Caballero: For a while, Apple bonds sold at a higher price than Treasury bonds. I think it was a very brief moment, but I think it did happen.Krugman: I do see where sometimes people say, “I’m going to get you something that’s safer than U.S. government debt.” And I always wonder, what do you think anything is going to be worth if the U.S. government goes bankrupt? Who’s going to enforce the contracts?Caballero: I assume they are talking about price risk more than the default risk. And by the way, I wrote this paper on a lot of debt, if you will, and what that does to aggregate demand. But I’m not predicting any sort of crisis; I don’t see that. I think there’s nothing that can substitute for U.S. Treasury bonds. I always say, you know, there isn’t enough French real estate you can move to if you want to get out of the U.S. So the paper I wrote says precisely, “No, no, no. Assume that this will remain safe.” I don’t think that this is the issue. The issue is that it becomes more costly to issue this safe debt and that begins to become a big drag on aggregate demand.Krugman: In some ways you answered the question already. But I’ve been wondering, how much of what we’re seeing is just that there’s a lot of debt out there and you basically have to reward people more to get them to absorb it, and how much of it is an actual loss of faith in the safety of the stuff?I’m seeing back and forth on this, by the way. I’m reading Robin Brooks, and he’s talking about the debasement trade and people worried about the security of U.S. debt. And I think you are not worried. But the question of whether you are worried and whether somebody out there might be worried are not the same question.Caballero: Of course.Krugman: Do you see any signs that people are, in fact, losing faith in the safety of U.S. debt as opposed to just that they don’t really want all that much of it?Caballero: I think inflation risk is something that is a bigger concern. That’s a debasement risk more than, I think, a default—I would assume. I mean, I don’t know what’s on some people’s minds. But I think there is a much bigger concern out there about inflation, and particularly with the current Fed and, you know, interaction there is not very good. But I suspect it’s that kind of thing.Having said this, you are seeing a little bit of a change. You remember we talked about corporate bond spreads having shrunk. But not in the hyperscalers. Now, you have seen a little bit of concern there that didn’t exist at all a few months back.Krugman: Yeah, I have to say, if you go back just a few years and you looked at the big established tech quasi-monopolies, they had this enormous cash flow and these huge business technological moats around their quasi-monopoly positions. And how could they ever be in financial problems? And the answer is, well, if they’re going to spend $3 trillion on a technology that, however great it is, may or may not actually be profitable for the people who spend on it... That could do it. So, yeah.It’s at least arguable—I mean, you don’t have to get particularly political to say that the U.S. government doesn’t sound the way it used to sound. Maybe you can help me here. I’ve been trying to wrap my mind around what a loss of confidence in U.S. debt would mean. How would that even play out? When people say, “Oh, people are going to dump their U.S. bonds,” I always ask, “And buy what?” And you’re in that same camp?Caballero: Mostly, yeah. I mean, again, local is different. With a small scare, you can see lost revenue. There was an episode when inflation was a little higher than now and people perceived, for the reasons you just described, equity in this hyperscale assets hypothesis. And I think part of the reason the equity risk premium was so low—and now it’s been increasing a little—it was exactly that. Treasuries were perceived relative to the main shocks that we were experiencing—inflation, if you like—Treasuries were perceived as riskier than some AI-related equities. So you could see for local shocks and so on, depending on the nature of the shock, something going into equities and the like. But otherwise I just think there is nothing that can be done in size, in very significant size.But we can get a spike. Remember in March of 2020, I think it was, there was a moment in which foreign central banks wanted to sell Treasuries and the Treasury swap spread got unwound because of margin calls, and we did see big spikes in treasuries. And I think the swap lines that were created by the U.S., by the Fed and the like, were mechanisms to try to stabilize episodic things. But I call them episodic. I just don’t see anything that can hang in there for a long time without creating a matching mess.Krugman: Yeah. One of the marks of really, really effective financial policy is that nobody even notices that you did it.Caballero: Exactly. Absolutely. That was very well managed.Krugman: March 2020, for a couple of days, was absolutely terrifying. But they responded effectively. Although, actually, even then, what were people buying?Caballero: Cash.Krugman: Ah yes, they were piling into cash. And of course, the thing about that is we can print cash.Caballero: True, eventually. But first you have to go through a spike and then it happens.Krugman: Yeah.Caballero: But effectively that’s what they did. When you create a swap line, it’s just like printing cash.Krugman: Yeah, that’s right. I’d say I probably get about 15 emails a morning saying, “Here’s how the dollar is going to collapse. It’s the great American financial crisis.” And it usually starts with how irresponsible U.S. policymakers are. All of which is true. But how does this happen? You know, give me the mechanics of the crisis. And I’ve never been able to get an answer on that.Caballero: Yeah, I don’t see it either, but I do see a drift. I do see a drift. People can be very creative. You give them time. If you tell me now I have to relocate $40 trillion of debt somewhere else, there’s nothing I can do. But, I mean, give them enough time. People start finding certain things that they use, to find sort of safe and appealing, or more appealing [places to put their money]. So I think drift can do a lot more damage than events.Krugman: Yeah. I mean, I’ve been on a kind of related subject: the international role of the dollar in the global payments system. And it’s really, really hard to see anything replacing the dollar, but workarounds that people manage to do—you know, we’re witnessing that in the Persian Gulf as we speak. People can find their way around it.Financially, what keeps you up at night? I mean, we’ve both lived through and were very attentive during two inconceivable financial crises. Although the one in 2020 got solved very quickly. But I remember 2008. I actually had a relative who was working at the New York Fed and that weekend, the 13th, 14th of September, he wasn’t answering his phone and we said something must be up. And it sure as hell was.Caballero: That was a long weekend there.Krugman: Yeah, it was. He had bags under his eyes big enough to pack your luggage in. But anyway, are there scenarios out there that you worry about now?Caballero: More than a crisis, I worry about the fragility of the current boom. Precisely for the reasons we have been discussing. I think that high valuations are a needed ingredient in the development of this wonderful technology nowadays. But at the same time, we’re quite fragile to that. I mean, the good thing is that we have a lot of space to cut interest rates very, very rapidly if something goes wrong. But I think things are fragile.I’m exaggerating here but, you know, Venezuela did great under Chavez for a long time because the price of oil was rising a lot. And I feel that a lot of what is happening that is good has to do with AI covering up a lot of stuff. So I’m a little afraid about something that depends on high valuations that could come down very abruptly, and then we don’t do that great.Krugman: Yeah, I mean, you’re younger than me, but old enough to remember the late ‘90s. And I remember how everything seemed wonderful. Although that was a bubble during which people were happy. We’re now managing to have something different: It may be a bubble, but somehow everybody hates it.Caballero: A lot of people are very happy with the current bubble.Krugman: That’s true.Caballero: But it is also true that there’s a negative side as well. Now, having said that—this may be very optimistic, but I think that the current story is—there’s more alignment between the high valuations and the people that are really involved in generating this revolution. I think the fragility comes from different things. The Chinese may come out with some technologies that wipe out a big part of the competitive advantage we have and things of that kind. Sort of creative destruction-type things can be quite bad for financial wealth temporarily.Krugman: So, last question: What do you think of Scott Bessent’s attempt to push those top rates down?Caballero: I suspect they got very nervous, and I think that they wanted to cut a tail. I think he’s smart enough to know that he cannot change fundamentals, but I think precisely because of the fragility—I mean, I think they’re very worried that financial conditions can tighten very abruptly with a spike of that long end and then crash precisely the equity market and the like. And I think to me, this was a sort of “put”-type policy for financial conditions, which is quite important, obviously, for all the developments, political and economic.Krugman: Interesting times. This discussion will be posted four days after we’re having it, and given the way things are, it may be totally out of date by then. But I’m actually feeling somewhat more relaxed after this discussion, because I was a little bit worried that you were going to tell us that there are no safe assets anymore and the world is doomed.Caballero: Currently I don’t believe that. We shall see whether that’s naivete or wisdom.Krugman: Well, thanks so much for talking with me.Caballero: It was a pleasure. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Der Untergang 26.08.2026 12minFor all my interviews and more, subscribe on YouTube.Note: After I recorded this it was reported that Trump officials are threatening to demolish the Kennedy Center if it can’t be renovated to Trump’s taste (and presumably with his name added). Matches my argument exactly.Der Untergang naht.Pardon my German pronunciation. I’m going to take a break today from wonky economic analysis and talk about, well, Donald Trump, but in a slightly different way from what I think most people are saying. Not positive, obviously. Just before recording this, I saw that Trump wants to rename Lake Ontario Lake America. Which is silly, would be funny, except that this guy is the President of the United States. And it’s really kind of troublesome that someone in that position is that out of it, that petty, disconnected from reality. And look, it’s not news to anybody that Trump is ego-driven, disconnected from reality, and at the same time, somehow commands a level of deference and obedience from the entire machinery of the federal government that no president has ever had before. So this is really quite serious. What I don’t think people are fully aware of is just how bad it can get, given that Trump is so obviously dissociating, decompensating, that he’s not all there. Obviously, he was already a very problematic personality, which was doing a great deal of damage to the United States. I don’t think even now people fully appreciate the amount of damage that has been done. Even before the Iran War, Trump’s provocations, insults, his trade wars, really destroyed the world’s trust in America.America became a country that could not be trusted to honor agreements. It was a country that constantly tried to bully other countries. Our word was worth nothing. Our sanity was not to be taken for granted. And then, of course, along comes Iran, where in addition to showing that we’re not to be trusted, that we’re not going to be relied upon., we also showed that we were far weaker than people imagined. If there’s one thing people thought it was, well, America has a powerful military. It turns out, well, not as powerful and not nearly as competent as people thought. How much of that is the result of Trump and Hegseth degrading it and how much of it was there to begin with is an interesting question. But anyway, at this point, we are not loved, we are not respected, and we aren’t even feared. And we’re not getting that back. Even if Trump is succeeded by someone decent —God help us if he isn’t— but even if we have a more or less rational, well-intentioned government that follows, the world now knows that we are capable of putting someone like Trump in a position of unprecedented, almost absolute power and that it can happen again. And the world also knows that we’re just not as fearsome as we seem to be. That we can be defied much more successfully even by smallish countries than anyone really imagined. And we’re not getting that back. I anxiously wait for the days when we’re no longer a Trump-ruled country, but this is my country, and what will be left of us, what will be left of our role in the world, even once he’s gone? Okay, the title I gave, the way that I opened this talk was Der Untergang, which is the German title of the movie Downfall, about the last days of Adolf Hitler. I hope that nobody is going to complain about my using the German, right? We’re long past the point where it’s considered unthinkable and incredibly rude to make Nazi parallels. There’s a lot of people in this administration or close to this administration who are effectively Nazis, in some cases explicitly Nazis. America is not yet Germany under Hitler. But the reason we don’t have a functioning Gestapo in this country is not for lack of desire to have one. It’s because these people, at least so far, don’t have the juice. So all of the stuff, all of the parallels seem appropriate.And the parallels are there. I mean, the parallels are there even in seemingly small things. Hitler was obsessed with building a gigantic gaudy ballroom. So there’s just a lot of parallels in there. Now the main message of the movie Der Untergang is that it’s about Hitler in his final days who knew that he was losing. He knew that defeat was looming. He knew that his power was collapsing. And his reaction was, among other things, to take it out on his own country. Hitler never accepted that he had failed Germany. He felt that Germany had failed him. And so he had a plan, often called the Nero Decree, which was to destroy as much as possible of Germany’s infrastructure. Supposedly to deny it to the victorious allies, but in large part to punish Germany. Well, Trump knows. He may deny it, he may have his moments when he actually believes that the polls are all fake and all of that, but in many ways he is behaving like somebody who knows that his days of supreme power are about to end. He, of course, is not going to accept that it’s his fault. It’s the fault, obviously, of the Democrats, who are all communists. It’s the fault of the Republicans, who didn’t live up to his leadership. The fault of everybody but him. What does he do in the position of losing? Probably not committing suicide in the Fuhrerbunker, but still in the position of losing all of his power. Well, what you do in that position, if you are somebody like Trump, who is an empty vessel: there’s nothing in there, the only pleasure he appears to take in life comes from dominating other people. Well, one thing you do is you try to stick your name everywhere, or leave your imprint everywhere. So Trump, according to reporting by Swan and Haberman, spends most of his time thinking about his construction projects and trying to leave his mark on everything in Washington. What I don’t think we’re fully appreciating even about those projects is that there isn’t a whole lot of actual construction. There’s a lot of starting of stuff, but so far it’s been mostly destruction, mostly tearing stuff down. We don’t have a triumphal arch, but we have a hole where the ballroom is supposed to be. We have just a lot of damage having been done to our nation’s capital and to the iconic structures that were supposed to define, symbolize who we are as a country. The scale of the destruction is really quite amazing. So I’m not going to try fancy video editing here. I’m just going to show you a picture of what the environs of the White House look like right now. There you go. That bare area is the South Lawn, ripped up because of Trump’s cage match. You can see in the corner there the hole in the ground, which is where the east wing of the White House used to be. Basically, Trump has left, so far, wreckage in his wake. Even the things which have not involved tearing stuff down, the gilding of statues, the horrific redecoration of the White House, is surpassingly ugly. That’s partly because Trump has terrible taste, but it’s also, I think, a clear sign of aggression. He’s saying, oh yeah, you’re going to give me a 33% approval rating? Well, I’m going to make the nation’s capital as ugly as I can in this little time as I possibly can. Now, this is all superficial. This is stuff that can and will be repaired. It’ll cost a lot of money, but OK. So we’ll rebuild the White House. We’ll reseed the South Lawn. We’ll strip the gilding off the statues. We’ll make the White House a dignified place again. But how much more will be coming? When we talk about Hitler’s last days, as I said, one of his last attempted acts was what’s called the Nero Decree, which was an attempt to destroy as much of Germany’s infrastructure as possible, supposedly to deny it to the victorious allies. But clearly, and even there’s some evidence that he actually he clearly thought this as a way of punishing the German people for failing him.Now, historiography is a little more complicated than that, as it usually is, but that’s clearly the gist of it. That Hitler’s final acts were to basically try to bring everyone else down with him. Do you really want to say that that’s not what’s going to happen with Trump? Assuming that he loses much, if not all, of his power to shape events this November, and of course we’re all worried about how he may try to disrupt or overturn the election, but assuming he doesn’t manage to do that, he will find himself much diminished. How much damage will he do basically taking revenge on America?Because always you want to bear in mind that Trump hates America. He hates the values on which America was built. He hates democracy. He hates rule of law. He hates all of the things that are what we’re supposed to be about as a nation.But increasingly it looks as if he just plain hates this country because it doesn’t love him. How much damage will he do? How much damage can he do? I don’t want to make a specific prediction, but I’m worried. And don’t say that he won’t do that or he can’t do that. Those have been famous last words again and again over the past decade. So this is going to be even worse, even uglier, I think than most people imagine. Have a great rest of your day. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
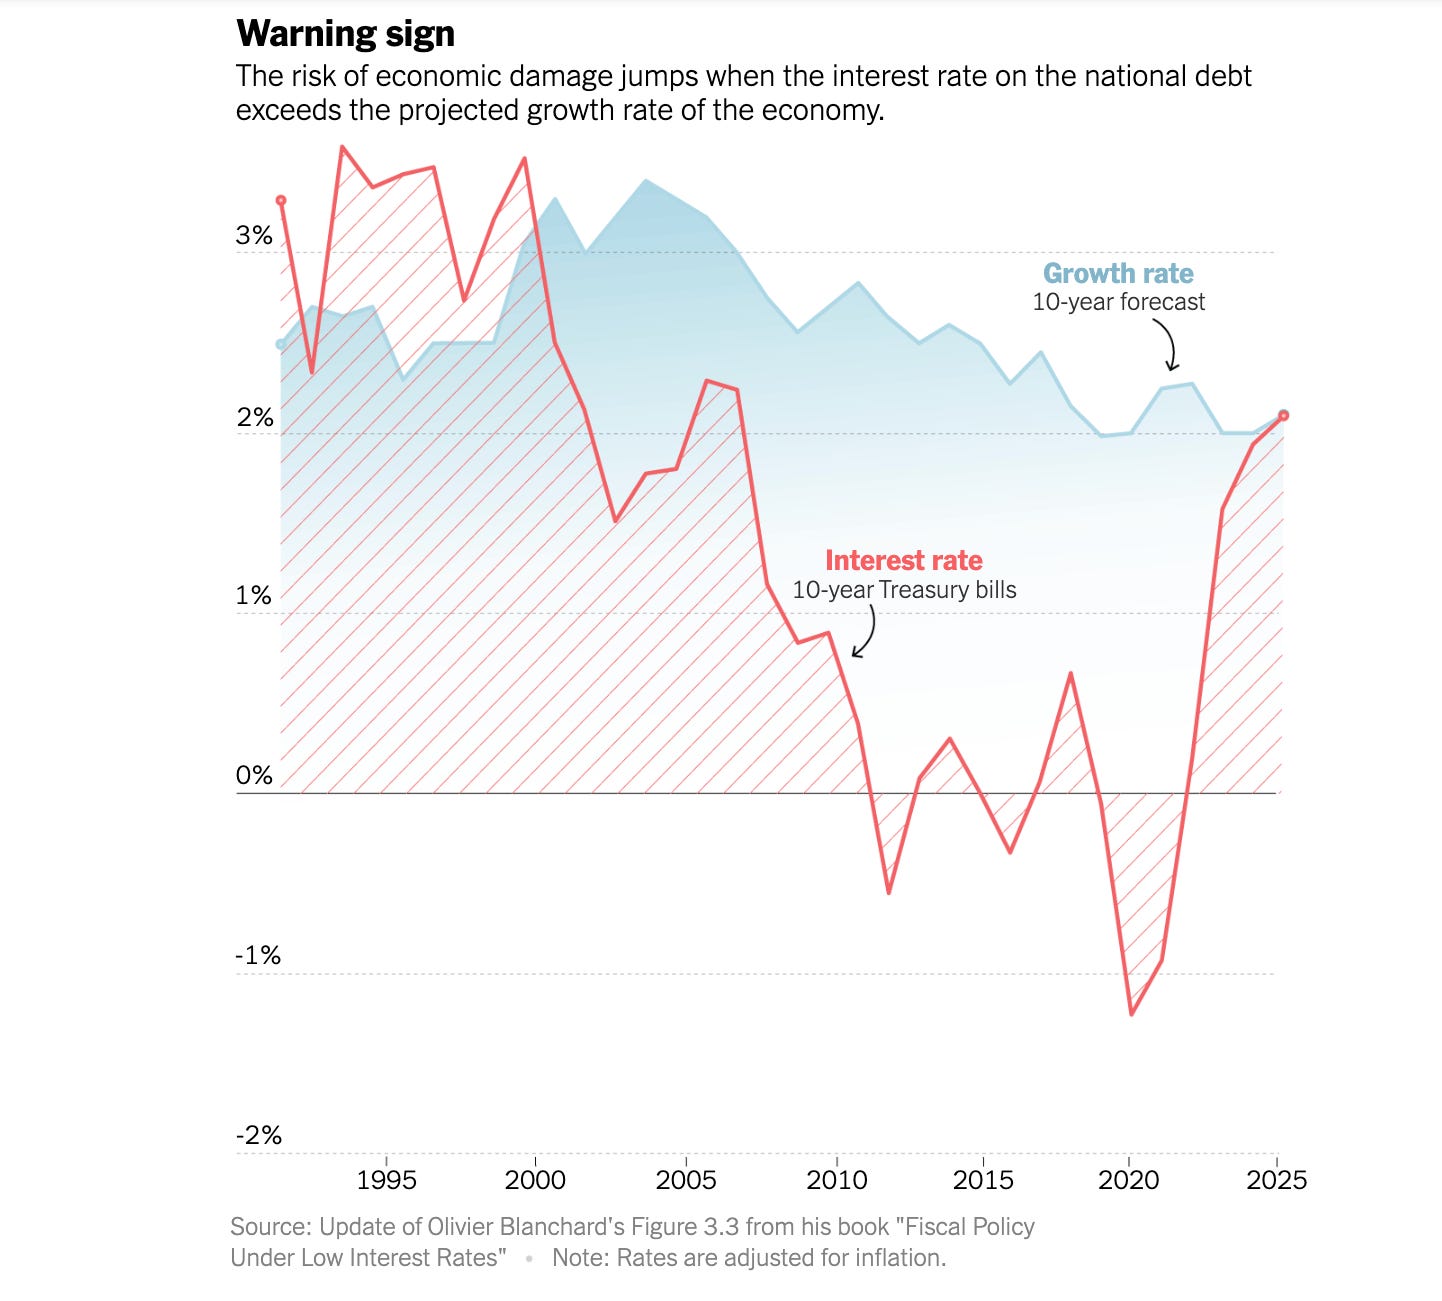 Jared Bernstein on Debt (Reposted with better transcript) 22.08.2026 42minFor all my interviews and more, subscribe on YouTube.Better transcript!. . .TRANSCRIPT: Paul Krugman in Conversation with Jared Bernstein(recorded 8/20/26)Paul Krugman: Hi everyone. Paul Krugman talking with Jared Bernstein, former chief economist, head of the Council of Economic Advisers under Joe Biden. Now a policy fellow at the Stanford Institute for Economic Policy Research and at the Center for American Progress, which is in DC.Jared Bernstein: And I speak to you from Alexandria.Krugman: Yeah, and the reason I want to talk with you is, you know, there’s a lot of headlines now about debt. Interest rates, particularly at the long end, are way up. You and I have both been Substacking about it. I think we mostly are on the same wavelength, but I’d like to go back and forth, and I want to talk about some work that you’ve done, particularly with Bobby Kogan. But what’s your take right now? I mean, we had all these headlines about forty trillion dollars of debt. This is very different from the way we were talking about debt a few years ago, so what’s your take?Bernstein: Well, Paul, like you, for many years I was pushing back on those whose hair was on fire about the urgency of the federal debt. I thought that that overheating was overheated, and that as long as the growth rate surpassed the interest rate and we sort of kept our deficits within kind of a normal range, we could service our debt without breaking a sweat. But a few years ago, I began to become more hawkish and less dovish for a couple of reasons. One, the budget math became less favorable; the growth rate looked a lot closer to the interest rate, and that was before this recent bump up in bond yields. But also, you know, I’ve been in government a lot lately, and it looked to me like neither side really cared much at all. The reaction function, as we say these days, seemed to have been kind of dead in a way that I thought was problematic.Now, this is not a pox on both houses. And by the way, here’s an area where you and I may have slightly different views. The Republicans’ tax cuts—and Bobby and I have done a lot of work on this—are public enemy number one here. Exhibit A, in terms of why we’re in the mess we’re in. But you know, Democrats have largely endorsed those tax cuts and, in my view, have done some irresponsible stuff, too. So that’s kind of my first take.Krugman: Okay. You’re talking about r-g, but that’s kind of an important point, right? Why do we think about interest and growth and debt? Lots of people are out there saying, “Look, the interest on the debt is now so huge,” but that’s not quite the whole story, but it’s closer to the story. Anyway, your version of it...Bernstein: Yeah. For me, a lot of this comes from paying attention to Olivier Blanchard‘s work. He has kind of wedged into a lot of our heads this notion that when the growth rate surpasses the rate of interest, it is possible to keep rolling over that debt and not get into a kind of debt spiral because you’re generating enough growth and revenues and incomes to sustain the debt or to roll it over. Meaning, you know, replace some old debt with new debt without worrying about the debt getting on an unsustainable trajectory. As soon as r is bigger than g, that’s when you have the threat of a debt spiral.That’s not all the math. It depends on the size of your deficits as well. But broadly speaking, for many years we had pretty good growth and pretty low interest rates. We can talk about how that growth was distributed—a lot of it didn’t reach working-class people—but the fact that g, the growth rate, was higher than the interest rate was one reason why I was less wound up about all this.Krugman: Yeah, one of my favorite things is talking about the question of “How did we pay off the debt from World War II?” And the answer is we didn’t. The debt when John F. Kennedy was elected was about the same as it had been on V-J Day in dollar terms, but it was just vastly smaller as a share of the economy because we outgrew it. As long as debt doesn’t rise relative to GDP, it’s not a problem. That means if the economy is growing and interest rates are not too high, not only don’t you have to pay off the debt, you can actually keep it growing as long as it just doesn’t grow too fast, right?Bernstein: Exactly. So the problem we face is when our debt grows faster than our economy, when the debt ratio, or the debt-to-GDP, just keeps going up and up and up.Krugman: Basically for much of the period when everybody was going on and on about debt, the arithmetic there was actually pretty favorable, right?Bernstein: This is precisely why I kind of did a bit of a flip. I have an Op-ed in the Times—it’s from at least a year ago—where I managed to actually get them to put a graph in, which, you know, they don’t always do in there, which portrays this problem. It shows how the growth rate used to just reliably be well above the interest rate, where the economy grows faster than the debt, and so your debt-to-GDP ratio sort of glides along in a way that’s not particularly worrisome. But it looks like it’s starting to flip and starting to change.And then if you look at the CBO forecast, they actually have the interest rate on the debt falling below the growth rate numerous years out. And their estimates actually are kind of optimistic in debt terms because they assume a number of things: they assume tariffs continue to generate a bunch of revenue, which doesn’t look to be the case; they assume that some of the Trump tax cuts would fade, but now they’re permanent. So yeah, the budget math has gotten less comfortable.Krugman: Okay. I want to get to the interest rates in a minute, but the deficit that we’re running right now is just incredibly large. I mean, we used to run deficits to fight wars, and then we started to have big deficits when you had severe recessions. But now we have neither. I mean, there’s a war, but it’s not like World War II, right? It’s a fraction of a percent of GDP.Bernstein: Right, but it’s not free.Krugman: Yeah, but it’s not forty percent of GDP. It’s something like six percent of GDP now, right?Bernstein: Exactly. It’s a little north of six percent of GDP. And according to the kind of numbers that I run on this, with the macroeconomy doing pretty well—and again, I know it’s not reaching a lot of folks; affordability concerns loom large—but you know, GDP is growing around trend, which is about two percent real. The unemployment rate is close to four percent, which is in the neighborhood of full employment. And the stock market’s booming. We should have a deficit that’s closer to three percent than six percent.And what’s happened here, Paul—and you’ve written about this extensively—is that the constant ratcheting down of tax policy. All those tax cuts introduced by Republicans, too often kind of kept in place by Democrats, have really broken the linkage between solid economic growth and revenue flows to the Treasury. And what Bobby and I show is that if you take the Bush and the Trump tax cuts out of the mix, our fiscal scene would look fine. So, you know, that’s important.What you can do is simulate what the debt ratio would be—by debt ratio we mean debt-to-GDP—or what the deficit would be (either one), or what the interest payments on the deficit would be. You can simulate those if you take the Bush and the Trump tax cuts out of the system, which means taking them and not just the original cuts, but all the following-on legislation that made those cuts permanent.You know, when I say Democrats have played a role here: I was in the Obama administration when we essentially made permanent 80% of the Bush tax cuts. That’s not a hundred percent, so I’m glad that we let at least 20% at the top end revert back to what they were. But that’s the exercise we did.Krugman: The blue line in that chart is the projection for debt on the current trajectory, and up to the point where it gets dotted, it’s the actual debt-to-GDP. And it’s really three rounds, right? It’s Bush, which were very much tax cuts for the one percent; then Trump 1, more tax cuts for the one percent; and then Trump 2, even more tax cuts, not entirely for the one percent. Where we are now is not at all where we would be if we hadn’t had all of these tax cuts.Bernstein: Yeah, and let me say something about this. First of all, I know you do a lot of economic history, which is just really great work in my opinion, and I just don’t want our viewers to not note that that graph started back in, I think, the late 1700s. So that’s some pretty good economic history there.Remember, those figures, including the one that showed a much lower, much more sustainable debt path, include all the spending that is in the system. The only change we’re making is the tax cuts didn’t happen. And so this is important, because there are always going to be people who say, “You know, it’s all spending,” and “It’s all taxes,” and that’s a common fight. But that figure keeps the spending precisely where CBO says it is. So that’s not a judgment on whether we have the optimal amount of spending—we can argue about things that should be cut or expanded—but those are the numbers; those are the facts.Krugman: One of the things that strikes me about this is that often if we’re trying to understand what it would take to be able to pay for even what we have, that we would have to have something like European levels of taxation or something radically different. And actually, all we really need for that is Clinton-era levels of taxation.Bernstein: Precisely right. Yeah, in fact, under the Clinton regime was the last time we had an annual surplus, so the debt-to-GDP was starting to come down, which is what happens when you have a surplus. Now, a lot of that had to do with a big bump in capital gains, and that led to more revenue flows. But that’s precisely the channel that I think we’ve shut down with this endless ratcheting down of tax policy.Krugman: Yeah, it’s an amazing thing. And you and I both remember the nineties, and I didn’t feel that we were living in a regime of oppressive taxation that was stifling entrepreneurship. Those were the roaring nineties.Bernstein: No question. The extent to which the political class, particularly Republicans, has convinced so many people and so many media writers that taxes are always bad and must always be cut is one of the reasons we’re in this mess.Krugman: Okay. Now, clearly the deficit is so big because of, again, another round of tax cuts and the legacy of the past tax cuts. But also, the arithmetic of debt used to basically kind of melt away relative to GDP because of growth exceeding the interest rate, and that’s not the case anymore. Although the gap is not that large even now, right? It’s sort of like a four percent average interest rate on federal debt and maybe three percent nominal growth, three to three and a half. But still, it’s very different now. But the thing that is really striking is that interest rates are way higher than they were not very long ago, especially, of course, at the long end. So I’m actually not fully sure myself what I think is happening, but why do you think interest rates have gone up so much?Bernstein: You know that old movie—I think it’s called Murder on the Orient Express—where it turned out, spoiler alert, that they were looking for one perp, but there were like 17 perps?Krugman: Yeah.Bernstein: I think there’s a bunch of reasons. To me, it seems credible and plausible, so I don’t feel particularly confused about what I’m seeing, though I may be missing something, but I would put at the top of the list that there are two very large demanders of credit right now in both the US and other economies as well. Those are the AI build-out and all the picks and shovels therein. Those folks are now leveraged, meaning they’re borrowing somewhere between six, seven hundred billion and a trillion this year.Krugman: Right.Bernstein: I’ve seen plausible estimates that they’re going to borrow a trillion dollars. By the way, a lot of those AI companies used to invest using cash flow. They weren’t leveraging; now they’re borrowing. And they’re borrowing hand over fist. A lot of investors are confident about those returns. I personally think it’s kind of bubbly, but they’re confident about those returns, so they’re certainly buying that debt.The other big competitor is the US government, and I just mentioned maybe the AI bros will borrow a trillion this year. Well, we know that the US government’s gonna borrow twice that, a little bit north of two trillion. That’s thing one.Cause number two, is the Trump-induced inflation concerns. So look, if you think that inflation is going to be high and sticky and you’re about to lock up some of your money for a while in a bond, you might want an inflation premium. You might want a little bit more compensation on that interest rate to account for the fact that this is all a nominal deal, and so you want to be compensated for higher expected inflation.Then there’s the fact that Kevin Warsh has gotten off to a bit of a shaky start, and I think that’s spooking markets a bit, and that kind of uncertainty also calls for a higher risk or term premium.And then there’s the fact that the country’s being run by an orange maniac. I think that is kind of a long-term risk premium that any investor is concerned about. Some foreign investors, who have often bought a lot of our debt, are saying, “Huh, maybe not so fast given the way this country is governed right now.” So if you put those all together, to me they tell a pretty compelling story.Krugman: Okay. I think I mostly agree with that, except I have a couple of questions. One is that this is global, right? Interest rates are up all around the advanced world. They’re more or less moving on parallel tracks in Germany, with their famous, slightly insane fiscal discipline, and in Japan, where we used to say nothing ever seemed to matter. I mean, the AI boom is mostly here, and the orange maniac is only here. He would like to be elsewhere, but he’s only here right now. So—Bernstein: I think he spills over into some other places, but yes.Krugman: Yeah. So, is there kind of a common story?Bernstein: I mean, it’s a great question, and I should have said: I don’t think anybody can explain 100% of this variance, but my R2 gets up there pretty good, I guess. I think the problem is that the fiscal accounts of other countries are looking a little bit more like ours than they used to, and that they also seem to be facing a borrowing crunch.Japan, as you just mentioned, would make our debt-to-GDP ratio look very, very tame, because of course they’ve been north of 200%. And for years, nobody really thought that was too big a problem. But I guess because of some of the global risks—you know, we have geopolitical dynamics; when energy is stuck in the Strait of Hormuz, that is a much bigger deal for Europe, for Japan, for China than it is for us. And so I would argue that the combination of geopolitical tensions and unbalanced fiscal accounts is probably pushing up long rates in other countries as well. But there’s probably more to it.Krugman: We have a couple of financial indicators that are supposed to capture some of these risks. There’s breakevens, right?Bernstein: Yeah.Krugman: The US government sells bonds that are supposedly protected against inflation, and the spread between those and regular bonds should give you an indication of what Mr. Market thinks is going to happen to inflation. And that really isn’t showing anything, right?Bernstein: Right.Krugman: And then there are credit default swaps; insurance that will pay out if a company defaults. And there are credit default swaps on the United States government, although I always wonder a little bit what good any contract is if the US government goes into default. But anyway, those are just not flashing red at all.Bernstein: Yeah, I can speak to that. There’s a couple of points here, one of which I think is very important that you made in your post this morning, and I’ve been trying to stress as well. I really want to make sure we get into it, which I will here.The first point is that a second ago I said there’s an inflation premium in some of these bonds, meaning that credit investors want to have a slightly higher return because they’re worried about expected inflation. I think that’s a pretty small part of the puzzle; I think it’s more on short-term than on long-term loans. And this is clear if you look at where you really see the increase—for example, the 30-year bond is in the inflation-protected version, and that tells you that it’s not just inflation; it’s making the breakeven point a different way. And that tells you that there’s some nervousness about the long-term prospects of the US project.The important thing that I wanted to nail here is that I think of this as much more of a slow burn than something that’s going to explode this week or next week. I don’t think the US is going to have a Liz Truss moment. I’m referring to the case in the UK where creditors engaged in what’s called a sudden stop: they looked at her fiscal plan and said, “That’s it, we’re out. We’re not going to invest in that country anymore.” I don’t think that happens here, for a variety of reasons that you and I can tick through.But that doesn’t mean that everything’s fine and happy-dappy or we’re out of the woods. It’s more of a slow burn, this upward pressure on rates, which folds into affordability—mortgage, auto, credit card loans, and so on—that is a problem for American households and consumers. And that is less of a “what’s inflation going to be next week” story and more of a “higher for longer” problem, where rates look to me and to many others like they’re going to stay up for a while because these problems are structural.Krugman: Yeah. There’s a lot of crisis talk, as there was, by the way, back in 2010 when there was really no problem at all. And my problem with that has always been: explain to me how that happens. You say people will go on a buyers’ strike and try to sell all of their US government debt, and my question is always, “And buy what?” I mean, it’s not like there’s an obvious place. Even for Britain, the Liz Truss moment was much more limited than people claim. And for the US as a whole, it’s not like Greece, where people were demanding euros and the Greeks couldn’t print euros. As someone said, it’s that we should be thinking about termites, not a tornado.Bernstein: Yeah, and here’s why I think this is so important, and you and I have both been circling around this point: It’s very important for human welfare—not just American, but for human welfare—that the current thugs running the government be banished and held accountable. I’m sorry if that sounds partisan, but I don’t think it is.And for that to happen, I don’t think candidates can run on—I remember the John Kasich platform, which is, “Vote for me and I’ll lower the debt and the deficit. We’ll all eat our spinach.” And I think that’s a mistake. I think it’s a mistake politically, and I think it’s a mistake economically. As you wrote this morning, don’t panic. I agree with that. This is a structural problem that’s not going away anytime soon, but we can chip away at it by reversing some of the high-end tax cuts, which I think would be both progressive and send a signal to markets and investors that we’re actually back in the business of having a reaction function to our unsustainable path.But first and foremost, we have to meet the very basic, urgent needs of households that have been left behind for too long: health care, child care, housing, energy costs. That, to me, is the first demand on fiscal policy. And so I think the fact that neither you nor I see a pending sudden stop or credit crisis—we could be wrong about that, in which case we’ll have to reconfigure—but based on history, I think we still have time to get this right, and we should do both. We should walk and chew gum.Krugman: Okay. At the risk of delaying a moment until we get to what to do, there’s one thing that kinda bothers me intellectually: during the era of low interest rates, we had a really good story—secular stagnation—basically that largely because of low birth rates and a stagnant working-age population, there was just going to be lots of savings and not enough places to spend it on. And that’s kind of what we thought had happened to Japan. And now here we are.Just six years ago, I would have been a full-on secular stagnation guy, and now we have, whatever it is, 5.3% interest rates on the 30-year. Were we all wrong about that, or did something really radically change?Bernstein: I think that we were over-torquing or over-indexing a bit on a period where interest rates were uniquely low, and we built a big story about secular stagnation that I sort of believed at the time. But I look back now and I think that perhaps that wasn’t as believable as we thought.I think what might have been happening instead was we just had what Ben Bernanke called a global savings glut. We had excess savings, and there are a lot of reasons for that; it doesn’t have to be a lack of investment opportunities. A lot of it had to do with international imbalances, which you’ve written a lot about. And so these excess savings found their ways into U.S. Treasuries because it was the safest debt you could buy, and the U.S. looked like a going concern, so a lot of those resources flowed here. And that glut of savings, often coming out of Asian trade surpluses, led to rates that were really quite depressed for a long time. But as those dynamics changed, I think the savings glut is in the rearview mirror and the dynamics are more like those we’re talking about today.Krugman: Yeah. If I can say, one intellectual trap that I fall into far more often than I should is the lure of a beautiful model that seems to fit the facts for a while. The secular stagnation model was lovely, and it all fit together, and there were the low interest rates. And then all of a sudden, it wasn’t really that solidly grounded. But the fact that a model seems to work for a while doesn’t necessarily mean—Bernstein: Well, it may have been the right model for the time. And look, you’ve made a career and won a Nobel Prize for beautiful models, so I wouldn’t—I don’t want to wave you off of that.But I think there’s another dynamic to this—see if this resonates with you. One of the foundational principles behind secular stagnation is the idea that there’s more savings than there are credible investments, or places to put it; there’s just an absence of investment.Krugman: Right.Bernstein: And by the way, when Larry Summers raised this issue of secular stagnation, Ben Bernanke stood up at the IMF conference and said, “Wait a second, there’s lots of places to invest.” I’m not sure that was exactly right at the time, but it sure is not the case now, right? And that’s the AI boom.There’s this tremendous investment opportunity going on now. Again, I think those guys are over their skis because there’s so much more investment than there is profitability right now that I have bubble worries, and Ryan Cummings and I have written numerous pieces on this. But secular stagnation, or the absence of investment to absorb the excess savings, may have been a fact for a few years there, but as this new technology came along, as is often the case, you now have an investment absorption mechanism.Krugman: Right. And it’s probably worth saying, just going back, that it’s not just that the hyperscalers are borrowing money when they used to not have to, but also presumably before, all of these huge profits being generated off our social media addiction were effectively being parked in places where they could then be lent out. And now, instead of pouring water into that pool, they’re drawing water out of it, and that adds to this pressure.Okay, big question: hopefully January 20th, 2029, President—name your favorite—with majorities in both houses comes in. And aside from needing to go after all of the legacy of corruption and all of that, they’re going to come in during what looks like it’s going to be a less forgiving financial environment than we might have hoped. What do you do? What’s your agenda for how we address all this?Bernstein: Well, first of all, from your lips to God’s ears, as we used to say. If we find ourselves in that situation, I will be partying in the streets and not worrying about the interest rate, at least for a few days.I’m sure you’re right, and it’s an important question and an important framing of the question. I think there’s a path forward, though. First of all, we should definitely hold the Trumpies accountable and in a big way. I’ve written about that, and I think we have to Trump-proof our government because other authoritarians will come along. But if that’s all we do, we’re falling short. We really have to attack with the affordability agenda. And there, I think we should look at not just Mamdani and some of the others on the left who are making delivering the absolute key plank of their political project, but so is Abigail Spanberger and Mikie Sherrill from the center. So it’s not just a left-center thing; it’s just about rejecting the status quo and delivering to American households who’ve been not just abandoned, but abused for so long, especially under this administration.And in terms of the context of what we’re talking about now, how do you do that if you’re in a high-rate environment and you have this budget outlook? Well, we have to reverse the high-end tax cuts. We have to close investment loopholes. We have to close the tax gap. We have to fund the IRS enforcement mechanism, because for every dollar you invest in IRS enforcement, you collect something like nine or ten dollars in taxes that are currently being evaded almost exclusively from the top of the scale. Closing the tax gap is a project that could yield five, six, seven hundred billion per year.Krugman: Let me, by the way, explain again for listeners: “the tax gap” is a term of art. It’s not just hand-waving; it’s speaking specifically about money that people owe that we’re not collecting because the IRS doesn’t have the resources, and it’s overwhelmingly very high-income people. So you’re saying that’s like two percent of GDP.Bernstein: I recently heard Natasha Sarin talk about this and she used, I think, that exact figure. I’m colorblind, so I’m not sure what color it was, but the chart that Bobby Kogan and I used—I think it was green—that could get us closer back to that debt-to-GDP line that’s much more sustainable. And they rest largely on applying taxes to where income and wealth have exploded at the top of the scale, so they neither hurt middle-income people nor compromise the affordability agenda.I don’t want to be too Pollyannaish about this: a dollar spent on childcare is a dollar that’s not available for debt reduction. But what I really don’t think we should do is say we have to come in here and clean up the Republicans’ debt mess as our first priority. Anything we do that stops digging us into a deeper fiscal hole—even if we’re digging more slowly, or even better yet, stop digging, not necessarily filling—would be, I think, not only good fiscal policy, but probably welcomed by the markets as a sign that the congressional reaction function to the fiscal outlook isn’t dead.Krugman: I regret to inform you that the good debt scenario, if we hadn’t had all of these irresponsible tax cuts, the line is orange, which is kind of an unfortunate choice given where we are in America right now.Bernstein: Whoops.Krugman: But anyway, I think you may have partially answered my question. When I look at that “if we hadn’t had those tax cuts” line, that would be great. If that was where we were, then I certainly wouldn’t be worrying at all about debt. But although those tax cuts were very heavily tilted to the top, with something like thirty to forty percent going to the one percent, reversing all of them would hit a number of people who at least think of themselves as middle class. And so the question is: what is within the realm of the politically possible that we can actually do?Bernstein: Great question. And I definitely have argued and tried to stress that the right place to start and to linger is at the top of the scale. I don’t think we should raise taxes on middle-class or middle-class-adjacent people; they’re having a hard enough time already and don’t need an extra tax burden.But the extent to which income and wealth have accumulated at the top of the scale—I’m sure you’ve seen the factor share data showing that the labor share of national income is kind of uniquely low and the profit share is uniquely high. And so I think we have to be pretty aggressive in that regard, but we can do so without dinging the middle class.If you listen to some budget hawks, they say we have to get back to that orange line. To be clear, I’m not saying that. I don’t think we do have to get back to the orange line. By the way, Danny Yagan has some nice papers on this, saying that we can be really gradual about getting back to some version of fiscal responsibility, but we have to move in that direction. We sort of have to change the sign, even if the magnitude is tiny.Krugman: Yeah, I think the post-World War II story is actually kind of helpful here because people talked for a long time about, “How are we going to pay the national debt? How are we gonna pay off the war debts?” And we never did. In fact, by sometime in the sixties the debt was higher in dollar terms than it had been, but the trajectory of all of the ratios was down, and we probably don’t even have to do that steep a descent, right?Bernstein: Yeah. Some people want to say that AI is gonna save our bacon because it’s gonna generate so much growth. In the piece with Bobby, we have a section on it, and my view is kind of like: hope for the best, plan for the worst.Krugman: Yeah.Bernstein: I’m kind of stuck on the fact that the internet really did eventually have a strong productivity impact, and then it went away.Krugman: Yeah, things can go into reverse, but there was only about ten years of good growth.Bernstein: Yeah, exactly, and then we kind of got back to where we were. So a lot of the AI productivity discussion assumes that not only will AI boost the level of productivity, but it’ll just keep getting better and better and better so that it improves the growth rate. And you know, I hope that’s true, but I certainly wouldn’t bet on it.Krugman: So, what are you hoping for in the spring of 2029 as our hypothetical virtuous government comes along?Bernstein: I am hoping for the following: I spend a fair amount of time scratching my aging noggin with the question of how much of the damage done by the Trump regime is temporary and can be quickly repaired, or is long-term and will be with us for a while.If a good Democrat takes over and we have some legislative power, can we restore good relationships with Canada and Europe? Or are they gonna be like, “Screw you, we’ve seen what you guys do. You’re okay, but we don’t know who the next guy’s gonna be. We might be looking at President Vance around the corner.”So I guess what I’m hoping for and looking for is that the damage can be reversed in my lifetime, which isn’t the longest span of years. And that’s an open question.What about you? You answer that question.Krugman: Well, okay. When you ask me about the economics—can we restore, can we even significantly reverse the drift to oligarchy—I’m actually fairly optimistic that it’s within the realm of the doable. When it comes to our international relations, when it comes to our military credibility, I don’t know. I think we’re talking about a generations-long project, and that really upsets me quite a lot.At some level, you know, I talk about Iran or something like that and I say, “Okay, this is Trump’s failure and we should wrap it around his neck.” But in the end, it’s my country, too. And my God, we are not the country we were in the eyes of the world, and I don’t know when we ever will be again.Bernstein: I agree with you, Paul, and I share that worry. I’ll only say the following: it may be a generational project, but if it is, it’s a great generational project, and generations should be anxious to undertake it.Krugman: Well, on that happy note, thanks so much for talking to me. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Defending the Bonds 21.08.2026 1minGet full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 The Misery Will Continue Until Morale Improves 17.08.2026 15minAccording to an old military maxim, amateurs talk about strategy, professionals talk about logistics. But these days we need a third category: Immature, insecure guys think that war is about acting tough and looking cool. Hi, Paul Krugman with a podcast update for today. I want to weigh in on the incredible rash of stories about how Trump and company are eviscerating the military. It is truly remarkable. If there’s one thing that we thought that the United States was still kind of number one at, it was that we had the world’s premier military. Now, of course, we managed to rather quickly effectively lose the war with Iran, although current management will never admit it. But also just a series of stories, some of them related to that war, some of them going beyond and to other areas that just are truly shocking, even for somebody like me, who had no expectation that this administration would be doing any good for the nation. Just to remember the story: So first we had the big warning that the U.S. military was basically running out of ammunition. That the precision missiles that are so essential to waging war were largely gone, expended unproductively against Iran. And clearly the cost benefit calculus was a disaster because the Iranians were sending cheap drones and we were using multi-million dollar weapons in an attempt to counter them. After that, we got the story about the horrific conditions on board the USS Lincoln, the aircraft carrier that’s been stationed for a very long time without, it appears, adequate resupply and with toilets flooding. Apparently just horrific conditions, which turn out to be not unique to that ship: Other ships are having problems. There’s the USS Boxer, an amphibious assault ship, which apparently has run out of feminine hygiene products, among other things. Okay, so we have those horrific stories. And then we have the stories about Trump intervening. Demanding, first, that the Navy construct a whole new class of ships, Trump-class battleships, which are useless and would be sitting ducks. Then demanding that the Navy replace modern catapults with steam catapults, which he thinks are cooler. And then demanding that they relocate the command tower on aircraft carriers because he wants them to look more like the way they looked during World War II. Is this America? I mean, think about the American way of war. We are not a warrior nation, which is fine. We are a lot of other things.We were a nation that was supreme in the arts of peace. We were a nation of know-how. America won its wars by doing the arts of peace right, by.building better and more stuff than other countries. By getting our act together in ways that didn’t necessarily involve fighting. Of course, you always need courageous warriors. You always need people able and willing to risk death in the service of their nation. But what America was supreme at was logistics. If you ask how did America and its allies pull off D-Day, well, a lot of it was being able to deliver supplies to the beaches of Normandy in a way that the Germans never thought was possible. America was always the place, the country that was really good at logistics. For us to be not feeding our sailors, not able to keep ships that are not, after all, under fire all the time, to keep the plumbing working, that is incredible. The idea that the president is imposing his personal aesthetic preferences to undo design decisions that were made by military professionals is also basically incredible.Okay, what is this all about? And what happened? Some of it is specifically military, but mostly it’s not. I think these military failings should be put in the same context as the frantic and disastrous destruction and redesign of Washington, D.C. The demolition of the East Wing. The disastrous attempt to refurbish the reflecting pool to reflect Trump’s aesthetics. Even the gold leaf and gold lettering that is polluting the White House. All of this is really part of the same picture.So what is going on here? Obviously we have a seriously mentally ill, mentally deficient guy with his finger on the button. The president of the United States is clearly dissociating, I’ve been calling it sundowning because I personally saw sundowning during my father’s awful last year. Trump is not in full possession of his faculties, and he is obsessing about things that are really just kind of remnant ego trips. I haven’t read the Haberman book yet, but reportedly he spends a large fraction of his time and probably a larger fraction of his mental energy on his redecoration projects, which aside from all being carried out disastrously are also in incredibly bad taste. But this is where he is. He’s actually more interested in his giant, tacky, gilded ballroom than he is in the fate of the nation. But how does somebody like this end up able to impose his will on these disastrous things? How does he end up able to eviscerate the military? Well, part of it is that this is a wannabe authoritarian regime. We’re in a peculiar state now where the United States is not yet a police state. It is not yet a place where the secret police will cart you away for expressing the wrong opinion, unless you are not a white U.S. citizen. Maybe the time is coming when that will happen. But in any case, we are not yet East Germany under the Stasi. We are not yet Putin’s Russia. But the Republican Party, senior politicians, who should be feeling that they have at least some dignity, ability to take a stand, behave as if they were living in an authoritarian state. They’re obviously terrified. They’re afraid to express any dissent. They go along with Bush’s — see, I’m dissociating, living in the past myself. They’re going along with Trump’s wishes.On top of that, I think it really helps to think of the ruling party in America right now as being a party that behaves as if we were a full-on authoritarian state. And one of the things we learn about in studying how authoritarian regimes behave is, first of all, that the leader actually can be possibly the worst informed person in the nation because nobody dares to tell him bad news. We’re hearing this a lot about Putin, that he doesn’t know how badly his war is going. Well, Trump in many ways probably still doesn’t understand how badly his war is going.The really striking thing about the munitions shortage and now the horrible conditions on US ships is that to the extent that any action has been taken on either of those issues is it has been only after extensive reporting in the press. So now the Pentagon is talking about a crash program to have defense manufacturers produce more of the missiles that we’ve been running out of. But it’s not clear it’s even started yet, and that call didn’t happen until many months into the war, whereas the munition shortage was obvious to independent observers just a few weeks in — that we were expending munitions that we couldn’t replace. Nothing happened until there was widespread press reporting. The USS Lincoln has finally been recalled for refit and shore leave. But that didn’t happen until after many press stories about it, all of which were denied, but it’s very obvious just looking at the behavior that the Pentagon and Hegseth and Trump finally reacted saying, oh, I guess something needs to be done. We can’t let this go on. But they didn’t do it until after the press reported.Now, is this because they’re totally callous? Well, they are. They don’t care at all. The people who yell support the troops most loudly are the people who actually have no interest whatsoever in supporting the troops. But I think it’s probably also the case that they may not have known. That nobody told Trump that we were running out of missiles. He may have read some press stories to that effect, but he said that’s all fake news and nobody within the administration was willing to tell him. They may not have been willing to tell Hegseth either, who by all accounts flies into a rage and punishes anybody who brings him bad news.So they just didn’t hear about this. They didn’t hear about the munitions. They didn’t hear about the conditions for US sailors until the drumbeat fromthe press became too loud for them to remain insulated, to remain in denial. So this is what happens. This is the problem with authoritarian regimes. It goes with the related problem with authoritarian regimes, which is that they have a single point of failure. You elevate one person to a position of untouchable authority, and if that person loses it, that person is sundowning, there is no recourse. One more thing to say about what’s going on is that authoritarian regimes systematically promote incompetence. This is Hannah Arendt on totalitarianism. That it’s not just that they value loyalty above competence. They actually actively dislike competence. Because someone who is competent, someone who knows what they’re doing, might stand on their dignity, might refuse to follow instructions from above. You need third-raters or worse.This has long been true in areas that I know something about. It’s been true of right-wing economics forever. It’s long been the case that although there are plenty of conservative, competent economists, what the right-wing wanted, even pre-Trump, was creatures like Steve Moore or Larry Kudlow, people who had no idea actually how to do economic analysis, but were unimpeachably, unquestionably loyal because after all, they had no constituency to fall back on.So we have this mix of leader principle, Führerprinzip. Yes, I think we’re allowed to use the original German here. Information blackout at the top because nobody wants to tell the leader bad news. And incompetence as a general principle throughout the government. And if you want to understand how the Reflecting Pool happened, if you want to understand how we ended up with this hole in the ground, that was previously the east wing of the White House, all of this is fundamentally the same stuff and it’s true of lots of other areas of policy as well.Still, I guess most of us thought — I thought, mea culpa — that the military would be among the last places to be hit by this. That, first of all, it should be obvious even to people likeTrump and Hegseth that you don’t muck too much with the military, that you don’t destroy the one instrument you really have, and also that the military itself had, so I thought, a strong enough culture, was highly enough respected among the populace that the military would be able to stand up and say no. But it turns out that I was wrong. And so instead of being insulated from the craziness and incompetence, the military is actually possibly the most acute victim of everything that’s happening. At this point they might manage to start feeding the sailors and fix the toilets, though I wouldn’t put 100% odds on that. But the broader problem of really destroying one of the last real sources of U.S. strength, that is not going to go away. Instead, it’s going to be the same thing. And the misery will continue until morale improves. Have a great day. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Vanessa Williamson on Taxes and Democracy 15.08.2026 46minFor all my interviews and more, subscribe on YouTube.. . .TRANSCRIPT: Paul Krugman in Conversation with Vanessa Williamson(recorded 8/12/26)Paul Krugman: This week, I’m talking to Vanessa Williamson, senior fellow at the Brookings Institution and author of a fantastic short history of taxation called The Price of Democracy, which is, I’m pretty sure, an allusion to Oliver Wendell Holmes’ “the price of civilization,” but a very different take. And because I’m so interested these days in tax policy, I thought I could talk to Vanessa to get a sense of a lot of these issues where I am very much an amateur and she’s done the homework. So, hi!Vanessa Williamson: Hi. Thank you so much for having me.Krugman: So, yeah, let’s talk about the title of the book first, because obviously the famous Oliver Wendell Holmes quote, which I’ve seen in slightly different versions, was basically saying, you know, if you want police and roads and public order, then you need to have taxes to pay for it. But you’re making a much broader point there. Why don’t you explain why you say it’s the price of democracy?Williamson: Yeah. So I love the Oliver Wendell Holmes quote, that it’s the price of civilization. But as I was writing this book, which was just going to be a history of taxation in America, it struck me that taxation is really more than the price of civilization—it’s the price of democracy. And that’s because democracy isn’t just being able to vote; it’s people having the power to actually make change to their government. And if the government doesn’t have enough money to act, then, even if you can vote, it’s inconsequential.Historically, this is a very deep story. Taxation and representation really do develop together. This goes back all the way to 1215 with the Magna Carta, when King John had been taxing at a higher level, and the barons demanded that if there were going to be extraordinary taxation, the king had to get the general consent of the realm.Krugman: Right.Williamson: And that was a very early iteration—an attempt to create what eventually became Parliament. So the very origins of representation in our historical tradition are really about taxation, because what you find is that when rulers want to tax, they become dependent on the taxpayers. And it builds a connection between the ruler and the ruled, and it gives the taxpayers power.I think commonly the story you hear in this anti-tax mythology that’s around is you’d imagine the taxpayers use that power to avoid taxation. The opposite is true: when representation develops, taxes go up because, of course, the taxpayers can now have a say in what the government is doing. So taxation and representation developed together historically, and they developed together cross-nationally. The freest countries today are high-tax countries.Krugman: That would be, above all, the sort of Nordic countries that are very high-tax?Williamson: Sure, but it’s true across the board. Even highly developed economies that are authoritarian have lower taxes than you would expect given their level of development. And that’s because authoritarians are simply not very good at raising taxes. They much prefer other forms of revenue, whether that’s a gold mine, the spoils of war, or fees and fines that they can apply to their political opponents. There are just other mechanisms that do not make them dependent on the rank-and-file people of their country.Krugman: Okay. And I want to come back to the high-tax countries in a minute. But one point that you make at several points in the course of the book is that the idea that taxes are okay is very much a challenge to wealthy people saying, “Well, my wealth is mine, and nobody has the right to take some of it.” And there’s a statement of principle that says, “Well, okay, but you too are subject to the laws of the republic and must pay.” Right? That seems to be a pretty big part of the story.Williamson: Yeah. There’s this long-standing tension, and it’s not all wealthy people or all the elites at any time in our history, but there are often some who are very, very wealthy. Fundamentally, they don’t like to see themselves as citizens, right? They like to see themselves as masters. The first group of people who felt this way, of course, were the slave owners who were desperately opposed to taxation. The anti-tax components of our Constitution were all put there as part of a compromise with slavery, right?Krugman: That’s a good point.Williamson: Yeah, the slaveholder class was afraid of mass democracy, even if only of propertied white men. So we get the Three-Fifths Clause. And they were specifically afraid that if every propertied white man could vote, what you would end up with is abolition by taxation—that we would tax slavery out of existence. And so that’s why you see these anti-tax measures in the Constitution.It happens again in the Gilded Age. You see Rockefeller claiming that high graduated taxation is the most fundamental threat posed by democracy. You see efforts to roll back suffrage rights during that period, even in Northern cities. So it’s a very long-standing fight between the mass public and the kind of things democratic governments usually want to do—roads, schools, and things of that sort—and a fraction of the elite who are willing to accept democracy as long as that democracy is too poor to threaten their power.Krugman: Wow. Okay. I’ll come back to the history shortly. One thing that I probably don’t talk about enough when writing about these things, but it’s something I certainly always taught when teaching a class on the economics of the welfare state, is that the high-tax, generous welfare state countries don’t have highly progressive tax systems. The state of the US debate always seems to be about, “Shall we raise taxes on the wealthy?”, which is an important concern. But places like Denmark or Sweden or, just in general, European welfare states, have high taxes sort of on everybody.Williamson: Yeah. That’s exactly right. I mean, that’s also how we pay for Social Security and Medicare. Big social safety net programs are typically funded by broad-based taxes.Krugman: Right.Williamson: I think it’s really important to remember all the things that taxes do. We really focus on the redistribution part. And it’s so important, absolutely, especially now with the incredible consolidation of wealth in this country. We focus on the straightforward redistribution part of the top rates, that kind of thing, or whether we should have a wealth tax. That’s important, you’re exactly right. But at the same time, we just need a lot of revenue. Traditionally, and in terms of long-term sustainability, that’s something that we fund by taxing everybody. But that’s part of citizenship.One of the things that is part of that anti-tax mythos that you hear all the time—people are under the impression that Americans hate paying taxes. It’s just not true. People are quite proud to pay taxes, and they’re very willing to pay taxes for things they think are valuable—things like Social Security and Medicare. So I think the fact that we’ve shied away from asking people to support their government by paying taxes at a federal level has really weakened the civic rhetoric of this country. I think it’s left us in a terrible position. If we can’t convince people that their government is worth paying for, how can we convince them that democracy is valuable?Krugman: Yeah, indeed. There are several episodes that I actually was ill-informed about. I kind of knew the numbers, but not at all the political history. There was this period, basically under the New Deal and through World War II, when the idea of broad-based taxes—that lots of people pay into social insurance programs, but also a broad-based income tax—really became established. That came as kind of a surprise, that people were willing to accept it, right?Williamson: Yeah. Before World War II, the income tax was what was called a class tax. It was paid only by the very wealthy. And the country relied far more heavily on tariffs. By the way, the tariffs chapter of my book is not what I expected as I was writing it to be—as relevant as it ended up being. But anyway, most people contributed to the federal government through the higher prices that resulted from tariffs, and the income tax was a tax on the very wealthy.Well, World War II comes along. We’ve got to pay for that. We need a ton of money, and they decide to go with an income tax. Now, we’re talking about a time when people didn’t have pocket calculators. A lot of people hadn’t been to high school. And suddenly they’re going to have to fill out a paper form and pay their taxes. And it’s not going to be withheld in the first years.So, there was a lot of fear in the Treasury Department: Could Americans do it? There were these incredible campaigns to let people know about the income tax and to help them pay. There was a song by Irving Berlin called “I Paid My Income Tax Today.” There were Donald Duck cartoons that played before movies. Donald Duck figures out how to fill out his taxes in the cartoon.So it was this huge effort, and in the end, it worked, right? Americans paid their taxes. We paid a much larger fraction of the bill for World War II than we otherwise could have. What’s especially amazing is how positively people felt about those taxes. They were voluntary contributions to the Treasury, made out to Uncle Sam. Polls suggested that 90% of Americans thought it was fair, because they saw it as a worthwhile thing to support the United States.Krugman: I guess the big increases in taxation have always come around wars, right? World War I is really where the income tax comes in, even for the wealthy, and then World War II comes in. But that’s a complete change in attitude. I don’t know if you remember after 9/11, when Tom DeLay, the House Majority Whip, said that “nothing is more important in a time of war than cutting taxes.”Williamson: Yeah. Extraordinary. It was the first time we fought a major war in this country without raising taxes. I think it speaks to the decline of accountability, that we stopped having that connection between the decisions of our policymakers and the costs.Krugman: We used to say that America was kind of special, at least compared with a number of other advanced countries, in the fact that we were so successful in getting people to pay income tax, that there was a lot less cheating. I don’t know if you touched on it in the book—I don’t remember—but is that something that you think is explained by the history or by contingency, or is that something about the American character, at least what we used to be like as a country?Williamson: That’s certainly an open question. But yes, American “tax morale” has always been high. That’s the jargon-y term for willingness to pay taxes. And that’s partly, I think, part of our civic culture. People see taxpaying as patriotic. If you ask Americans, “Is it every American’s civic duty to pay their fair share of taxes?”, you get over 90% of Americans agreeing, sometimes as high as 95%. I actually looked for poll data that showed equivalent levels of consensus. You have to ask things like, “Is Elvis alive?” or “Did we really land on the moon?”—just really out-there stuff. This is a shared belief.The first time President Trump, in his campaign against Hillary Clinton, talked about not paying taxes being “smart,” this was a huge change of rhetoric. If you recall Mitt Romney saying he’d always paid 13% or 14% in income taxes, this was a huge change in rhetoric, and it didn’t shift American attitudes. Americans did not suddenly come to see cheating on your taxes as acceptable. They see it as wrong.Krugman: One of the points you make along the way is that the public’s attitudes about taxes really haven’t changed that much over the years. I think the line used was that since the 1980s, the policy and the politics of taxes have changed, but Americans’ own attitudes have really not. Do you want to enlarge on that a bit—what you mean by that?Williamson: Yeah. Clearly, we live in a startlingly anti-tax time. One of the two major parties sort of sees taxation as fundamentally bad and sees taxes as something that should always go down, at least for the wealthy. That is a historical oddity. In the mid-20th century, neither political party saw taxation as a particularly major issue. It was important, but it was technical. It wasn’t a major part of either party’s platform. That changes in the period after the civil rights movement, where again you see the rise of the kind of anti-tax rhetoric that is fundamentally a kind of anti-democratic rhetoric, and that grew more and more extreme over the following decades. That’s sort of where we are today.The strange thing about that is, as our politics have become more extreme in so many ways, the politics of taxation have become more extreme, while the underlying views of Americans have been markedly stable. I think that speaks to the decline of the quality of our democracy, right? Because what happened was the politics became untethered from public views. Most Americans say that you have a responsibility to pay your fair share of taxes. Most Americans say that paying taxes is patriotic. If you ask people what their top concerns are about the tax system, their top two concerns for literally decades have been that corporations and the wealthy are not paying their share. The third is the complexity of the tax code. Somewhere below that falls the amount they personally pay.On this issue and on many others, frankly—you see it on things like gun control or the minimum wage, for example—the attitudes of most people are simply not a good predictor of our politics. I think that speaks to a real erosion of our democracy.Krugman: So when you say after the civil rights movement, there are two interpretations. I think there’s some of both in your book, The Price of Democracy. One is people feeling, “My money is going to support the bums on welfare,” because there was a huge expansion in AFDC (”Aid to Families with Dependent Children”), which is the classic rap on welfare, although it’s never really all that much money. But it’s a big expansion in the visible support for nonwhite people. Is it “my tax dollars are going to pay for that,” or how much of it is just the empowerment of conservative politics, to put it mildly, because of the backlash?Williamson: Yeah, I think both are happening at once. At the same time, you see welfare programs that had previously been available almost exclusively to white Americans suddenly become more available to Black Americans. You see, obviously, growing Black political power after the Voting Rights Act. So there’s a racial resentment and a backlash to that, and the origins of the “welfare queen” rhetoric. We’ve all heard the story. So that’s happening.At the same time, you start to see the divide between the very wealthy and the rest of us. The compression of incomes and the economic spectrum that had typified the mid-20th century starts to break down, and you see the decline of union power and the rise of business power. All of these things are pushing in the same direction towards an increasingly radical anti-tax politics on the right.Krugman: There’s a moment—an episode that really looms quite large in The Price of Democracy that I was really kind of unaware of—which is the 1978 change in taxes. This is pre-Reagan, although obviously some of the things that gave rise to Reaganism are very much in the air, but this is under Carter. Why don’t you tell us about what happened in ‘78? I thought that was a really remarkable story.Williamson: Yeah. You have to make a choice about where you are going to say the turning point was. You can claim it was the Reagan era, or you can say all these other things. I settled on 1978 because three things happened that year that I think were really significant, and again showed what the conservative alliance against taxation would look like. A bunch of different forces were brought together.First of all, you see a bill pass that is an enormous rollback on taxes for the wealthy, something that The New York Times at the time described as sort of incomprehensible in terms of our politics. Before that, it had been assumed that Americans liked raising taxes on the rich, and it would be very hard to do a tax cut that just helped the rich. But the new corporate interests found a way to do that, so you see this big rollback in taxes for corporations and the wealthy.At the same time, there’s an attack on the IRS that is the first of what would become a recurring problem for the agency. That is to say, some issue in tax enforcement gets blown up in the conservative media and makes the IRS into a whipping boy for anti-tax interests. In this case, what had happened was the IRS was obligated by law to figure out how to remove the tax-exempt status for segregation academies—the whites-only schools that opened in the South as white families fled integrated schooling. Those schools were segregated; they discriminated on the basis of race and therefore did not qualify for a tax exemption. The court so determined. So now the IRS has to figure out what is a segregation academy and how to go about removing their tax exemption.This was really hard to do because lots of schools opened in that period, and lots of schools were segregated. There was also a move to church schooling and evangelicalism in the same period, so the IRS was trying to sort through this. After several efforts to remove the tax exemption from the most obvious segregation academies, they issued a new set of rules. It became a trigger on the far right about how the IRS is coming for our tax exemptions, leading to congressional hearings and all sorts of fodder.This is widely agreed to have been a key precursor to the development of the Moral Majority, because conservatives had been trying to get evangelicals on board with the conservative movement for ages, but evangelicals didn’t want to participate in politics. This issue brought them into politics in a new way. There’s an amazing quote suggesting that even abortion couldn’t get evangelicals into politics, but coming for their school’s tax exemption did. So that happens at the same time.The third thing that happens in that same year is Proposition 13, the property tax cap in California. Property tax caps have a long and sordid history in America. They were invented in the Redeemer era that followed radical Reconstruction, as white supremacists came back to power. One of the ways they disenfranchised poor whites and Black Americans was by putting in place constitutional tax caps so that even if they managed to lose an election—if more poor Black or white people managed to vote—they still wouldn’t have the power to raise taxes on the rich. Now suddenly that same idea, which had been prevalent across the South a hundred years earlier, becomes a force in California. It’s very much part of the civil rights era backlash. They put in place a stringent property tax cap that applies largely to this day, which undermined public education funding in the state for decades to come.Krugman: Yeah. I lived in California in the mid-’90s and was always struck by Prop 13. We had newly purchased a house there, and we were probably paying five times the taxes of some people a little ways down the road. It was a remarkable thing for people who stayed in their houses—basically older white people who already owned their houses got a tremendous tax advantage from that. It was really something.So how did those 1978 tax cuts come about?Williamson: There’s a really fascinating movement on the right that leads into this moment, and it’s a series of corporate breaks. What leads into it, fascinatingly, is that in the Kennedy era, they were also trying to cut taxes. The economy was booming, and people’s taxes went up automatically—not rates, but brackets.Krugman: Right, bracket creep.Williamson: Bracket creep. So they had more money than they needed. When Kennedy wanted to assemble business interests to cut taxes for businesses, he couldn’t find any groups to act as the grassroots mobilizers of this. Over the coming decades—and exactly at the time that union power was in decline—they started to actually develop these business interests.There were moves to make what now sounds like completely standard rhetoric, but at the time was very strange: this new rhetoric about the possibility that these taxes were stifling innovation and entrepreneurship. That’s where they came in with these corporate tax breaks, to basically put in massively upward redistributive tax breaks. What they did was build grassroots organizations for business that today seem run-of-the-mill, but at the time were completely novel.For example, lobbyists in Washington would bring in local business leaders from all the districts for “fly-ins” so representatives would hear from their own constituents on these business issues. That was a real development in terms of lobbying prowess, and it paid off tremendously.Krugman: And so, in ‘78—and actually until Newt Gingrich comes along—you still had Democrats controlling the House of Representatives. This was not a Trump-era Congress, and it was a Democratic president. The public didn’t support tax breaks for the rich. I think public opinion would have been pretty populist in that sense. So what moved the votes? Why was Congress doing this? How did that influence work?Williamson: At the end of the day, the fact is that mass public opinion isn’t what causes politics to happen. Politics is not a public opinion poll; it’s the mobilization of organized interests through a party system. So you shouldn’t expect things that most people believe to automatically become law. That’s just not how it’s done; you have to have organized interests. It’s a collective action problem, fundamentally.That’s the underlying thing. But as the economy divides and as you have this concentration of wealth at the top, it’s self-reinforcing. As the rich get richer, they have more power, because money is power, and they start to invest very heavily in having greater political power. There was a lot of concern about the Nader era and all the regulatory things that were happening in the early ‘70s, which really helped to bring business power to bear—Krugman: The Nader era meaning when business really started to say it needs to stand up and throw its weight around?Williamson: Yeah, exactly. You saw what I would deem a great deal of progress on things like environmental protection and the regulation of consumer goods. These were some of the successes of that era, including clean air and clean water in the early 1970s. For a lot of more conservative-leaning business leaders, these were seen as encroachments on their capacity to be profitable, and so that helped convince them to devote themselves to politics. As they succeeded, of course, they became wealthier.This is exactly the same thing that happens with the tax code. As the top rates are rolled back, you see more and more loopholes for corporations to avoid paying taxes. As the IRS becomes underfunded so that they aren’t in a place to actually enforce the tax code for wealthy people, all of those things are reinforcing, because a substantial portion of the inequality that we’ve seen over recent decades can be attributed to the decline of top rates. So it’s a really negative, reinforcing cycle.Krugman: When I started, loosely speaking, doing the math, I was actually shocked—particularly if we’re talking about the very, very top—how much the change is actually driven by cuts in tax rates. As economists, we like to talk about technology, competition, and all of that, but actually taxes are a very large part of the story.Williamson: It’s really the ‘70s where this starts to happen. It is all, in a sense, mechanical. The money that you didn’t have to pay in taxes, now you have, and it will accumulate more over time. It also has pre-distribution effects. When, for example, a CEO had $0.90 out of every additional dollar they were going to get paid going to the government—which was true in the mid-20th century—the board of directors didn’t have a great incentive to raise their pay unless they really had done something to deserve it.There’s research on this, as you well know, but as tax rates go down, it becomes easier—cheaper, basically—to overpay executives. So it feeds in both ways: afterwards, you have these ballooning paychecks and they get to keep more of that money, but it also gives an incentive to balloon paychecks in the first place when those very high salaries are undertaxed.Krugman: Yeah. This is a long-standing thing. The committees that decide on the CEO’s pay have always been basically appointed by the CEO. But why did that translate into 30 times the average worker’s salary in the ‘60s and 300 times now? Part of the answer, you’re saying, is that it wasn’t worth pissing off people that much—sorry to use the technical term—when the CEO didn’t really get to keep the money anyway. Now that he can, they do it.Williamson: Exactly.Krugman: You get this first wave of big, top-end tax cuts under Reagan, but fairly quickly, we get people agitating about the budget deficit. This is also when the budget deficit becomes significant for the first time since World War II, and there’s a feeling we need to cut back—the beginnings of austerity. Why isn’t there more of a backlash against these tax cuts? Why didn’t that happen?Williamson: I think there are two things going on. First, there’s just the very effective lobbying techniques that business uses. They’re very powerful. There’s all kinds of political science research to suggest that legislators are more responsive to donors than to constituents, and more responsive to organized interests. They misperceive their own constituents again and again. It’s more true on the right, but it’s true on the Democratic side as well. Legislators misperceive their constituents as more conservative than they are. Some of that’s about who they talk to, and some of it’s about the media environment they live in.There’s this persistent problem in the background. Thinking back to that capital gains cut in 1978, there’s just this new playbook that becomes part of our politics. It’s hard for us to even imagine now that this was ever new, but I think that it really does speak to the moment we live in.Now, you’re asking about why it is that there hasn’t been a backlash. One important aspect of that is that for many, many years—and we are now testing the limits of this—these tax cuts were not “paid for.”Krugman: Right, right.Williamson: We paid for enormous wars with debt, and we paid for enormous tax cuts at the top with debt, so there was not a tradeoff that the American people would see right away. If you look at the George W. Bush era, this was a very conscious strategy. In principle, you could have taken the surpluses of that era and used them to shore up Social Security or do any of a number of other things. If you look at memos within the Bush administration, it was very clearly stated that in going to the voters to cut taxes in this very regressive way, they had to say there were no tradeoffs at all. Fiscally, barring the costs of debt and interest, there were no immediate consequences.So there’s a real decline in the signals that would have informed Americans more about the choices that were being made in their names. Right now, the most recent Trump tax cut is an exception to that rule. Where the big tax cuts going back to Reagan were off the books, this time they’ve done quite a lot of retrenchment of major social safety net programs. They delayed that, but it is coming now as we speak, and I think it’s a question of whether that will be more evident to people.One reason they were willing to take that step in the most recent Trump tax cuts—to also make it the most regressive budget legislation in history by simultaneously cutting taxes at the top and cutting benefits for poor people—is another indication that popularity is no longer a concern. Frankly, you want popularity to be a concern for politicians in a democracy. The budget legislation is a good indication that doing things that are popular in order to get re-elected by a majority of the voters is not the primary political strategy of the Republican Party anymore.Krugman: Just for listeners—the tradeoffs we’re talking about now are that the “One Big Beautiful Bill” includes big tax cuts very much for people at the top, offset only partially by really savage cuts to means-tested, poverty-oriented programs like food stamps and Medicaid. I guess the question is: Is this a kind of cynical calculation that most Americans won’t care about that, or just a calculation that it doesn’t matter what Americans think?Williamson: There are the immediate effects that will happen for the people who are affected, but this will have a huge impact on the economy. Medicaid supports health access for poor people and supports hospitals in rural areas. The ramifications are likely to be enormous and widely felt beyond the technical beneficiaries, for sure.Krugman: Same with food stamps, of course. The extent to which the places that voted most strongly for our current government are exactly the places where you are going to lose a critical mass of purchasing power and a critical mass of patients who can afford to pay their bills at hospitals. People are not going to lose hospitals anywhere close to where they live in New York City, but they very much could in West Virginia.Williamson: Yeah.Krugman: To just come back a bit: We’ve been in this tax-cutting mode since the late 1970s, but there was one range of substantial tax increases during the ‘80s, which was the increase in FICA, the increase in payroll payments. This kind of gets at your thesis. You have an extended section in the book about how we came to pay for Social Security and then later Medicare with payroll taxes. That’s a story I think people should know, because it comes up now a lot as we talk about what we can do between Social Security funding and general healthcare reform. How did that happen? Because this is a regressive tax. It’s $170,000 or thereabouts, just the maximum. It’s a flat tax up to that level and nothing above.Williamson: And it’s a tax on wages, not wealth, so it’s not taxing the income from wealth. The Social Security tax is a regressive tax that hits most people pretty hard. In fact, it’s the biggest federal tax for most households.Krugman: So why did FDR make this choice?Williamson: Well, he’s coming into office in the throes of the Great Depression, and they’re doing a whole bunch of emergency rescue measures to try and stabilize the economy. What he does not want is his pension plan to be seen as a temporary measure; he wants it to last forever. He wants this to be something that cannot be retrenched, and he wants to distinguish it from these other emergency measures.There was a lot of debate within the administration about this. Plenty of people within the FDR administration said, “No, this is not the way to fund this. We need to fund it differently.” FDR was not always a policy wonk, frankly. But on this point he was extremely adamant, both because he wanted to distinguish Social Security from emergency anti-poverty measures and because he was always thinking about the politics of how you tell a story about policy. He knew that he could tell people they were making a contribution, here was what they were going to get someday, and here was how it was going to work. He knew that he could tell the American people to contribute to a fund like this, and he was right.He famously said that the payroll tax contributions were not economics, but politics—to make sure that no politician can ever eliminate his Social Security program. To a substantial degree, that political logic was proven correct. The program not only survived, but grew after the Depression.It’s funny—business interests at the time tried to mobilize against it. They were really trying to mobilize against his “attack the rich” rhetoric. In the following elections, they tried to go after him on Social Security because it was a $1 tax coming out of people’s paychecks. Business interests put propaganda on people’s pay stub envelopes saying, “If you re-elect Roosevelt, you are condemned to this tax increase, and who knows whether you’ll ever get benefits?” A union organizer famously said, “Why didn’t they put propaganda in your pay stubs last time? There were no pay stubs!” It was FDR who was getting us out of the Depression.That was how FDR saw the fight. He was a political maneuverer, unparalleled perhaps in our history, and that was 100% the playbook they used for Medicare. They knew full well what to do to make a program that would survive.Krugman: Now, it’s interesting. I don’t know if people realize this, but it’s only Medicare Part A, the hospital insurance part, that is payroll, and the rest comes out of general revenue. But in some ways, the aura of this separately funded program extends to the whole thing, even though a lot of it is not paid for by that bit on your pay stub.Williamson: The downside, in terms of the price of democracy, is that people don’t necessarily think of these as government programs. People know about their Social Security taxes, and they don’t think it’s going into a bank account for themselves. Sometimes there’s worry about that, but people know that it’s going into a general fund and paying out today. They have that much of a sense about it, even if they don’t always have a full sense of the totals.The flip side of putting this aura around these particular programs is: Does it implicitly denigrate other programs? I think there’s a case to be made for that. Over here are Social Security and Medicare—the contributor-funded, worthy programs—and over there are other welfare programs that are somehow seen as not as deserving or worthwhile. That’s a real risk of the approach.Krugman: Yeah, okay. I’m always a little surprised looking at the record of the Obama years to see how much, particularly at high income levels, he did manage to raise taxes. CBO numbers say that the effective tax rate on the top 1% under Obama rose to pretty close to where it was pre-Reagan. But it was not going to be enough if we really want to have the kind of society that a reasonable, center-left person wants. So what are the prospects? Are we still living in this era of tax phobia? I think I’m dreading your answer here.Williamson: Well, I think one thing that’s happened is that the mask really came off on this. For many decades, being anti-tax was a kind of polite fiction, a rhetoric you could use to attack the idea that a democratically elected government could do good for people. Rather than directly attacking democracy, conservatives attacked taxation. This is a replication of precisely the rhetoric that followed the Reconstruction period. The Redeemers, the white supremacists, came back to power through violence and intimidation, and organized themselves as taxpayers using rhetoric that looks very familiar to anyone who knows about Reagan’s “welfare queen”—that Reconstruction governments were full of corrupt, untrustworthy chiselers, and the poor, burdened, implicitly white taxpayers were rising up against that. It’s very similar to the rhetoric you see in the aftermath of the second Reconstruction, the civil rights movement in our own time.To some degree, the dog-whistle aspect of anti-tax rhetoric has fallen by the wayside as the Republican Party has moved to an explicitly anti-democratic stance, like failing to accept election results. So the tax rhetoric is falling by the wayside, and the stakes are a lot clearer now.The problem, to my mind, is what we have not seen. You’ve seen some real movement on the center-to-left side on all kinds of things—rhetorical progress—but what remains missing is a willingness on the part of center-to-left politicians at a national level to tell people that their government is worth paying for. At a state level they have to do this, but nationally, the unanswered disparagement of government—which has been a consistent part of our politics for my entire lifetime—paved the way for things like DOGE and the massive destruction we’ve seen in the last two years.To some degree, I think that destruction has made the value of government more evident. It has brought things like the role of the CDC, or the fact that we had people watching our nuclear silos, to the forefront of our minds. But what I have not seen is politicians on the center-to-left talk seriously about the idea that the United States government is worth being paid for by all of us.And you see that with the plans by Senator Booker or Van Hollen. Once you’re proposing very large tax cuts for middle-class and upper-middle-class people to the tune of hundreds of billions of dollars, we will not have those measures in place to do the rebuilding that is so absolutely essential.Krugman: Even someone like Mayor Mamdani in New York City saying we’re going to tax the lavish pied-à-terres held by non-residents who have $100 million apartments—which is fine—shows he’s still kind of afraid to do a Willie Sutton and go where the money is.Williamson: Yeah. To me, it’s hard because people want you to say it has to be one or the other. They want you to say either you want progressive rates at the very top—and I think there’s no way around that as an approach to reducing wealth inequality in this country.I’ll tell you a story: Tom Paine, the guy who wrote Common Sense and famously said that the United States did not need a king, wrote The Rights of Man a few years later in defense of the French Revolution. In it, he includes a tax plan because he was worried about extreme wealth corrupting elections. It was a tax plan applied to income from wealth, and the top rate proposed by Thomas Paine in 1791 was 100%.He imagined that there should be a limit to wealth—explicitly saying “any level that you would possibly need to support a family, any amount that you could conceivably earn through your own effort.” But he thought a level of consolidation like the wealth of the lords and earls in rural England endangered a republic. So there’s a very long tradition in American politics of very progressive tax plans, and that’s an important part of thinking about the future. At the same time, we need to think about revenue that will be available in perpetuity, and come back to that old idea that this is our government and that’s why we pay for it.Krugman: Okay. So how long till we get a value-added tax in America?Williamson: I’m right there with you, yeah. I think it’s about seven economists behind the banner.Krugman: Okay. Well, this was great. The historical perspective is more and more important; you can’t understand where we are without looking back, and then looking forward with a little bit of trepidation, but maybe a bit of hope.Thanks for speaking with me today. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 What Malta Tells Us About Oligarchy 10.08.2026 7minLink to primer here.TranscriptIf you want to understand how we went so far down the road towards oligarchy, Malta is a good place to look. Hi, Paul Krugman, doing a video today.Yesterday, my weekly primer was another episode in the series about the rise of oligarchy and the policies that have led it to where it is. And this time, I focused on the role of a huge shift in taxation that has taken place over the past several decades, away from taxing capital and towards taxing labor. Half of that is a very large decline in the effective rate at which profits are taxed. Now that decline has taken place partly via a reduction in headline tax rates, but to a large extent, from expanding loopholes — of which one of the most important is the ability of corporations to use accounting tricks to shift their reported profits into low tax jurisdictions, which is where Malta comes in. On paper, according to the official numbers, Malta plays a remarkable role in the world economy. It’s a huge investment destination: There are only a bit over 500,000 people on the island. But it has attracted more than $500 billion in foreign direct investment. At the same time, Maltese companies have invested about the same amount overseas. That’s about a million dollars per man, woman, and child in each direction. Of course, it’s all fake. What we’re actually seeing is a proliferation of shell companies that are used by companies elsewhere as ways to launder, transfer their profits so that they pop up in Malta, which has a basically zero tax rate on corporate profits. This is a combination of tax avoidance and tax evasion. Avoidance is when it’slegal, although it probably shouldn’t be. Evasion is when it isn’t. There’s some of both going on in Malta. There’s quitea lot of actual money laundering and sheer criminal activity. Famously, an investigative journalist from the island who looked into it was blown up by a car bomb. But mostly it is probably, at least marginally, within the, or arguably within the outer limits of the law. So Crocs has a two-person office in Malta. And according to its books, basically all of its global profits come from that two-person operation in Malta. The New York Times had a very good report about all of this, which somehow I had not seen before writing the primer. What is going on here? Well, the mechanics are quite simple. The real question is why this is allowed to persist. Tax avoidance or evasion, but profit shifting to avoid taxation, is a big issue. Estimates for the United States are that we lose probably north of $100 billion a year to companies finding ways to make their profits appear someplace else. If you want a sense of perspective, that’s roughly the entire budget of the food stamp program. It’s roughly the entire amount that Medicaid spends on health care for children. These are programs that the administration falsely insists are full of fraud, but international profit shifting is fundamentally tax fraud, although it may be legal. Now, Malta is a sovereign nation, but there really wouldn’t be any problem if the major democratic nations said this must stop. Malta is in fact part of the European Union. The European Union could clearly stop it. It has not. Now, Europe is not totally hopeless. They actually have to some extent reined in the tax shelter status of Ireland, although it’s still there, but it’s weaker than it was. They have made moves toward a general international agreement that says that corporate tax rates must not be below 15% anywhere. It’s not really in effect, but they’ve moved in that direction. But Europe is characteristically weak in implementation. And let’s face it, there’s a fair bit of corruption there as well. The United States, well, the United States was part of the project to limit at least extreme tax havens. To impose that minimum 15% corporate tax rate. But Donald Trump has withdrawn from the agreement.It’s very clear that the United States government, as currently constituted, is not interested in cracking down on tax avoidance and tax evasion. In fact, the President of the United States and his lackeys are very much clearly on the side of tax cheats.Now, I don’t want to say that Malta is the whole story. It’s obviously just a piece, although it is pretty extraordinary. We’re taking about basically a million dollars of corporate profits being laundered for each inhabitant of this tiny island. But it’s an indication. It’s also an indication of what I’ve been calling the downward spiral of oligarchy. If we ask why is this outrage, this fundamental tax cheating permitted to continue, the answer is very clearly, it is the power of people with money who want to be able to avoid taxes. And their ability to avoid taxes leads them having even more money,which reinforces that power.So it’s going to take a really big effort to, you know, we really need to reverse this. And we need to do it, you know, not slowly because this is a cumulativeprocess. We are on a downward spiral here. Malta is slightly exotic, it’s a funny story, but it’s actually very much indicative of what’s going wrong for the United States. And a reminder that although we are definitely the bad guys here, theEuropeans aren’t such great guys either. But maybe they can be shamed. And maybe if we have a regime change here in the United States, we can finally be part of the effort.Have a great day.For all my interviews and more, subscribe on YouTube. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Talking With G. Elliott Morris About the Midterms 08.08.2026 44minFor all my interviews and more, subscribe on YouTube.. . .TRANSCRIPT: Paul Krugman in Conversation with G. Elliott Morris(recorded 8/6/26)Paul Krugman: I am returning for another of multiple conversations with G. Elliott Morris, whom I find the most informative polling and political data analyst out there. And for a couple of reasons: We just had the primary in Michigan, we have a lot of numbers, and the Strength in Numbers midterm model is up. So we have our first reads on best estimates of what’s going to happen. So there’s a lot I’d like to talk about.G. Elliott Morris: Hey, Paul. Yeah, let’s get real wonky on the forecasting. Good to be back.Krugman: Yeah, let’s start with the model. You have a first forecast, which is pretty encouraging for Democrats. But why don’t we talk about what the forecast says and then what might be issues to raise around it?Morris: Sure. The forecast, which people can find at fiftyplusone.news—which is sort of a sister publication to Strength in Numbers that I run with a couple of friends—is just a team effort, so we kind of have a different play sport than just a solo podcast. That forecast, as of recording (Thursday afternoon), says the Democrats have an 87 out of 100 chance to win control of the House. They need 218 seats; they have 215 right now, so it’s a pretty easy get. I can explain why. And that the Democrats have a 54 out of 100 chance to win control of the Senate. So pure toss-up territory there for the Senate. There, they need to win 51 seats; they currently have 47.Krugman: Now this is, of course, a map on the House that includes the extreme gerrymandering, all of the attempts to tilt it. And so you’re saying that despite that, the Democrats don’t have a lock, obviously. But I assume that without the gerrymandering, it would be even higher gains on the House.Morris: Yeah. I mean, without the gerrymandering, I would take close to 95 or 96% odds for them to take it. Our best guess is that the gerrymandering cost Democrats 5 or 6 seats in the House. So that combines a pretty good amount of gerrymandering in Texas—that cost them probably three seats there—and then 3 to 4 seats across the other Southern states. Tennessee is one; Louisiana, 1 or 2; Alabama, probably one there. Florida as well—a pretty big hit in Florida. And then, of course, it takes into account some gerrymandering back in the Democrats’ favor in California, and one lucky seat that they got a lucky break with in Utah with some court-mandated redistricting there. Democrats will take a seat from Utah for sure. So, yeah, I think that they’ll get 231 seats on average today, but that number should be close to 237 without the mid-decade cheating.Krugman: You’d said that they needed something like a four percentage point advantage in the popular vote.Morris: Yeah, we’ll be writing more about that. I think the number in the forecast now is close to three and a half. It’s a little more optimistic taking into account stuff like how candidate recruitment was really good for Democrats in some places. Their polling numbers and fundraising are looking really good in those competitive districts. So, you know, if the historical patterns are correct, Democrats gain some ground in the generic ballot, and the predictors are as reliable as they typically are in midterms, then it should be a pretty easy victory for them. We would predict a pretty easy, big House majority for them with 230 seats.Krugman: But just to talk about the Senate—so that’s a much heavier lift, right? I think I know why, but why don’t you give me your version of what it’s about?Morris: Yeah, well, in the Senate, Democrats currently control 47 seats. They need 51, so they have to find four seats to flip somewhere. The Democrats are very favored to win the seat in North Carolina. Former Governor Roy Cooper is running—a Democrat. He’s running against current Republican National Committee chair Michael Wheatley. And Roy Cooper is just kind of one of those politicians who has a good connection with his state and kind of can outperform those fundamental indicators in the state. So the typical voting pattern of the state is what I really mean there. So they will very likely win that seat—maybe an 85% chance we gave them.So they need three more. And Democrats are also defending a seat in Michigan, just for whatever that’s worth. So the other three seats the Democrats could get are Maine, Texas, Alaska, and Ohio. All four of those seats are toss-ups, leaning Democrat in Maine, although we lack a lot of data in Maine with the new nominee, the new Democrat nominee. So that’s really the territory. You could argue maybe Iowa looks potentially competitive based on early data, but it’s kind of thin. Georgia Democrats are looking to upset the incumbent Democrat, Jon Ossoff, but I don’t think they really stand a chance there.Krugman: Yeah. And the thing about the Senate, there’s two things about it structurally, right? First of all, only a third of the seats are up this year, so Democrats have to win a large percentage of the seats that are actually on the table—where they’re actually holding elections this year.Morris: Right.Krugman: And then the Senate gives Wyoming—whose population is basically the equivalent of a neighborhood in Brooklyn—and California the same number of senators. And that kind of works in Republicans’ favor, right?Morris: I mean, if you count them up, there are 6 or 7 competitive seats from the Republican side that Republicans currently hold. And as I mentioned, Democrats need to win four of those. So you’re looking at two-thirds or so of the competitive seats Democrats have to get to pick up the majority if they defend that seat in Michigan—which is not a certainty. I do think the polls are perhaps undercounting, underestimating the Democrats there, but I wouldn’t put money on that. That’s just kind of a hunch based on the polls and other seats.Krugman: Okay. But let’s talk about Michigan. So we had this extremely contentious primary. And, you know, Charlie Cook shows up in my feed saying Democratic chances of taking the Senate have just evaporated. And then I read you saying that it really doesn’t make a difference or not much of a difference that El-Sayed won. So let’s talk about this. There are interesting methodological differences.Morris: I guess the great Charlie Cook would have said that, yeah.Look, I think there’s a real lack of epistemic humility when it comes to Abdul El-Sayed’s chance of winning Michigan. There is a lot of conventional wisdom out there that, you know, let’s just say it: like a Muslim candidate cannot win the US Senate in Michigan, that Medicare for All and other progressive positions are going to drag him down. And frankly, a lot of this punditry comes from those center-left Democrats who should be in favor of those candidates winning. And so there is a sort of shooting-yourself-in-the-foot dynamic there as well. But if you actually look at the polling—and I wrote about this on Strength in Numbers—if you look at those polls pitting Abdul El-Sayed, the current nominee, against Mike Rogers, the Republican nominee, and then you compare them to how Haley Stevens would have done in those same horse-race matchup polls, the difference between the two Democratic candidates, or potential Democratic candidates, is statistically indistinguishable from zero. It is, on average, zero. Maybe it’s as big as three in either candidate’s direction. But if you’re Charlie Cook saying Democrats’ chances just evaporated, you are leaning heavily on some other priors or other punditry in saying that and not really the data.Krugman: So, there’s two aspects to this, one of which I take pretty strong statistical evidence from you and one of which is a kind of “don’t know,” but... One of them is saying El-Sayed is too far to the left, and you basically have said that that’s a dimension that exists in the minds of pundits, but not in the real world or not among voters.Morris: Yeah, there’s a strategist fallacy here as well. There’s an over-indexing on the perception of Abdul El-Sayed as some radical-left DSA candidate. For the record, he’s not even a member of the Democratic Socialists of America who have been winning so many seats. And there’s a default backlash to the idea that, you know, a more left-than-moderate Democrat could win in Michigan. There’s no similar skepticism, however, about the probability of a far-right Republican winning Michigan—Donald Trump in this case, who just won it. So clearly, this over-indexing on ideology from the pundit class, the strategist class, has, I think, pretty little bearing on the actual electoral outcomes.Krugman: Yeah. What I take a lot from you is that the idea of, “Well, Medicare for All, that’s kind of a left-wing policy, and people will be against it”—it’s not clear that the public even thinks about it as being a left-wing policy, or even that the public has a left-wing versus right-wing conception except sort of as a caricature vision. So...Morris: Yeah. A public option for healthcare, if you want to say it that way, polls very well. The 60–65% universal healthcare idea and expanding Medicaid polls at 75–80%. People want more of a government role in health insurance. I just saw a lot of the interviews with younger people in Michigan as well. And, you know, anecdotes are anecdotes, but still, most of the accounts from these young people about why they supported Abdul El-Sayed were healthcare-related—that they wanted some guarantee of health insurance.So I just think we all carry around a lot of biases in our heads about what’s possible politically. And that has changed a lot over the past decade with rising partisanship and a demand for change from Washington. Just one more statistic, and I’ll wrap up here: In our polling, 60% of people say that the political system needs major structural changes; to be torn down and rebuilt. That is similar to the DSA sentiment about how the economy’s not working, right? So you can imagine why the appeal would be there for the sort of anti-system candidates like Abdul El-Sayed.Krugman: I’ve always been shocked by polling by the likes of KFF that shows very, very strong public support for Medicaid, very comparable to Medicare. And I’ve always wondered how much of that is because people may not know the difference.Morris: I couldn’t tell you, but I think your instinct there is the right one. There is a lot of public support for government providing health insurance to people who need it. And then there’s a lot of definition about who needs it from the right, especially in campaigning against these benefits. I know you’ve written a lot about that.Krugman: Yeah, but it’s interesting. I’d like to say “the public loves Medicaid,” but I’m not entirely sure that people don’t think it’s the same thing as Medicare or, you know, don’t know that one of them is means-tested. But the only thing that gives me pause is I just worry about the idea, “I would have no qualms at all if someone had El-Sayed’s exact same positions, but was named John Smith.”Morris: Yeah.Krugman: And no one seems to want to talk about how...Morris: Yeah, they don’t want to talk about the Muhammad factor of it all. And that seems really relevant to our priors in American politics today. I mean, how many exact same articles were written about how Barack Obama was too far left to become president of the United States? And Barack Obama was not a far-left senator. It should be laughable in hindsight. If he wins and he wins by 5 or 6 points, I think maybe we’ll say a lot of this was all for naught. On the other hand, if he loses, people will point to his ethnicity and name as a reason, and as something Democrats should avoid in the future. I’m sure of that.Krugman: Yeah. You know, Obama was, in fact, very centrist, very restrained. I sometimes worried that because of his name, he felt that he had to be and that he was too cautious on some of the policy stuff.Morris: Well, I don’t know the guy.Krugman: Well, I did, though not a lot. But there were some meetings with economists wanting him to take a harder line on Wall Street, and bankers telling him he mustn’t. And the bankers won all the arguments.Morris: What else is new?Krugman: But yeah. And so you actually said, basically, that Stevens vs. El-Sayed makes no difference at all to your probability of the Senate.Morris: No. And that’s the other thing: If you are really splitting hairs about the probability of winning Michigan, then there is an on-average effect of Abdul El-Sayed winning. It’s on the order of 4 or 5 percentage points. So to spell that out, our current forecast, including Abdul El-Sayed, is for Democrats having a 64 or 65% chance of winning the seat in Michigan. Whereas if you replace the quantitative indicators for El-Sayed, such as the polls and some other factors, with those that you would have in a hypothetical election with Stevens, Stevens has a 69% chance of winning. So there is a five-point difference there.If, however, what you care about is the chance of controlling the Senate, this is negligible; it is less than one percentage point. Democrats in our forecast have a 55% chance of winning the chamber today. They had a 55% chance of winning the chamber on Monday [before the primary]. And, frankly, according to the quantitative data that we have right now, it just doesn’t matter who that nominee is. But maybe that’ll change, right? Democrats have gotten in some trouble recently nominating candidates who have not been vetted before, not run for office. We don’t know what will happen in the future. But as of right now, it doesn’t seem to matter who that nominee is in Michigan.Krugman: Okay. So the backdrop to all of this is the unpopularity of Trump and his policies. That’s what makes this a reality. I think that there’s been a noticeable further downleg in Trump’s approval. Is that right?Morris: Yeah.Krugman: Is that basically post-Iran, or is there more going on than that?Morris: Well, the war in Iran definitely eroded support for Trump at the beginning, which I guess was March 1st of this year, where in our average, we had him at a 37% approval rating. Then over the next month, his approval rating fell to the low 36’s. And on the other side, his disapproval rating increased from 55–56% up to 60%. So there was some consolidation, especially in opposition to Trump among those sort of, you know, maybe Trump-skeptical or unsure voters. There has been further degradation since then. I mean, Donald Trump’s approval rating was almost in the 35s a couple of days ago, and his disapproval rating was approaching 62%. It’s since bounced around a little; there’s some noise in the polling data, so the average bounces around a little. But his approval rating is at an all-time low—net of something like -25 or -24.But what we do is we compare Trump’s approval rating on the issues to whatever Donald Trump’s overall approval rating is on the day the issue surveys are released. And then as Trump’s overall approval rating changes, we predict what an issue approval rating would be given, you know, whatever his approval rating is on that day in the average. So what we’re actually doing is looking at the difference between his issue approval rating on something like prices and his overall rating, and then predicting that, until there’s new issue approval rating data. I mean, at this point, there is issue approval rating data like every couple of days; pollsters have started asking for it. Maybe it seems to get them a lot of attention to publish a really bad number on inflation, for example. So there’s plenty of data, at least on the big issues.Krugman: Okay, but there’s a kind of ranking of issues which are really bad for Trump and issues which are—at this point, I guess there are none that are really good, but there are degrees of badness. I think anybody can look at your site or at fiftyplusone.news, but tell me what’s kind of worst and best, and what do we know about those.Morris: Yeah, the “degrees of badness” is a fun way of putting it. You know, I was interviewed by WNYC a couple of hours ago so the numbers are fresh in my head. Trump’s approval rating is somewhere between what Richard Nixon’s was literally the week that he resigned the presidency in disgrace (around 32%) and George W. Bush’s in 2006, the middle of the Iraq War—I think just after the Abu Ghraib scandal—where he was around 38%. So Donald Trump’s ratings today, even with the amount of political polarization we have and the amount of partisan sorting that we’ve had over the past 20 years, has, you know, the approval rating of some of the darkest periods of American history in terms of the evaluations of the president. So it is very bad. I mean, despite what he wants to say on social media about having the best polls ever, he has an almost worst-ever approval rating for any point in a presidency.Krugman: By the way, the political polarization thing is something not everybody will understand. I mean, what you’re saying is basically that when Richard Nixon was president, people could actually be persuaded—Republicans could actually be persuaded that a Republican president might be bad. And, well, we were thinking that we weren’t in that kind of world anymore. But you’re saying that despite that, we’re kind of getting into there?Morris: Yeah. The approval rating and Gallup’s tracking for the out-party of the president—so the other party than the president’s party, in this case for Nixon, the Democrats—used to be able to get up as high as 50, 60%. The American voter was just more ideologically flexible and more willing to give credit to presidents of the other party, especially at the beginning of their term when there’s a so-called honeymoon effect for that president right when they start out. Comparatively today, you never see a poll with the out-party of the president approving more than 15%, even at the beginning. And now it’s closer to five. About 5% of Democrats say they approve of how Donald Trump is handling the presidency. I imagine a lot of that, by the way, is like measurement error in identifying who a Democrat is. So...But the point is, that makes it really hard for a president to have high approval. The president has a higher floor and a much lower ceiling. So it’s really hard to persuade members of the other party to approve of them. Equally, their party members tend to approve of them pretty much regardless of what they do. So the fact that Trump’s approval rating is as low as it was for some of these really dark times in American history—for the presidency, at least—really says something about numbers that low.Krugman: He started out pretty positive, despite all of this, with immigration, deportations, all of that. And that’s gone negative. Is that just part of the general decline, or is there something special going on with the deportations?Morris: You know, it is impossible for me to say with the data that we have now whether or not someone would say they disapprove of Trump on immigration now purely because of immigration policy. So I don’t want to overstate the case here, but the fact of the matter is that Donald Trump and the Republican Party had, I think, a 15 percentage point lead on trust to handle immigration and deportations in the 2024 election. And now they’re even or underwater. So, you know, you might want to adjust in your head for the fact that this number is affecting the Republican Party as well; it’s not just Trump overall. It’s probably not just a factor, I would say, of Trump’s approval rating going down overall, because there’s been this other observed trend downward in trust for Republicans. I mean, you’ve been writing a lot about...Krugman: Trump’s net negative, -25 or so on approval. And the generic ballot is a much narrower spread in favor of Democrats. And that’s from what?Morris: It’s mostly Republicans who say they disapprove of Trump’s handling of the presidency—you know, his approval rating overall. But these people are still Republicans, right? Most of them call themselves Republicans and conservatives. The vast majority of those people who say that they will vote for Republicans on the generic ballot, but disapprove of Trump, voted for Trump in 2024. In a couple of columns I’ve called them “closet Republicans.” The fact of the matter is they’re really just Republicans; they may not even be closeted. They say they’ll vote for Republicans again. So we can’t expect every person who disapproves of the president to change how they would vote in a congressional election.Krugman: It was true for Biden and Democrats, too, in 2022.Morris: That’s right.Krugman: Actually, the Democrats did kind of okay in the 2022 midterms.Morris: Right.Krugman: Or better than you might have expected, given how unpopular Biden was.Morris: Yes, yeah.Krugman: Someone—and I think it’s YouGov—actually breaks Republicans into MAGA and non-MAGA. It’s pretty striking. Basically, the non-MAGA Republicans, which might be something like the group you’re talking about, are in many ways a lot closer in views to independents and Democrats.Morris: Well, since you’ve mentioned this: In their most recent poll release, either this week or last week, actually, they’ve broken down Trump’s approval rating among Republicans who call themselves MAGA—if you ask them, “Do you identify with the MAGA movement?” I think that’s the wording of the question—and those who don’t. And Trump’s approval rating among non-MAGA Republicans has really degraded. I mean, that is probably responsible for much of, if not most of his degradation in his overall approval rating. But if you look at Trump’s approval rating among non-MAGA Republicans at the beginning of his term, it is almost identical to his approval rating among Republicans who call themselves MAGA. Now today it’s underwater by, I think, 5 or 10 percentage points. So he’s just really lost a lot of ground among that group who doesn’t identify with his movement.Krugman: You had a map that really caught my eye, and I’m planning to do a little statistics on it myself, where again, this kind of synthetic approach where you try to produce an estimate of what net approval is on deportations—I think it was specifically deportations by state. How is that done? How do you do that?Morris: In brief, these maps of opinion—so statewide approval rating for this case of deportations—is generated with a statistical model that is called multilevel regression and post-stratification. What we do is we take our national polling data—in this case, ours is Strength in Numbers and my polling partner’s site. And this national polling data is 20,000 people or so. And we look at their demographic characteristics and who they voted for in the last election. And then we predict how every person in a given state—so let’s just say, like Texas—would answer our survey if we had interviewed them instead. And we know the demographic characteristics of Texas from the Census, and we know the political characteristics of Texas by past voting behavior from the last election. So we know that these estimates are rooted in demography and politics. We just balance by congressional district as well, not just at the state level. We actually get a little fancier than that; like, we have local-level knowledge about where these people live and what the political characteristics are in their state. But [talking about] that would be getting pretty weedsy.Krugman: But if you look at the map, the places where there is still positive approval on deportations is what I think of as—I’m patenting this—”the ICE belt,” which is sort of from Louisiana through West Virginia. If you know anything about the geography of immigration in the United States, these all happen to be places where there are very few immigrants.But I guess the way you construct it, you aren’t actually directly asking people their views on deportation, so I’m not sure this actually provides an independent check on the hypothesis that people are really hostile to immigration if they’ve never seen an immigrant.Morris: I will provide you some studies. I was at Pew Research Center in 2017, and someone there was publishing an analysis of whether or not, controlling for all their demographic and political factors, you were more pro-immigrant if you had been around immigrants more. And in this case, they were actually looking at support for building the border wall. And they found that proximity to the border wall actually decreased your support of the border wall. The most pro-border-wall states were Montana, Idaho, North Dakota, South Dakota—the states furthest away from the US–Mexico border. So that might provide some suggestive evidence for you, Paul.Krugman: Yeah, because I realized I actually can’t use your data for this, but okay, that would be helpful. I mean, I have my two favorite kinds of email that I do get. One of them is from people, typically actually in the Southwest, not too far from the border, who are very anti-immigration. And I get letters saying, “How would you feel if New York City was full of immigrants?”Morris: Have they been to New York City?Krugman: I guess a surprising number of people have not. But the other one is—and this is a little more esoteric, but—”How would you feel if lots of professorship jobs were going to immigrants?” And if you ever looked at the listing of a well-known economics department...Morris: ...and definitely don’t look at the computer science department of your local public university.Krugman: Yeah. So it is kind of a funny thing. But I’d like to believe that the familiarity makes you see immigrants as people, but that may be a little too romantic.Morris: Yeah, might be a little too optimistic, Paul.Krugman: Okay. What everybody is wondering about is: If the midterms were held today, we can be reasonably sure that Democrats would take the House. Then the Senate is a much harder climb and also more quirky. How much can things change, or how much do the things that we know might change affect it? Historically, how locked in are midterms by this point? I actually don’t know the answer to that.Morris: I’ll have to do a blog post on that one, because I don’t know the answer to the question in terms of, like, how often does the party that’s ahead end up losing in terms of binary? But the reason that we do these forecasts, at least at Fifty Plus One, is to really contextualize the polls and, along with that, the other information we have about the election. So those fundamental indicators—by which I mean, like, the way a state typically votes and whether or not an incumbent is running—contextualize the expert race ratings from the race raters, people like Cook Political Report and Sabato’s Crystal Ball. And the forecast probability on our website takes into account the usual amount of change in the election, or rather, the upper bounds of historical change in the election. That is what our confidence interval, our uncertainty, is for. I mean, the whole reason we really do it is to measure uncertainty in the polls and the other indicators today to see what could happen if they change or are wrong by the amount that the polls have typically changed or been wrong by.Krugman: Right. So when you say 87%, that’s not 87% Democratic control of the House if the election were held today, right?Morris: Right. But it does also include that sort of normal further movement against the party holding the White House, but also the uncertainty of events. Our forecast, which is different from some other forecasts out there that you might see, projects the amount of change that there typically is in the generic ballot. So the advantage that the Democrats in this case would get over the course of the election—usually the party out of power gains about a point to two points in the polls between now and November. And that makes a big difference in your estimated probability that in this case the Democrats would win the House and the position that they would have in the Senate by the time November comes around. But that’s just the right way to do it.There is a chart on our methodology page that shows the trend of the generic ballot over the course of the election year for every midterm going back to 2006. And it is quite stark: at about the 60-day-out mark—so Labor Day—there has always been a 1 to 2 percentage point increase in the polls. Again, patterns break down over time, but that is a pretty safe bet that as people tune into the election, they come to the conclusion that the party that is in charge of the White House does not deserve to be in control of the House. And that’s just typically what has happened.Krugman: Okay. And my specific concern—you know, people have no idea which party I want to see win! But anyway, my specific concern here is, okay, it’s possible that essentially the US has surrendered and that the Strait of Hormuz will reopen on Iran’s terms and that gasoline prices will come down and all of that. And the question is whether that can really make a big difference in the time remaining before the midterms.Morris: Well, it would take some amount of time for oil to be shipped back to America if there were refining capacity left.Krugman: That’s my alley, so I’ve definitely done that one. But, you know, imagine that somehow gas prices were to tumble by $0.50 over the next two months, something like that—which is certainly in the realm of possibility, though might not be the most likely forecast. How much difference could that make to the election?Morris: Yeah, I wrote about this last Friday. If you game out a return to $3-a-gallon national gas, it looks like that’s worth about ten points in Trump’s net approval on prices, and about a point, maybe two points if you’re really stretching it, in his overall approval rating. And that forecast is based on the change in gas prices that we witnessed through much of June and the change in approval rating that Trump saw in June. He did get a bit of a bounce back in June as the price of gas receded. He did not go all the way back to where he was when gas was whatever price it was at the end of June—I’m just not remembering the exact price of gas at the end of June. Forgive me, forgive me.Krugman: No, that’s all right. Now I’ll ask you what a gallon of milk costs and we’ll rule the U.S. forever on $1.99, I think.Morris: Okay, there we go.Krugman: No, but we’ve had a back and forth—both face-to-face and in sort of interacting blog posts—about public views on the economy generally and what it takes. And I look a little bit at the Biden years, obviously. We had $5 gas for a little while there in 2022, and then the price of gas came way down. Inflation came way down by late 2023. You could have said, “Well, this looks like an okay situation on inflation and gas prices.” But Biden’s approval on the economy never really recovered. And that’s what suggests really long lags here, right?Morris: Yeah, I think that was the second chart of my blog post from last Friday as well. If you look at how Joe Biden’s approval rating went up by ten points from -20 to -10 from peak inflation, which was I think July 2022, through the next spring in 2023. And then it of course went back down and he had—yeah, he effectively resigned the presidency, right?Krugman: Yeah, I mean, I think that in some sense the narrative is probably baked in already. People think of Trump as somebody who drove up their cost of living.Morris: Yeah. You wouldn’t bet that a president would get credit for inflation easing, whether or not it would be CPI or gas prices. Even if I’m oversimplifying our interlocking blog post chains… But what people seem to be reacting to is the pain. And then they remember the pain, even if prices stopped going up by as much as they were going up or indeed go back down. That creates a negative impression in the public’s mind of the person in charge of preventing the bad stuff from happening in the first place.Krugman: I think you haven’t exactly said this will be a wave election, but you said it sure looks like a wave election. What do you mean by that?Morris: You can make the title of this podcast, “G. Elliott Morris Says It’s a Wave Election,” and I will back that up statistically.Krugman: Okay.You know, we rerun our forecast historically in a backtesting where our forecast predicts, in this case 2018, using only the data that was available to it through the previous election cycle—so 2016—to gauge how our model would have reacted historically on out-of-sample data, the way that it’s reacting or the way it should be reacting this year. When we do that, we predict at this point in the election that Democrats would have had around a 70-75% chance to take the House and no chance to take the Senate in 2018. The map was too far tilted against them back then. Democrats ended up losing, I believe, two seats in the Senate in 2018. Comparatively, we think Democrats have about an 85 to 87% chance of taking the House, and they could very well win back the Senate. So I think that qualifies as a big blue wave, really.Krugman: Okay, but there’s a world of difference between taking and not taking the Senate.Morris: Well, and you know, one thing we don’t take into account, to be fair, is Pennsylvania Senator Fetterman changing his party identity—something like that. A sort of real black swan moment without any historical precedents. We just kind of have to caveat that one away; we can’t assign a statistical probability to that. Although, hey, that’s a good blog post idea! Let me see what the forecast would be if you assign a 50% chance to Fetterman changing his party ID if Democrats win. We can run that math.Krugman: Yeah, again, although that’s something where the difference between 51 and 52 Democratic senators is, you know—sorry, but my own nerdishness says that’s an endogenous variable there.Morris: Yeah, right. And there’s some weird game theory whether or not he would change his party ID if it meant deciding control of the Senate, right? Perhaps he would be much less likely to do that. He does still mostly vote on Democratic bills, even though he doesn’t necessarily vote against Republican nominees. For example, sometimes he blocks very important cloture motions. But for the most part, he does vote against Donald Trump, I think 90, 95% of the time.Krugman: Okay, that’s something I didn’t know. That’s interesting, yeah.Morris: They don’t want to lose a Democratic senator, even if he goes on Fox News every day and creates bad headlines.Krugman: Okay. There’s a bunch more that I could ask. But actually, just one last thing—I thought that was the last question, but just coming back to Michigan: There was an awful lot of money... the campaign financing was very heavily weighted against El-Sayed, which seems to have made no real difference, right? Is that telling us something about this year? I mean, should we not be worried at all about Elon Musk and Ken Griffin?Morris: I hate to be the bearer of bad news to you on this front. Money does really seem to matter. At least in primary elections, it really seems to matter, because in primary elections, we as voters don’t have as many partisan or ideological heuristics to fall back on. All right, Haley Stevens and Abdul El-Sayed are both liberal Democrats. Maybe one is more moderate than the other, but you don’t have a conservative running in that race for you to use your ideological identity as a proxy. So money and exposure to advertisements—and especially negative advertisements against the other candidate—can really have an impact.And I would hazard the guess that the—whatever it was—$55 million spent on Haley Stevens’ campaign, especially in the last week or last two weeks of the campaign, may have even been a reason that the polls so dramatically underestimated her, because they were old by the time the election came around. It costs a couple hundred dollars to change a vote in a Senate election, essentially. So Elon Musk is spending $150 million out there—you can do the math on that. If he’s changing a couple hundred thousand votes in the right places that could really matter if there’s no countervailing spending. Now, in a general election, people have their partisan identities to fall back on, and money is less important. But unfortunately, billionaires spending hundreds of millions of dollars on campaigns does seem to matter, and that’s a problem that the Supreme Court has declined to deal with.Krugman: All right. So I guess our bottom line is Democrats heavily favored to take the House, Senate in play, and we should still be afraid of billionaires.Morris: Yeah. Democrats favored to take the House. Elon Musk might be kingmaker via his ad spending.Krugman: Oh dear. Well, could be worse, but all right. Good to know. And thanks for keeping us up to date. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 An Explosion of Misery 05.08.2026 10minFor all my interviews and more, subscribe on YouTube.TranscriptContrary to what Trump administration officials say, we are not experiencing explosive economic growth. We are, however, experiencing an explosion in misery — and Donald Trump deserves full credit. Hi, Paul Krugman here, slightly different location. I want to talk about food stamps and health insurance, two areas where things have gotten dramatically worse just in the past year and are continuing to get worse. There's going to be a lot more hungry people in America, especially hungry children, by the end of this year, and a lot more people without health insurance or with inadequate health insurance. And it all can be tied directly to legislative action or inaction on the part the Trump administration and its allies. Here's what has happened. So we have what everybody still calls food stamps, though it's officially Supplemental Nutrition Assistance Program. But we have a situation now where the One Big Beautiful Bill didn't exactly cut the rate of benefits, but what it did was to impose work requirements. You might say, well,shouldn't people who can work work? Yeah, but that's not really what's happening. What's happening is that people who can work and do work —because among those who can work who are receiving food stamps, the vast majority do in fact work — must show proof of work. And that is, for many such people, a basically impossible burden. I mean, think of who is likely to be on food stamps. They may well be irregularly employed. They certainly may not have a job where they can call up the HR department and get the necessary forms. They are also presented with a complicated paperwork requirement. We're talking about people who are, to some extent, lacking in formal education. But above all — I've never been poor, thank God — but as everyone who's studied or been poor can tell you, the biggest issue of poverty in some sense is the cognitive burden, the constant struggle to just make ends meet, which is a huge burden on everything else. So you're imposing a bureaucratic hurdle, really a bureaucratic barricade in front of exactly the people least able to get across it. So of course, we're seeing a lot of people losing nutritional assistance with millions of those people children. Health insurance is a rather different story. The Affordable Care Act made a huge positive difference to many people's lives — in this case some people I do know quite well, small business people and so on. But the way it was set up, there are subsidies to help you purchase insurance through the exchanges. The subsidies are means tested. I could not get a subsidy for health insurance, nor should I. So they fade out with income. But as originally set up, they faded out too quickly with rising income, and there was a cliff at 400% of the poverty line, no more subsidies, which was clearly bad policy. And they knew that at the time. It was just that trying to scrape together enough votes to get that thing enacted was hard. So during the Biden years, the subsidy program was improved. It became somewhat more generous, but more important, it no longer had a cliff. It just gradually faded out. Unfortunately, that was not a permanent change. It wasn't enacted into legislation for forever. There was a cutoff date. Why? Well, two words, Joe Manchin. But in any case, obviously, Trump and Republicans in Congress refuse to even contemplate extending those enhanced benefits. And so a lot of people are now faced with vastly higher costs if they want to retain their health insurance. Interestingly, these are not the poorest. The poorest are going to be on Medicaid and even people a little bit above that are still going to have the full subsidy. But it's people in the middle class whose income is a little above 400% of the poverty line and suddenly have no subsidy available. That is a hardship for, again, millions of people. So far we know that enrollment on the exchanges that were set up to buy health insurance has dropped by about three million so far. Probably a lot more to come. And probably that understates the loss because people trying to save money because things are more expensive are in many cases stepping down to less comprehensive plans. So there's an increase in the number of underinsured too. Which means that a large number of Americans who had adequate health insurance no longer do. How should we think about all of this? The Trump administration has put out a report on the decline in Affordable Care Act enrollment, which is really a blood-boiling document because it portrays the big rise in enrollment that took place during the Biden years as a problem because it was an increase in fraud. Now, is there fraud? Yes, there's fraud in the Affordable Care Act. Is there fraud in the food stamp program? Yes — there's fraud in every program, public and private sector as well. There's fraud in the endless pasta deal at Olive Garden. There's fraud in frequent flyer schemes. There is no reason to believe that there is significant fraud in the sense that it's a significant, important part of any of these programs. And one thing that you always want to bear in mind when we're talking about these means-tested programs is how cheap they are. The average food stamp recipient receives $187 a month in nutritional assistance — $187 a month, a little over $2,000 a year. Maybe one way to put that in context is to say that Donald Trump's East Wing Ballroom Project, the one that is so far still just a hole in the ground and hopefully will never be finished, is costing $600 million. So that project alone, that scam, because we know that there's a lot of corruption involved, that is the equivalent of food stamps for 300,000 people for a year. So the things that we're talking about here are, it's not really about the money. It is one of those “the cruelty is the point” stories. And we could go on about that, but clearly the fact that a lot of people are going to suffer is not an unintended byproduct of these policies. It is kind of, in some ways, the goal. It's also enormously destructive, not just for people's lives now, but for the future. One of the best established facts about the benefits of government spending is that nutritional and health assistance to children pays off for society as a whole. That children who received food stamps or Medicaid in their early years grow up to be healthier, more productive adults who pay more in taxes and are less likely to need government assistance. The rates of return on both the food stamp program and Medicaid, the original aid for health care for the poor, are enormous. They're far bigger, far better substantiated than almost anything else you can do. If you ask, you know, what do we know about the payoff to infrastructure investment? Well, we think it's pretty big, but... that's not based on solid evidence. The evidence on these programs is enormous. So by cutting back on these programs, by creating this explosion of misery, they're not only making millions of Americans much, much poorer than they were, they're also making the country as a whole substantially poorer in the long run. It's an anti-growth policy. But of course, the cruelty is the point. And here we are. Many things happen to the economy, many things happen to society that are outside the control of the guy in the White House. Many bad things aren't really the fault of the party in power. This is absolutely, totally Donald Trump's fault. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 The Fire This Time 27.07.2026 8minFor all my interviews and more, subscribe on YouTube.TranscriptSome say the world will end in fire. Some say in ice. Robert Frost wrote that in 1920. With more than a century gone by, we have a verdict. It’s fire for the win. Hi, I’m Paul Krugman. I thought I’d talk today about a story that should be getting even more play than it is. I mean, there’s so much going on, but, you know, Europe is on fire. There are massive wildfires in France and Spain that have forced the evacuation of hundreds of thousands of people, are menacing Bordeaux and not too far from Madrid. This, of course, follows on the enormous Canadian wildfires that for a while gave Toronto the worst air quality on the planet and turned the skies orange and the air foul across a large part of the eastern United States. And that, in turn, followed on that deadly heat dome in Europe that killed thousands of people. Okay. It’s pretty awful. It’s also something that was predictable and predicted. If you go back — I’ve been looking at a 2012 report from the UN, their climate project, that very clearly forecast growing incidents of extreme weather, extreme heatwaves, storms, flooding, and by implication, at least, wildfires. This was clearly in the cards. In fact, the story that somehow has not become standard is that climate scientists pulled off something that was extraordinary in intellectual terms. They got the basic outlines of what was coming and in many ways even the numbers on what was coming right decades in advance. In any kind of rational world we would be hailing them as heroes and very much listening to them about what we should be doing now. Of course where we are is that climate scientists are reviled. Climate change is almost crowded out of the political discussion and there’s a fair bit of actual personal persecution of people like Michael Mann and so on who are being punished for the sin of being right. Okay, of course, it’s more than just that. Now, there are sort of multiple levels to the climate story. At one level, it’s, you know, there are powerful vested interests that don’t want you to take global warming seriously. Fossil fuel interests are dying as an industry, but they’re dying slowly and they’re doing their best to take us all with them. And they have enormous influence in this administration. That feeds into something else, which is very true of the people now running the federal government, which is they hate science. So this is across the board. There’s almost always some financial interest, but it’s not just follow the money. It’s just a real hatred of the whole scientific enterprise. And so in an obvious sense, the climate denial is of a piece with the determination of RFK Jr’s health department to find a link between vaccines and autism. There have been many studies saying, no, it’s not there, but that’s not the answer they want. And they just kind of hate the idea of scientists, they hate the idea of objective research of any kind. And so that feeds right into the climate denial.And then, actually, it’s even broader and deeper than that. I don’t think you can really understand what’s going on in this administration without saying that there’s a kind of hatred of the intellect, not just science, but really any kind of hard thinking. I mean, at some, not very deep level, it’s an obvious correlation between Trump saying that the reason that we had fires in Canada is because the Canadians didn’t rake their forests, — all, by the way, two million square miles of boreal forest in Canada. You know, there’s just this absurdity, this kind of evil absurdity of the whole situation. And Pete Hegseth, having presided over the humiliation of the U.S. military because we were not ready for 21st century warfare and the Iranians were. So he’s busy suffering casualties and of course trying to hide them, suffering enormous damage and complete failure of war aims in the face of drones and missiles and basically this new world in which the Ukrainians are showing the way. This is warfare, which still requires some people, still requires enormous personal courage. But the decisive arms of battle are machines, fairly advanced machines, although cheap compared with the expensive hardware we have. And so here you have Pete Hegseth, faced with all of that, and he thinks that what the U.S. military needs is more testosterone. And that’s not a metaphor. Literally, he wants to give testosterone shots. The truth is that even the ancient Spartans didn’t win battles just by flexing their biceps. Intellect was an important part of war, even in the 5th century B.C. But now, above all, consider the craziness of thinking that it’s all about brawn and muscles and good grooming. Oh my god. But this is all hatred of basically anything that involves hard thinking. Again, the deep point is it’s not even exactly, I think, that people in this government are lying about climate, that they’re lying about military stuff. I mean, yes, of course there’s a lot of lying, but I’m not sure they even really have the concept that there is objective reality. And they certainly hate anybody who tries to argue that what they’re saying is objectively, empirically not true. How did we get here? I’ve been writing about oligarchy, and it’s certainly true that the big money — and the big money has never been bigger — that the big money has thrown its weight behind these deeply anti-intellect, anti-science people. This is in the long term, and not very long term, really against their own interests, but the short term lure of tax cuts and a corruptible government — because they’ve got the money to do the corruption — I guess outweighs that. And also, of course, quite a few of the mega-billionaires are themselves caught up in this. If we all get through this, Elon Musk and the general awfulness of the people who somehow end up with hundreds of billions of dollars is going to be a cautionary tale for generations to come. Anyway, that’s where we are. What can I say? I’d really like to not talk about depressing stuff, and I will now and then, but boy, we are in quite a state. And the sky is blue right now, so I guess I should go out and spend some time outdoors while we still can. Take care. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Talking Again With Gabriel Zucman 25.07.2026 52minFor all my interviews and more, subscribe on YouTube.In my writing about wealth concentration and oligarchy, I steal a lot from lean heavily on the truly work of Gabriel Zucman, who is a hugely important researcher (winner of the 2023 Clark Medal) who is also starting to play a major role in policy. I’ve talked to him before, but this seemed like a good time to bring him back.. . .TRANSCRIPT: Paul Krugman in Conversation with Gabriel Zucman(recorded 7/23/26)Paul Krugman: So, hi everyone. Paul Krugman here, bringing back Gabriel Zucman, probably the best guy for thinking about inequality, especially wealth issues. And since I’ve been writing about that and stealing a lot of Gabriel’s research, I thought we should talk again. So, hi Gabriel.Gabriel Zucman: Hi Paul, thanks for having me on.Krugman: Yeah. So, you have been writing—and now I’ve been, you know, cannibalizing it—a lot about wealth concentration. Why don’t you tell us about your reasons for focusing on wealth.Zucman: Basically, because there’s a fundamental tension in democratic societies between extreme wealth and the very possibility of a well-functioning democracy. And it’s not a new idea—don’t get me wrong. All the thinkers of democracy have written about this, all the way back to Aristotle, more than two thousand years ago.Krugman: Right.Zucman: But there was a period of time after World War II when many people thought that this issue belonged to the past. And it corresponded to a very particular moment in history when extreme wealth had largely disappeared after World War II, after the shocks of the first half of the twentieth century.But now, of course, it’s making a dramatic comeback. And so we are back to this discussion of: how do we deal with this tension? How do we organize the economy and our society to prevent the forms of capture of the political process, in particular, that are associated with extreme wealth?Krugman: Now, there’s a question. I mean, I’ve been on the inequality beat for an alarmingly long time—since you were a small child, actually. But in the early nineties, let’s say, it was all income rather than wealth. And a lot of it was top quintile, and maybe top one percent. And now you’re telling us that we need to focus on the wealth rather than the income of the top 0.0002 percent. Why that shift? Why wealth rather than income?Zucman: Well, it’s for two reasons. Number one is a macroeconomic reason, which is that wealth as a whole has been growing much faster than income. So if you look at the ratio of total household wealth to GDP in the US in 1980, it was around 200–250%, and today we are past 500%. This means that the total wealth of the country is equivalent to more than five years of annual production, five years of annual GDP. The second reason is that wealth itself has become much more concentrated, and the rise of wealth inequality, especially at the top of the distribution—at the very top—has been massive and has been even faster and stronger than the rise of income inequality.So we all know about the rise of the top one percent; the top one percent’s share of total income has increased from about ten percent of income in the US in 1980 to about 20% today. But at the top of the wealth distribution, the increase has been even much more dramatic than that.Krugman: At the risk of derailing it slightly, one thing that I myself have gone back and forth on—and certainly I get from comments on things I write—is a question comparing the wealth of the top 0.001%, or whatever: should we be comparing it to total wealth or to total income? And I know you’ve used wealth to GDP, and I have some thoughts, but you’ve done it both ways. Which do you use, and why would you use it? I don’t know which is right, but what are your thoughts?Zucman: I think both statistics are interesting and capture different aspects of reality. So if you’re interested in wealth inequality, in the concentration of wealth, the most meaningful statistic is to divide the wealth of the super-rich by total wealth in the economy. So, for instance, if you look at billionaires—roughly the top 0.1 percent of the population—they own about seven percent of total US wealth today. In 1980, they used to own about one percent of total US wealth. So it gives you a sense of the rise in wealth concentration. If you look at the super-top, you know, the oligarchs, the twenty wealthiest families—a very, very small fraction of the population—their total wealth is 2.0 to 2.2% of total household wealth in the economy. So I think that if you care about wealth inequality, these are the relevant numbers.Now, it’s also interesting to compute another statistic, which is the wealth of those top groups, and in particular the oligarchs, relative to total income or total output in the economy, because it gives you a sense of their influence on the economy and also because it gives you a sense of how much revenue there is at stake from taxing their wealth. So let me illustrate. If you get back to the 20 wealthiest people in the country, they have about 2 to 2.2% of total US wealth, and that’s equivalent to about 12–13% of total US GDP.Okay, so now you’re dividing a stock—their wealth—by a flow. And what it means is that if they spend their wealth—of course, they’re not going to do that in a given year, but imagine that they spent all their wealth in a given year—then they could buy 13% of all the goods and services produced in a given year in the US. So it really gives you a sense of just how big they are relative to the economy as a whole. And also it gives you a sense of what’s at stake with taxing billionaires. Because, of course, the way we think about tax revenue and about government budgets, is often in relation to GDP.And so here, what you have with billionaire wealth is that there’s a potential tax base; we are not taxing billionaire wealth today, which has been skyrocketing. That’s the flip side of the rise of wealth concentration. The positive aspect in all of that is that now there’s a lot of tax revenue at stake from potentially taxing the wealth of billionaires.Krugman: Yeah. I mean, my version is, I mean, most people have very little wealth, right? Wealth is highly concentrated, and what most people have is income. But the very top has wealth, and in some sense, the wealth-to-income ratio is telling you how many minions they can buy, how much influence they can buy in the economy and in politics. Is that kind of what you’re saying, or is there something else?Zucman: No, exactly. When I say that expressing their wealth relative to total income gives a sense of the influence they have, precisely it gives you a sense of how much they can spend on buying media companies, on funding electoral campaigns. Billionaires accounted for nineteen percent of total political spending during the 2024 federal election cycle.Krugman: Right.Zucman: They can fund think tanks and foundations, and influence the prevailing ideology like that. So it’s in that sense that it’s really useful, I think, to express their wealth relative to the value of the total income of people in the country.Krugman: So again, what’s your take on why total wealth has grown faster than income?Zucman: There are different stories, and I think the one that makes most sense to me and that seems most consistent with the data is that there’s been a number of policy changes since the 1980s that have favored wealth and capital, broadly speaking. So, for instance, you used to have rent controls for housing in many countries; when you lift rent controls, the value of housing wealth tends to go up. Many countries used to have pretty high corporate income tax rates, of almost fifty percent on average at the world level in the 1980s. Well, when the government takes half of the profits of companies, it capitalizes into stock prices; it reduces the market value of companies. But then when governments slash the corporate tax—and it has declined from about 45–50% to about 20–25% today at the global level—well, that again capitalizes into stock prices, and now it boosts the market value of companies, of equities.And you’ve had deregulation in many sectors that has boosted the profitability of corporations. You’ve had a significant change in the division of value added between labor and capital—the rise of the capital share, the decline in the labor share. That means more profits, more income for shareholders; again, it boosts the value of corporate equity. So all of these changes, they don’t happen like that out of nowhere. They are, of course, heavily influenced by policy.So, for instance, changes in factor shares—labor and capital shares—have been partly affected by the decline in union power. When unions are stronger, you tend to get a bigger labor share. When unions are weaker, you get a bigger capital share. Also in the way that we organize international economic relations, globalization. When we organize things without any kind of international tax coordination, or to put it differently, if we organize global economic integration by allowing total tax competition—no minimum taxes, no minimum tax rates—then capital owners can threaten to outsource production or to shift profits to low-tax places, and again, it reinforces the power of capital, hence the value of wealth.Krugman: Okay, But going back maybe twenty-five, thirty years ago—and again, I’ve been in the decrying-inequality business for a long time—we were saying, “You know, there’s a huge rise in income inequality, but it hasn’t really shown up in wealth.” And that really started to change. It’s not just that wealth has increased, but as you say, a huge increase in concentration in a few hands. So, what’s your story? I think I know what your story is about what drives this increasing concentration of wealth, but what is the mechanism? What’s it all about?Zucman: I think there have been different factors at play, so it’s not just a one-issue story. The thing that seems important to emphasize from my perspective is the dramatic changes that have happened with taxation, particularly in the US. Many people have forgotten, but the US used to have a sharply progressive tax system where capital was heavily taxed, where high incomes were heavily taxed, where large inheritances were heavily taxed. In fact, it probably used to have the most progressive tax system in the world between the 1930s, the New Deal, and the late 1970s. And then during the 1980s, it went all the way in the opposite direction.And perhaps what’s most striking is what has happened with the income tax. So when Reagan enters the White House in 1981, the top marginal income tax rate in the US is 70%. At the time, it’s the highest top marginal tax rate of all industrialized countries in the world. And then in 1986, you have the big tax reform, the Reagan tax reform, that slashes this top rate to 28%, which at the time was the lowest tax rate among industrialized countries. So it’s a really big change in just five years. And you’ve had that for the income tax, but also for the estate tax. The corporate tax rate used to be 50% after World War II; after the 2018 Trump Tax Cuts and Jobs Act, it’s been reduced to 21%.And so all of these really big changes, all going in the same direction, have had a massive effect on two things. So, first of all, on the incentives for very wealthy people to try to earn super high incomes. When the top marginal income tax rate was close to 100%—more than 90% in the 1940s and 1950s—there was just no incentive to try to earn a ton of money, because you knew that past some point, almost any extra dollar would go to the IRS. So why bother? Why try to bargain a super high compensation as a CEO? It was just pointless. Now when the top marginal income tax rate is 28%, it becomes really profitable to try to earn super high incomes, right? Because you get to keep most of the money for yourself. So there is this incentive effect.And there’s of course the pure mechanical effect, which is that with lower tax rates, you have more disposable income when you’re very rich, that you can save and use to grow your wealth. And that’s why I think those changes to taxation, which have been particularly powerful in the US, have played a very important role in the particularly fast rise of US inequality.Krugman: Now when you talk about incentives, if I were a right-winger, I’d say, “Well, the old system discouraged people from innovating, being job creators, and all that.” And I think that’s not what you mean, right?Zucman: Well, then it becomes an empirical question, right? In principle, it could be true. You could say, “Well, when people face those super high top marginal income tax rates, it discouraged people from innovating, from launching businesses.” But then you look at the data and you realize that in those decades after World War II, GDP growth was higher, in fact, than it’s been since the 1980s. Investment rates were no lower; in fact, they were higher. US capitalism, broadly speaking, seemed to work okay in that period of time. So of course you don’t know the counterfactual. You don’t know what would have happened if the tax rates had been much lower at the top in those decades. But what you can know as a fact is that these quasi-confiscatory rates on high incomes—and we’re talking about rates that apply to only super high incomes of several millions of today’s dollars—just didn’t kill innovation and growth and capitalism. And you have to think about who you are discouraging, what type of behavior you’re discouraging when you tax very high incomes at very high rates.Krugman: Right.Zucman: You could say, okay, perhaps it’s going to discourage innovation, but you know, are scientists or innovators really motivated by the extra income they’re going to be able to make above five million dollars in income? You know, perhaps, perhaps not. You’re also discouraging people who want just to capture rents, who want to create private universities that sell fake diplomas, for instance, or want to exploit patents and squeeze as much money as possible from consumers or patients or sick people, and so on.So there’s always in the economy people who are motivated by innovating, creating knowledge, and broadly speaking undertaking activities that are positive-sum for the economy as a whole. But there’s also people who are motivated by rent extraction, by different activities that are inherently zero-sum or even negative-sum. And suddenly, when you have 90% top marginal income tax rates, you’re discouraging this type of zero-sum rent extraction, which is the plausible reason why this policy was so effective, at least relatively effective, in the postwar decades.Krugman: The classic example from my angle has been that corporate CEOs have always basically set their own salaries. But in 1959, extracting a salary that was 500 times that of your average worker just made everybody mad at you, and you didn’t get to keep much of it anyway. And nowadays you do. So…It looks as if—and certainly from your work and those of us who pick up on it—we have had this process since the late seventies of this concentration, this oligarchy rising in our society, and that taxes have a lot to do with it. So the question is: what are the remedies? I know that we’ll get to wealth taxes in a minute, but we had a workable recipe, which was high corporate taxes, high estate taxes, high top marginal rates. Is there a reason why we can’t just reconstitute that regime, or why we shouldn’t—either as a possibility or desirability?Zucman: I think we could do it and it would make sense, but also, probably, it wouldn’t be enough. First of all, one of the outcomes of the first Gilded Age at the beginning of the twentieth century was the creation of the progressive income tax in 1913 and the progressive estate tax in 1916. So we instituted taxes to prevent or to curb the rise of concentration that was observed at the time and that many people were worried about.Krugman: Right.Zucman: It made a big difference, but also there was, and there’s always been, a kind of fundamental limitation, I think, with this historical experiment, which is that when you’re extremely wealthy—and think about billionaires—it’s, in fact, very easy to own a lot of wealth without having to report any or any significant amount of income. And so it’s, in fact, relatively easy to avoid the income tax. And we kind of knew about that from various anecdotes and case studies.For instance, a few years ago you had revelations by ProPublica on the taxes paid by US billionaires, and you saw people like Jeff Bezos and Elon Musk in some years reporting very little income, paying very little income tax. There’s even one year when Bezos says, “Look, I’m so poor that I’m going to claim the child tax credit,” and he receives the child tax credit! So we kind of knew about these limitations of the income tax, but it’s only relatively recently that we’ve come to understand that this is a structural feature of income taxation in the US and globally—a structural feature that the super-rich have not yet entered into the system. The income tax is just not the right instrument to tax them.And so that’s why, in addition to the income tax, you need some kind of tax based on wealth. Because for the very rich, it’s easy to manipulate income to pretend they have no income. So, for instance, Bezos, as CEO of Amazon, didn’t pay himself a wage, he instructed Amazon not to distribute dividends, he didn’t sell shares, and so he didn’t realize capital gains, and so his taxable income was really low. There’s no tax evasion there; it’s all perfectly legal. But, of course, his ability to pay taxes as one of the world’s richest men is, of course, extremely high. And so that’s why, for people like him, the right tax is based not on income, but on wealth, which is much harder to manipulate than income. And that was partly one of the reasons for having an estate tax, which is a tax on wealth, but it’s not enough because the estate tax is just a one-time tax at the time of death. And so you can be in a situation where the wealthiest people in the country, year after year, pay no or almost no income tax. And it’s only when they die—when the estate tax was still functional—that we tried to make them pay a little bit of tax.That’s the limitation of the US experiment with progressive taxation, which is that it never really tried to make the ultra-wealthy pay personally on an annual basis. And I think that it is this limitation that we need to overcome in the 21st century. And basically, that has to involve some kind of annual taxation based on wealth.Krugman: Let’s talk about corporate taxes first. We used to collect a substantial amount of corporate taxes. There’s a lot of dispute about exactly who pays them, but your position, as I understand it, is that basically they fall on stockholders. Why did we retreat so much on corporate taxes, and could that be reconstituted or should it be?Zucman: So first of all, yes, you’re right that the corporate tax used to be a big source of tax revenue for the US. It peaked in the early 1950s at something like six to seven percent of US GDP in tax revenue, just from the corporate tax. That was with a nominal tax rate for the federal corporate tax that was slightly above 50 percent, but the effective rate was also 50 percent. It meant that out of any dollar of profit made, 50 cents went to the government.Krugman: Right.Zucman: And today we are down to about 1.5% or so of GDP in tax revenue—1.5 to 2%—from the corporate tax. So it’s a big decline. The standard story is that it’s going to reduce corporate investment, which is going to translate into a decline in the capital stock, and then workers are going to be less productive because capital is good, it complements labor, and so eventually it reduces wages, and so it’s bad for ordinary workers. That’s the standard story, which, frankly, doesn’t have a lot of empirical support for it. But why not? As an intellectual story, it makes some sense in principle.The other reason, which has been even more powerful in practice, is international tax competition. It’s the idea that we cannot tax corporations at higher rates because otherwise they move to other countries, and that there is this kind of law of nature: the race to the bottom with corporate taxation is something we just have to accept as a law of nature, like gravity. And that also is wrong, because, of course, it’s not a law of nature. It’s a choice that we make collectively to accept international tax competition, or to fight it and to curb it. So I think what this all means is that, of course, we could revert to higher corporate tax rates. That’s definitely something that the US, or in fact any country, can do.But what I want to say is that, also, it wouldn’t be enough, because the corporate tax is just a flat tax on corporate profits. So someone who owns just one share in Amazon, indirectly is going to pay the same tax rate through the corporate tax as Jeff Bezos, who owns ten percent of Amazon. It’s not progressive, and so that’s why it’s structurally limited.Krugman: Okay. In the abstract, if our concern is great wealth and we’re looking for some way to limit that and also raise some revenue—though I think in many ways the social and political implications are even more central than the revenue—the history shows remarkably little experience with wealth taxes, right? I mean, we don’t have a lot of evidence, and a lot of people say that they’re unworkable, citing what they claim to have been the history of France. So why don’t you talk to me about the history of wealth taxation?Zucman: Yeah, I mean, the US never had an annual progressive wealth tax, at least at the federal level. There’s, in fact, a pretty long history of wealth taxation at the state level in the 19th century, with so-called generalized property taxes that were taxes not just on real estate and land, but also on financial assets, typically at flat rates, so not rising with wealth. There’s a long tradition in the US that’s been largely forgotten.The more relevant history is the European experience with progressive wealth taxation. Many European countries used to have progressive wealth taxes. And I agree that the track record is not good. By and large, they were not big successes. But, of course, there are two ways to look at that experience. You can say, “Well, some countries tried wealth taxes, it didn’t work very well, hence it will never work.” End of story. Or you can try to study this experience and try to understand what were the problems and what lessons can be drawn, and whether the issues can be overcome.And this is what I’ve been doing with many others in my work, and the conclusion I’ve reached is that, yes, they had issues, these European wealth taxes, but the issues can be fixed.The biggest issue is that those wealth taxes didn’t even attempt to try to tax billionaires. Look at France, for instance. France is really a striking illustration. The French wealth tax was created in 1981 when a Socialist president comes into power and he has an absolute majority in parliament, and so he creates a wealth tax. But immediately he says, “Okay, we are going to exempt from the wealth tax people who own more than 25% of the shares of a company.” Okay? So if you’re a big shareholder in a company, no matter whether it’s listed on the stock market or not, if you own a ton of stock, that’s going to be removed from the base of the wealth tax. This will be tax-free. But, you know, the wealth of billionaires is precisely that: it’s owning a lot of shares in a company. So what France did in 1981 was like if the US today created a wealth tax and said, “We’re going to exempt Warren Buffett from the wealth tax, or we’re going to exempt Elon Musk from the wealth tax because they have so many shares in their businesses.”You know, it really makes little sense. And the consequence is that the effective wealth tax rate for French billionaires in 2016, on the eve of the abolition of the wealth tax, was just 0.005% of wealth. They didn’t pay it. And it’s not because they illegally hid assets. No, no, it’s because they were legally exempted from the wealth tax.Krugman: Why did Mitterrand do that? Do you know?Zucman: The way the story is often told is that some of the top billionaires complained and went to see him, and they said, “We’re going to move to Switzerland if you do that.” And so that’s how they got that exemption.But the deeper explanation, I think, is that there was no real commitment on the part of Mitterrand or the Socialist Party to having a tax on billionaire wealth, partly because they thought it would be impossible, that we had to accept international tax competition as a kind of given, that France would be powerless to do anything about that; partly because it was never a big priority for them. They bet on other policies to transform society that didn’t involve progressive taxation, but that involved things like the nationalization of some companies or labor market regulations. But progressive taxation was not part of their ideology, so to speak. They were not very committed to that.And also, I think in the 1980s, you could make the case that the government revenue at stake was just not very important. So it was not worth fighting for this. I think that was their view. And perhaps you could make that argument in the 1980s or 1990s, but today, it’s impossible. Look at what has happened to the curve—the wealth of billionaires has skyrocketed. So now it becomes really important to include them in the base. So that was the main problem: billionaires were legally exempt.The other big problem—and it’s related, of course, to the first one—is that those European countries never tried to do anything to fight the risk of out-migration by the super-rich. They just thought that, “Okay, we are powerless. If they want to leave, what can we do?” And that’s just not true. For instance, in the US, there is citizenship-based taxation, meaning if you are a US national, you have to pay taxes in the US no matter where you live. So you can move to Monaco or Switzerland if you want, but you still have to pay federal taxes.Krugman: Right.Zucman: France or Germany could have done that; they could have done a variation on that idea. But the big blind spot of the social democratic experiment in Western Europe has been, in my view, this inability to confront the forces of international competition, and international tax competition in particular.Krugman: So that’s it. Do you want to enlarge on that? Because I think that’s an interesting point.Zucman: Yeah, these social democratic governments never invested intellectually in trying to organize international economic relations and make those consistent with their ambitions for democratic transformation. Or, to put it differently, the social democratic project was always thought of as a purely domestic endeavor. And when they realized that there was competition from other countries—tax competition in particular—their reaction was not, “What can we do about that? How can we rewrite the rules of global commerce? How can we forge international agreements, or how can we design unilateral policies to protect ourselves from those forces?” Their reaction was not that. Their reaction was, “There’s international competition. We cannot do anything about that. We just have to adapt.” And so we have to embrace the race to the bottom with capital taxation.And that’s how, in fact, it’s socialist governments, or Labour governments in the UK, or the SPD in Germany, that have slashed the corporate tax rate. Scandinavia, too, moved from a comprehensive income tax where capital and labor are taxed the same, to so-called dual income tax systems where capital income is taxed at lower, flat rates than labor income. Always for the same reason: they never tried to think about how to make social democracy compatible with a globally integrated economy.Krugman: That makes sense. Although I think that the EU has a kind of minimum VAT rule, right? So the tax that falls on working people, you cannot make it too low, but the tax that falls on billionaires...Zucman: Yeah, that’s a very good point. The only form of tax harmonization that you have in the EU is on VAT. So when it comes to taxing consumers, the middle class, the poor, all of a sudden we can craft common rules. But when it comes to taxing companies or the rich, what can we do? You know, nothing.Krugman: So if Ireland goes and poaches corporations—although I think it’s mostly US corporations there, but anyway—Ireland can do that, but they can’t offer shoppers bargains. It’s pretty wild.Zucman: Yeah, exactly. That’s a very particular worldview, but that’s been central, in fact, in how European construction has proceeded so far. And I think if you want to rationalize this view, deep down there is the idea that it’s not just that international tax competition is a law of nature, but also that it’s a good thing, frankly. That it’s something we should embrace because those welfare states in Western Europe are too big and they need some kind of external outside pressure to force governments to be more efficient—to starve the beast a little bit. And I think many people, even left-of-center people at one point embraced this idea that we should welcome it—it’s going to make us more efficient. We should welcome international tax competition.And why not? You can make that case, but I think it has two problems. One is that it’s a pretty undemocratic way to decide things. It assumes that voters are going to structurally choose policies that overtax capital or the rich, and hence the need for constitutional constraints or external forces. And, of course, the other problem is that international tax competition, the way that it has unfolded, has fueled the rise of inequality, because the main winners from this are multinational companies and their owners, or people who derive most of their income from capital income, the wealthy, and so on.Krugman: Right. Sort of Reaganite ideas may have actually had a lot of impact even in Europe.Zucman: They did. Even though it was never formulated that explicitly, I think this ideology was very influential, in fact.Krugman: So you’ve been pushing for, in fact, some kind of global accord that basically makes it possible to do more wealth taxation. I’ve been re-reading your G20 paper on all of this. I don’t think this is anything likely to happen anytime soon, but what’s the state of the idea?Zucman: It will happen, but patience.Krugman: Yeah, patience. Well...Zucman: The beginning of all of this was in 2021: there was an agreement among 130 countries for having a minimum tax of 15% on the profits of big multinational companies. And, frankly, very few people had seen that coming, because the prevailing view was, “You know, it’s impossible to get an agreement like that. Small countries like Ireland benefit so much from international tax competition. It’s just utopian.” But it happened in 2021.And then, in 2024, Brazil had the presidency of the G20, and they wanted to put new ideas on the agenda, and they asked me what I thought. And what I told them is: “Look, I think we should do for billionaires what we’ve been able to do for multinational firms. So let’s try to have an agreement on a minimum annual amount of tax owed by billionaires.” They commissioned a report from me, and some progress was made at the G20, but then, of course, Trump was reelected, so nothing can happen at the moment at the G20 level.But what’s really interesting is what is happening at the national and, in fact, subnational level these days. Because right after the Brazilian G20 in 2024, the French National Assembly adopted the minimum tax on billionaire wealth that I had proposed. So it’s a tax of 2% on the wealth of people with more than 100 million dollars or euros in net wealth. And it’s a minimum tax, which means that if you already pay an income tax the equivalent of two percent of your wealth or more, you have nothing more to pay. But if you pay less than that, you have to pay the difference to reach the two percent minimum. So it’s the fairest and the most targeted tax that you can imagine, because it’s just on the ultra-wealthy, but not only that, on those among the ultra-wealthy that avoid taxation today.So France voted for that; it was then blocked by the very conservative Senate. But there is the beginning of an international movement in that direction. You’ve had a bill crafted under French legislation that’s been introduced in Belgium, perhaps soon in the Netherlands, and in Spain. At the moment in the UK, they’re talking a lot about that with the new Prime Minister, Andy Burnham.And then, of course, most important in my view, is what is happening in California with Prop 40, the California billionaire tax, which is going to be on the ballot in November. This would be a one-time tax of five percent on the wealth of California’s billionaires. Frankly, it’s very important for California, for funding healthcare, Medicaid in particular. But it’s even more important for the US and, in fact, for the world as a whole. Because if California passes the California billionaire tax in November, I think this will really be the beginning of the US and international movement to tax the wealth of the super-rich.Paul Krugman: Okay. And this is a one-time tax, and it’s retroactive, right? It’s based on your wealth last year.Zucman: Yeah, exactly. So it has several characteristics. It’s one-time and not annual. And it’s only for billionaires, not for you and me. It’s on billionaires, and it’s on those billionaires who were residents of California as of January 1st of 2026. So it’s too late to avoid the tax, meaning if you were living in California at the beginning of this year, you would still have to pay the tax. So in that sense, there’s a small retroactivity here. And these two characteristics combined—the fact that it’s one-time and based on being a resident as of January 1st of 2026—mean that it’s nearly impossible for any billionaire to avoid the tax by moving to another state. So it also means that if it passes, it’s bound to generate a lot of tax revenue.The arithmetic is quite simple. The billionaires of California have about two trillion dollars in wealth. So if you tax them at five percent, you get a hundred billion in tax revenue. Another kind of illustration of how big the billionaire wealth tax base has become, which I think is quite striking, is the following: if you look at all the income of Californian people as reported in their tax returns—you know, AGI, adjusted gross income for California as a whole—it is the same number as the wealth of California’s billionaires, 250 people. So, their wealth is 100% of California’s AGI. Meaning, if you have a five percent tax on the wealth of billionaires, it generates as much revenue as a five percent tax on the income of all people in California. So that’s just a very striking illustration of what we were discussing earlier, which is just how massive the wealth of the billionaires has become and hence its implications for public finance.Krugman: Yeah, one of the things in California is it does have high personal income and high personal wealth, but that’s a few hundred people. They really skew the numbers. And so, how’s it going? I mean, it’s a little bit disappointing to see all of the “don’t be evil” guys from Google and all of that scrambling to protect themselves from taxes. But how are you feeling about the proposition?Zucman: Well, I’m not surprised by that, right? They have good reasons to hate this, because this is the one tax that they would have to pay. You have to realize that they pay very little today. The billionaires in California pay in income tax the equivalent of just 0.2% of their wealth. So, you know, moving from 0.2% to 5%, even if it’s one-time, it’s a big difference for them, even though their wealth has increased like 200% over the last two years. So from that perspective, it’s a drop in the ocean.But I think the polling is good. It’s going to be a battle just because the billionaires are spending tens of millions, hundreds of millions already, to stoke fears and try to defeat the proposition on the ballot. But I think the logic, frankly, is so compelling, and also billionaires are not very popular at the moment in California, like everywhere else, so I think it has a good chance to pass.But what I want to say is that, first of all, it’s important for California because there’s a big shortfall of federal funding for healthcare as a result of the One Big Beautiful Bill Act. And so California needs to find broadly a hundred billion in revenues to just preserve Medicaid. So that was the main reason for having this on the ballot in the first place. And so if it doesn’t pass, you’re going to see the number of uninsured people rise a lot in California. Under business as usual, it’s going to increase from six percent to ten percent. So that’s why it’s important.But more fundamentally, in my view, it’s important because it’s the one concrete measure that can begin to make a difference to oligarchic wealth and power.And don’t get me wrong, five percent one-time is not enough, but this is what’s going to pave the way, I think, for eventually some kind of federal wealth tax and federal annual wealth tax. And the reason why there’s good reason to view it like that is because this is what happened for the income tax at the beginning of the 20th century, which was first implemented by a number of states, like Wisconsin in 1911, before becoming federal policy in 1913. So that’s why it’s really important. And I can tell you that the whole world is watching California. I think people in France are like, “This is amazing! Go California, tax the billionaires!” And this is going to be a blueprint for what we’ll do in France, in the rest of Europe, and frankly, globally.Krugman: States as laboratories of anti-oligarchy. Let’s hope for the best. Thanks a lot, and onward with the project. Take care.Zucman: Thank you so much, Paul. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Oligarchy and the Media 22.07.2026 14minFor all my interviews and more, subscribe on YouTube.TranscriptGood news. The second richest man in America might be prevented from taking over CNN. That's the good news. The bad news is, aside from thefact that he probably will manage to pull it off anyway, the bad news is that that would be only a small piece of the ongoing takeover of U.S. media by oligarchs. And in turn, the media takeover is just part of the extraordinary exercise of power by the extraordinarily wealthy small number of men who have been wreaking so much havoc with America as we know it. Hi, I'm Paul Krugman. Doing a video today, because I didn't feel like doing a usual chart-heavy, analytics-heavy post, but very much on a topic I have been writing about and will continue to write about, which is the rise of oligarchy in America. Now, I know some people balk at that. But we're not talking about some kind of hidden conspiracy. We're not talking about the Protocols of the Elders of PayPal. We are talking instead about stuff that's largely out in the open, though not fully understood, which is the way that an incredibly wealthy small group of men, mostly men, is able to commandeer a lot of the political life of a country that is still nominally a democracy. And that's a fundamental story for our time, maybe the fundamental story. How does that takeover work? Well, there is what I think of as the middle level, which is the place where it's most easily quantified, tends to get most of the attention, which is campaign finance. American campaigns are very money intensive and have become more money intensive because we've opened the floodgates with Citizens United. And a lot of that money comes from a very small number of incredibly wealthy people. According to the New York Times analysis, about 20% of all campaign contributions in 2024 came from 300 billionaires and their families. That's a pretty big impact. A country of more than 300 million people, and 300 billionaires are a fifth of campaign finance, and surely more strategic, more targeted than the average donor. So that's really a very, very large role just in that direct sense of who pays for campaigns. But that's not the only level. There is a lower level, lower in the sense of morally lower, I guess, which is just plain buying politicians, buying policies, paying for the policies you want with cash or crypto on the barrel. There has always been some of that in our system, but it was normally discreet, indirect, deniable, the revolving door. It was the case even more than 20 years ago that when the Bush administration pushed through a Medicare bill that was very favorable to pharmaceutical interests, that the then chairman of the House Ways and Means Committee, who basically engineered and steered the bill through Congress, then promptly retired and became the chief lobbyist for the pharma lobby. So this kind of thing has been going on for a very long time. But now it's just blatant, out in the open, and the sums are massive. We just have literally billions of dollars thrown at the president and his family. No doubt large sums to other government officials, large sums to at least some members of Congress. So just plain buying the policies you want — and it’s not just that a large share of wealth is held by a small number of people, but that those are the people who are best positioned to really deploy their wealth to corrupt the system. There's also something, I guess you can call it a higher level, which is what military strategists call shaping the information space, which occurs at a couple of levels. One of them is the promotion of ideas and ideology that serve the interests of the very wealthy. You see that on many issues. You certainly see it very much on economic policy. If you ask, why do people still go out there saying that tax cuts pay for themselves and that tax cuts on the rich are an enormously powerful tool for stimulating economic growth? That's been tested to destruction, and it just ain't so. But it's a zombie idea. It keeps shambling along, eating people's brains, even though it should be dead. And the reason is, well, there's a lot of money in it. If you Google something I've written on, more often than not, when I do that, the top sponsored post at the top of the search page is an attack on me sponsored by some right-wing organization. And if you ask who supports those right-wing organizations, well, guess who. And it’s equally or worse the case in climate science. Scientific journals have been pretty good at not publishing climate disinformation. But when they do publish things that are somehow skeptical, or usually not outright denial, but attempting to sow discord about climate change, what percentage of those studies have received financial backing from fossil fuel interests? The answer is 100. It's all about the money. So this is, again, this is not new. Upton Sinclair: “It's difficult to get a man to understand something when his salary depends on his not understanding it.” So that has always been the case. But now we have something which is really, really important and is another level of this, which is the takeover of the media. So, okay. Ellison, or the Ellison family —because nominally this is Ellison's son in charge of Paramount — has already acquired CBS and has hired Bari Weiss to basically corrupt and destroy that network. If the deal for takeover of Warner proceeds, then CNN will get the same treatment. I'm finding CNN a very good news source, just braver at taking on what's really happening than my old employer, the New York Times, which is a great news organization and may be more necessary than ever, but tends to be cautious — and CNN is a little bit less cautious. But anyway, if he gets away with it, then CNN as we know it will almost disappear. It will almost turn into Fox News. Now, that won't be a profitable venture. There's already a Fox News, and so creating another one is not going to actually produce a lot of profits, if any, but that's not the objective. This is buying influence. Elon Musk, of course, took over the app formerly known as Twitter. Which was already becoming a more difficult place even before its takeover. I used to have, I guess, I think I had 4 million followers there. But it was impossible. I had to shut off comments because of the cesspool that Twitter had become. But now it is really by design. It is heavily tilted. That can be quantified. The algorithm really tilts it towards right-wing stuff, promotes really rabid racist views. And unfortunately, the network effects, the centrality that Twitter used to have, still keeps a lot of people on X, where they are influenced: people's views change. And also something that I don't know how to quantify, but it's very obvious if you follow and pay attention to people's positions, is that people who spend a lot of time on Twitter, elites who spend a lot of time on Twitter, start to think that the views they hear there are representative of where the country is — which they are not. But it does, in fact, tilt policy, tilt understanding to the right. The third richest man in America is Mark Zuckerberg, who made his billions from Facebook. Facebook is old-fashioned: I don't know anybody who uses Facebook. But I know that lots of people do. And it's still a very important information source and has, again, been tilted. On most of these media things, it's not as blatant as what Musk is doing at X. But it still has a big influence in changing the tone of the discussion and biasing the discussion towards positions that favor the interests of billionaires as well as favoring their prejudices if they happen to be, like Musk, authoritarian white supremacists. Okay. And the fourth richest man in America is Jeff Bezos, who purchased the WashingtonPost. I think he purchased the Post initially out of a belief that he was going to enhance his prestige. It certainly looked in his initial tenure as if this was actually more of a vanity purchase than a political purchase. But a billionaire is going to billionaire. And so he eventually shifted the Washington Post's editorial policy hard right, eviscerated the news division. There are still some brave, plucky reporters doing good reporting there, but it's a shadow of what it used to be. And of course, it's not at all the institution of Katherine Graham and Ben Bradlee, not anymore. So that's another challenge. What do you do about this? Obviously, one does what one can to try to limit this takeover of the information environment. And so we have the suit brought against the attempted purchase of Warner, hence CNN, by Paramount, hence Ellison. And that might succeed. You might think, well, if it's delayed, then what are the chances of actually ruling it out? Except that apparently there's a bit of a financial clock ticking for Ellison, who really has extended himself pretty far. So that's possibly going to block it, and that's good. It would have been great if someone had found a way to keep Musk from destroying Twitter. So you can look for solutions to immediate threats. But you're not going to hit all of these balls. And so the constant pressure towards a takeover of the news media, constant pressure towards a takeover of the general information environment by a handful of billionaires, is not going to go away. The constant threat or reality of corruption of the government by billionaires is not going to go away. Maybe once Trump is gone, it'll become less blatant, but it won't go away just because someone more discreet takes office. Even if we have an honest president, which in the current environment, I'm sorry, does mean a Democrat, but even if we have an honorable president, the corruption of the system will still be a continual threat because of all the money flowing around. So in the end, the only way out of this, the only reasonably durable solution is to not have so much wealth at the top. If you don't like what's happening to our institutions, if you don't like what's happening to the media, if you don't like the corruption of government, if you don't like the overwhelming of campaigns by big money with nefarious ends, the only lasting solution is to reduce the amount of wealth at the top. Woodrow Wilson: “If there are men big enough to own the government, they're going to own the government.” If we're going to have that much money in the hands of a few hundred people, and in the case of the real top of it, just 15 or 20 people, then you're not going to be able to maintain a truly democratic system of government. Oligarchy is not the only thing wrong with America. It's not the root of all evil. But it's the root of a lot of evil. And until we bring that concentration of wealth at the top down, we're going to be fighting a constant rearguard action trying to save some of what America is supposed to be about. Have a nice day. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Lina Khan on AI and More 18.07.2026 37minLina Khan, who chaired the Federal Trade Commission under Joe Biden, is one of the smartest and most influential thinkers about antitrust in our high-tech era, and one who has blazed new paths in policymaking. I spoke with her at a Graduate Center event back in March, and caught up with her again earlier this week for another enlightening conversation.For all my interviews and more, subscribe on YouTube.. . .TRANSCRIPT: Paul Krugman in Conversation with Lina Khan(recorded 7/14/26)Paul Krugman: This week, I managed to get to talk to Lina Khan, who was the incredibly influential and smart head of the FTC in the previous administration—with the current administration doing everything it can to undo her work. She played an important role in the Mamdani transition team and has had a lot of smart thoughts about technology and policy right now. And I thought we could talk for a bit about this, well, it’s always a bizarre moment these days, but this is the bizarre moment we’re in. And so, hi.Lina Khan: Hi, great to be here.Krugman: I want to get into technology and AI, but I wanted to just start with something that just happened. One of your special causes, which is “Click to Cancel,” which you tried to get as a national policy, just went through in New York City. Can you talk a little bit about what was achieved here and why?Khan: I’d be happy to. So, last week, the Mamdani administration announced that they are moving forward with two consumer protection initiatives. One was the finalization of a “Click to Cancel” rule, which basically says that businesses have to make it as easy to cancel a subscription as it is to sign up for one.This rule is responding to the fact that we’ve seen a pretty significant pivot to service-based revenue, and more and more companies are relying on subscriptions as a regular business revenue line. And that has created an opportunity for firms to create a lot of friction when people are trying to unsubscribe. A lot of people can relate to situations where it’s very easy to sign up, or sometimes you’re enrolled without even your full knowledge or consent. But then once you try to cancel, companies can make you jump through all sorts of hoops. Maybe you signed up with one click online, but to cancel you have to phone somebody, except the hours are really restricted or there’s nobody there to pick up the phone. In some instances, you may actually have to go in person.When we were at the FTC, we got thousands upon thousands of complaints, and people shared how, even during the pandemic when they were looking to cancel their gym membership, some gyms required that they go in person even after they had left the state. So this has been a growing problem, and people lose real money from it. I mean, there are estimates that, in New York City alone, people could be collectively losing over $160 million a year. So this rule, which is going to go into effect in October, is an incredibly important step forward.The administration also announced that they’re going to be proposing a rule to tackle junk fees. These are the fees that oftentimes show up at the very end of a transaction, even though they were not reflected in the original advertised price. Sometimes they’re called convenience fees, service fees, or amenity fees. And these are non-discretionary; people have no choice but to see them included. Companies will, again, often not advertise them on the front end, which is both deceptive for consumers but also gives them an unfair competitive advantage, because honest businesses that are marketing the all-in price then lose business to those firms that instead do pricing where they market a lower price and then add all the additional fees at the end.So, I’m really thrilled that the Mamdani administration is moving forward on these two initiatives, especially because we have seen some very serious backsliding at the federal level, where consumer protection initiatives have either been abandoned entirely or powerful companies that have connections to the White House can basically pay their way out of legal accountability. And so it’s incredibly important to see cities and states fill in that gap.Krugman: I couldn’t actually quite figure this out, but there’s this other initiative from Mamdani: public interest technology. Are you involved with that?Khan: It is something we considered during the transition and wanted to set up the administration with the option. But, yeah, this is basically... they will be creating a team that is going to be laser-focused on improving service delivery—technological service delivery, digital service delivery—to New Yorkers. And so there are all sorts of online portals that people have to interact with that are not really optimized; really important city websites that are still optimized for desktop, and when people try to use them on their phones, they break down. And so there’s going to be a lean team of technologists designed to go in and make sure that across city services, people are having a good experience and that these things are easy to use and functional for people.I would say the effort has some analogs to what was done at the federal level with the U.S. Digital Service, which was a team in the White House of technologists back in the Obama era. When I was at the Federal Trade Commission, we similarly brought in a team of technologists, and we’ve seen that, especially as more and more commerce goes online, and more and more government services go online, it’s incredibly important to have technologists on board designed to make sure that these things are easy to use and well-functioning.Krugman: I’ve seen a couple of areas where essentially governmental functions are initially done by trying to buy off-the-shelf technologies or bring in Microsoft or whatever. And I know of at least a couple of examples where it was a huge improvement just getting their own people because they kind of knew what people actually needed. So, I don’t know if you’re thinking along those lines or where it goes.Khan: I think you’re right that it does get to this deeper issue of what does it mean for the government to have capabilities and to actually build those capabilities in-house. I think we’ve seen various eras where the government will largely rely on outsourcing, relying on various consulting firms. And there’s a first-order question as to whether the government is really getting a good return on investment there. I think we’ve all seen the news stories about New York City having paid millions of dollars to McKinsey to produce a report saying, effectively, “Put your garbage in garbage cans.”But beyond that, I think over-reliance on outside consulting firms can also deprive the state of building in-house state capacity, which can be incredibly important for the long term. And so, again, I think the administration, through bringing some of these functions in-house, is also going to be investing in those long-term capabilities within government.Krugman: Yeah. I’ll give you, just quickly, my own example. There are bigger ones, but everybody doing sort of macroeconomics now is utterly reliant on this thing called FRED, the Federal Reserve Economic Data, from the St. Louis Fed, of all places. And the thing is, they did not outsource. They just asked some of their own people, who actually knew what working economists needed, to produce a website that is really optimized for people like me, and that’s just incredibly helpful. I assume that there are many, many examples where that could be done.Khan: Yeah. I mean, the other risk that you create if you are entirely dependent on some external actor is that a single business decision can render some of those products useless or severely degrade the capability overnight, or it turns out that there’s a new subscription and so there are all these additional costs. And so, either diversifying those inputs or creating more in-house capability is important insurance around some of that private power.Krugman: Okay. And New York City would certainly be among the world’s 20 largest economies so this is not a small issue.But these days, everyone is talking about AI all the time, in terms of the economics and a lot of political stuff. You were doing a lot of work on AI at the FTC, and you have written quite a lot since. I wanted to pick your brain a bit, but why don’t you tell me where we were going before the change in administrations on AI policy, and we can move forward from there.Khan: At the Federal Trade Commission, we were really focused on both the competition implications of artificial intelligence technologies, as well as some of the protection implications. On the competition front, we were really focused on, first of all, understanding: what is the stack? What is each layer of the AI supply chain of sorts? And how do we make sure we understand what each of the economic properties are across the board?And so you have the chips, you have these hyperscalers, you have cloud infrastructure, you have these models, and then you have various apps and services built on top of those models. And what we’ve seen in other markets, including Web 2.0 and in digital markets, is that it can be very easy for one of these layers to become monopolized because of certain network effects, and because of economic properties that lend those markets to tip quickly. If you allow monopolization without additional rules—such as common carriage or requiring equal access on equal terms—it can really result in other layers and other markets similarly becoming monopolized or otherwise becoming distorted, rather than principles of open and free and fair competition being really what’s allowing more of this economy to thrive and develop.And so we were really looking at the AI stuff through that lens, trying to understand: are we already seeing certain layers where there are bottlenecks or gatekeepers emerging, and could that undermine fair and free competition in other layers in ways that could deprive the public of the full promise and innovation of some of these technologies? And so we had various investigations underway based on what we were hearing from market participants. But at the end of the day, we wanted to, again, make sure that inasmuch as this is a technological inflection point, there could be a lot of opportunity. How do we make sure that the best ideas have the opportunity to win, rather than existing gatekeepers using their power to basically pick and choose winners and losers in a way that results in more self-interested outcomes for them at the expense of the public and for the market as a whole?At that point, we were hearing various concerns about Nvidia and various ways that they had become a core gatekeeper. We’ve heard concerns about the hyperscalers and ways in which firms that run cloud computing could be getting privileged access across the AI supply chain. And so those were some of the types of concerns that we were hearing at that time.Beyond that, we were looking at potential consumer protection abuses of these technologies, ranging from abuse of people’s personal data. For example, with more and more AI firms looking to train their models, they’ve become even more hungry for data, including people’s personal data. And so we were starting to see things like Google [Workspace] or other types of service providers sometimes changing the terms of service, saying that they could now use the content of, say, people’s inboxes or their Google Docs to now start training their models without attendant protections for people’s data. And people had not been setting up their inbox or writing emails in a way where they were anticipating that suddenly a company like Google could be using all of that for training data. And so we made it very clear that these types of after-the-fact changes in terms of service could, in some instances, be illegal.We were also focused on ferreting out how some of these AI tools could be turbocharging fraud and scams. And so we were already seeing at that time: an uptick in complaints around things like voice cloning fraud, the way that some of these AI tools can be used to mimic somebody’s voice. You call somebody’s grandparent, pretend their grandkid is in distress and needs thousands of dollars wired over immediately. We were seeing this as a growing vector of fraud that people were starting to lose a lot of money to. And so we wanted to make sure, at the very least, that these companies knew that the existing laws on the books, both from an antitrust and competition perspective as well as from a data privacy and consumer protection perspective, still applied.Sometimes in Washington, there can be a pattern where firms try to use new technological moments to argue that existing laws are invalid or out of date and don’t apply. And we wanted to make sure there was no misunderstanding about that—that the existing legal tools in place absolutely applied.The other thing we heard on the competition side was this issue of “interlocking directorates.” We were seeing a lot of AI partnerships and a lot of investments, famously Microsoft and OpenAI, and a whole bunch of other ones between Google and Amazon. And there was a lot of murkiness around what were the actual terms of these partnerships and investments, and could some of these investments, in turn, give outsized control to some of the existing monopolists over competitively strategic decisions? And so that was another area where we were looking under the hood to try to understand what’s really going on here in terms of these financial relationships.Krugman: Going back into history, the trusts that originated “antitrust” as a term... that was kind of overlapping, interlocking control. It was basically when you had the same people overseeing many companies. I’m perhaps doing violence to the history here, but am I right?Khan: Yeah, that’s right. The trust referred to basically a form of corporate control where this trust vehicle would basically roll up various entities and have financial control over various enterprises.Krugman: Yeah. And the Standard Oil trust was the most famous, but by no means the only one. And did you have specifics about the kinds of laws that they wanted to put by the wayside? I mean, I’m sure, but just give it a little concreteness for us.Khan: Yeah. I mean, I think one of the legal issues that is still percolating is this question around copyright. A lot of these models have been trained on existing information that is online, but much of that information has copyright associated with it. And so we would also hear from a lot of authors, artists, graphic designers, and people who produce content for a living who said they woke up one day to find out that this model had been trained on their life’s work and was now suddenly spitting out content in some instances that was competing with them. And yet, it was trained on them. And then because some of these firms controlled how search results are listed, they were now losing business to the AI version of their work.And so there are some really serious, meaty legal issues embedded there around unfair competition and copyright. This is an instance where, in existing litigation, some of the AI companies are arguing for “fair use”—that they were basically able to scan and train on all of this information because it was effectively in the public commons. And so some of these issues are still being litigated.But it’s really important to think about what the long-term incentives will be for newsrooms, for example, to still invest in news production and investigations if they’re not able to actually recoup their investments because it’s then just being swallowed up by some AI model. And so there are some serious long-term questions here around whether we are structuring our markets and structuring compensation structures in ways that are still going to incentivize the production of news or information content that we, as a society, decide is valuable.Krugman: Yeah. One thing I’m hearing from people in the news business is that the rise of AI in search is sort of suppressing links. Instead of getting a link to the deep investigative report by The New York Times or Bloomberg or whatever, you get an AI summary of what was in it, and people never go to the links. That’s the kind of thing, I guess, we’re worried about in many domains.Khan: That’s exactly right. And this is something that we had been seeing with Google even before 2022 or 2023, where they were giving privileged search results to some of their own vertical products in reviews, maps, or other types of search and travel verticals. But this problem is now being turbocharged, precisely for the reason that you said, and some of the statistics that are coming from publishers around just what a dramatic drop-off there has been in terms of search traffic to some of these publishers’ websites is just staggering.And so we see: before, Google used to be a turnstile to the rest of the web, where Google was the starting point so you could get to other destinations. And now, especially with more of these AI tools summarizing what’s on other websites and keeping people just within Google’s ecosystem, it’s depriving all of these other publishers of the traffic and oxygen that they would need to continue being financially viable, even as those other publishers and producers are the ones that are creating the information and the content in the first place. And so I think these are going to be some serious challenges.Krugman: Yeah, this is something where people that I know fairly well are actually quite seriously scared that their financial models are being undermined at lightning speed. One thing you can say about AI is that whatever is happening, it happens really fast.Okay. The particular thing that got me wanting to do this interview was an Op-Ed that you published in The Times, I guess soon after leaving the FTC. That was February 2025. Although when I looked and saw that that was the date on it, I was shocked because, in my memory, it was so prescient that it had to have been written like late last year. But it was actually written at the beginning of last year. It was under the headline, “Stop Worshiping the American Tech Giants.” Can you summarize what you were saying there? Because it does seem incredibly relevant to where we are right now.Khan: So, this was a piece that I wrote looking at the history of innovation in Silicon Valley and noting that, historically, the most paradigm-breaking innovations have come from markets that have allowed for real competition and allowed for new ideas to come in, get funded, and then to be able to really break into the market and compete on the merits of whether businesses or consumers like their products and services, as opposed to markets where you have gatekeepers basically deciding who gets to enter and who doesn’t get to enter.And so I was noting in the piece that at this moment of growing investment in AI, we would do well to want to double down on that commitment to competition, rather than allowing the monopolies and incumbents of Web 2.0 to be the ones that get to decide who gets to come into this market and who gets to compete or not.One of the catalysts for my writing this piece was the emergence of DeepSeek. This was an AI firm that originated in China. And it really shocked Silicon Valley and Wall Street when its model was rolled out, because it mirrored or rivalled the sophistication of American models but was able to do that with much more efficiency. And it really, I think, was a wake-up call from where I sat as to what it would mean to allow the American giants to just control these markets and innovate on the trajectories that they were determining, rather than allow for real competition.And I think with the American AI giants, there’s this additional question around conflict of interest. Again, some of these very firms—the Microsofts, the Amazons, the Googles—have their own cloud computing businesses. And inasmuch as these AI models are heavily relying on cloud computing, I think there’s a question to be asked as to whether these firms are going to have the right incentives when it comes to wanting AI models to be efficient, if they are simultaneously making a lot of money from models that are not efficient. And so I think the DeepSeek revelation was something that brought that conflict of interest to bear.Krugman: I sometimes hate that everything gets formulated in terms of competition with China, but at least part of the issue now is the idea of “national champions”—and we get to that in a minute or two—but that they are arguably, at least, putting us behind in competition with China. And then again, a lot of that has come to a head recently. People started to say, “Oh my God, we’re spending too much on tokens,” and a fair bit of turning to Chinese models. And that’s a huge move. And that was why, when I look back and read your piece, the date just popped out at me. I can’t believe you wrote that 18 months ago.Khan: Yeah. I mean, I think you’re absolutely right. And there are some real historical parallels here when it comes to certain technological companies insisting that these markets are inevitably going to be monopolistic, and therefore the government should treat them as “national champions” and support their monopolization.The piece also mentions Boeing as a cautionary tale here. There was a merger in the late 1990s that the U.S. government approved, where we allowed Boeing to buy up their last U.S. rival, McDonnell Douglas. And that merger, and what followed, basically has led us down a path where you then had Boeing’s planes falling apart, and people have died. And I think it’s unfortunate to have to admit that the lack of competition there probably played a role in Boeing not having to invest as much. There were other factors in terms of the culture internally—moving away from one that focused as much on engineering to instead one focused more on a McKinsey-type culture based on consulting—but I think we’ve seen how a lack of competition in some cases has really major consequences.Krugman: Yeah. This is one of the things which I love about your analytical work: the interplay between the cutting edge and history. Because everything is new, but on the other hand, we’ve been here before. And I thought that the Boeing example, as how things would go wrong, was a little bit revelatory.I know that you have a bunch of other things on your plate, but to the extent you’re following AI—and you may be following it more closely than I would imagine—where are we in that process now? Has the U.S. AI sector managed to get sloppy with monopoly already? I mean, everything now seems to happen at ten times the historical pace.Khan: I think there are going to be some new openings for potentially having more competition. I think, even with some of the more open models, you’re seeing that they can themselves be an input into more competition. And historically, we’ve seen that with open source—there are a lot of committed people around it because they believe the philosophy, but open source as a business model can also be enormously lucrative because it can just really catalyze innovation. And so I think making sure that we still have a vector and markets that are going to be built around that openness is going to be incredibly important.I think this issue of conflicts of interest is one that we need to take seriously and think through. Does it make sense to have the vertical integration that we do? Vertical integration can have, no doubt, various types of benefits, and there are sectors where having markets vertically integrated in that way can make a lot of sense. In markets where you are going to have one layer or multiple layers—the bottleneck layers, new layers where you have a lot of consolidation—allowing market participants in those gatekeeper-monopolized layers to also have a presence in layers that actually should be competitive. There’s nothing about economic properties that require those layers to be monopolized. But that’s when I think you can see a real problem. Because then you allow the monopolies to export their control and their consolidated power up and down the supply chain, distorting competition and distorting the trajectory of innovation.And so I think that’s the kind of prism through which we really need to look at the AI stack, along with these questions of efficiency. And what are the underlying incentives here? Do we have the right incentives when it comes to wanting to promote more efficiency with these models?Krugman: Right. And getting back to your example, at least as I understand it, if you have big players, either directly or with substantial ownership stakes, who are also in the business of selling compute, essentially they have no incentive to help the models use less compute—even though that would mean less environmental damage—and also have an incentive to favor profits there that are inefficient. And possibly, given that we do have a global economy, losing ground to rivals. Am I garbling this, or is that kind of how it is?Khan: I think that’s right. I mean, the other thing is these AI technologies and advances are coming against the backdrop of markets that had already been monopolized, right? There are major litigations against Google, which has been found to be a monopolist three times over, and against Amazon and Apple. And these are companies, especially when it comes to Google and Apple, that already have very significant control over key portals and over key distribution points.So, the way that most people interact with some of these AI models is through technologies owned by some of the existing gatekeepers—be it Microsoft, Apple, or Google. And so with those firms in particular, and especially Google and Microsoft which have invested more in AI, that’s where we also see potential conflicts of interest. We’ve already seen Google’s share of some of these markets go up because they’ve made such an aggressive push to use their existing monopolies in areas like Chrome and Google Search to make sure that it’s their AI services that get a leg up.Krugman: Yeah. Just a quick sociological observation—this is striking. I remember in a way that hopefully you don’t, but the dot-com era: that was all the scrappy young guys in their garages, and this is all giant corporations—the already giant corporations, and guys who made their decabillions 10 or 15 years ago. In some ways, I almost sometimes feel like the AI investments are kind of a plutocrat midlife crisis playing out.Sorry, but last point on this: One concern I have about the view of national champions is that we end up with—and I think you expressed this as well—having national policy directed to protect these incumbents, these players, even when they don’t have the right stuff. And now with talk of the Trump administration taking a stake in things, how big is that in your view?Khan: Specifically the concern around state control?Krugman: Well, not so much state control as that maybe if the Chinese have a better model, we start saying, “Oh, no. National security. It can’t be used here.” Or if there’s a smaller player that has a better model, that somehow or other there will be federal contracts, federal rules written to favor the big players who help pay for ballrooms and stuff like that.Khan: It’s a huge concern. I mean, it’s no secret that the CEOs of some of these technology companies have made it a top business priority to curry favor with this White House. They were all sitting there on the stage at the inauguration. They all make regular pilgrimages to the White House, to various state dinners. And so I think there’s a very serious risk of capture—a very serious risk of regulatory decisions being made in ways that are not serving the public interest at large or serving competition at large, but instead are serving the narrow private interests of a very small number. And so I think those are very serious risks.We’ve seen some debates in the White House and some policies that are veering in this way or that way. It seems like initially the White House had a very hands-off approach when it came to AI, and then they’ve started to take more interest in some of these specific models and where and when they’re being released. But I think, from a competition perspective, there is a very real risk that we’re going to see the biggest, most powerful incumbents, through their access to the White House and politically powerful individuals, be able to get rules and regulations that are personally favoring them and personally advancing them at the expense of the broader market, in the sense of startups and newer firms that in some instances may have better ideas.I mean, this is an age-old debate: what are the underlying market conditions that best pay for innovation? Is it monopoly or is it competition? The famous Schumpeter-Arrow debate. And at the end of the day, it comes down to this question of what type of innovation you are trying to promote. The empirical evidence shows that monopolies can be good at innovating, but they are primarily good at innovating in ways that deliver incremental improvements on existing technologies. Historically, the breakthrough innovations and the paradigm-shifting innovations have come from outsiders and have come from a competitive market.And so I think that’s why it’s especially important, as we look down the inflection point of some of these AI technologies, that we’re not allowing extreme centralization of those systems, when it’s in fact openness and competition that have been such a key driver of American innovation and market growth.Krugman: Yeah, in your op-ed, you point out that, I guess, the fundamental, sort of conceptual breakthrough that made what we call AI possible all came from Google, which just did nothing with it. It wasn’t until people left that they brought it to other places, and it started to become what we now see all around us.Khan: That’s right. And sometimes if you talk to employees at some of these companies, they will note just the enormous amount of bureaucracy, an enormous amount of bloat and red tape that can start to hobble the ability of these bulking institutions to really deliver fast-moving innovations. And so that’s why you see that sometimes ideas that even came from within Google actually have to go outside to get the attention and space to really be able to deliver.Krugman: Yeah. One of the great myths of our time is that the private sector is being efficient and innovative and only government is bureaucratic and slow. But if you’ve ever worked for or know anybody who works at a large corporation, it just ain’t so.Okay, just an open-ended question: what competition issue are we not paying enough attention to right now? Just trying to think about all of that stuff going on. It’s so much AI-focused, but what else? What’s kind of nagging at you as you track what’s happening?Khan: Well, I think one question is the way that AI and continuing technological advances and sophistication will intersect with other markets that are already very consolidated. And so as we see more and more integration of some of these AI tools in areas like healthcare, for example, or in areas like retail, I think there is an opportunity for these technologies to move. On the one hand, they could make these markets more open; but on the other hand, they could actually result in even deeper consolidation.We’ve already seen a whole set of lawsuits noting how in areas like housing and agriculture, there is use of algorithms to facilitate price fixing and collusion. Because where you already have a lot of concentration, these tools can basically make it easier to collude, or make it easier to collude with more precision and sophistication. And so I think the intersection of AI and technology with the rest of the economy is going to be an area to keep watching.Krugman: All right. Brave new world and really kind of alarming. I wish you were still in the federal government. But you’re by no means out of public policy. So thanks for talking.Khan: Thanks for having me. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 The Forever War Gets Scary 15.07.2026 6minFor all my interviews and more, subscribe on YouTube.TranscriptThe war with Iran has just reached a very scary phase, and I’m not talking about the bombs and the drones. Hi, Paul Krugman here, doing a brief podcast instead of a full post, because I actually spent the day with friends and doing other things, and this is a quicker alternative.If you’re following the news, you know that the sort-of ceasefire with Iran has been called off. Trump has reinstated the blockade. The Iranians are back to hitting things with their drones and missiles. The U.S. position has been wildly erratic. First, Trump said he was going to impose a 20% toll on all shipping, basically turning the Strait of Hormuz into a U.S. toll booth, which would have been wildly illegal and irresponsible, aside from being impossible. Now he says, no, he’s going to demand that countries invest in the United States, which is also actually wildly illegal. But in any case, it’s never going to happen.And yet, this is extremely scary. The reason to be afraid is not that I think the war is going to come to America. It’s not even that I think the United States is going to seriously try to occupy Iran. We don’t have the troops. We don’t have the missiles. Trump depleted a large share of our weaponry in the course of his failed war so far. So this is likely going to be punitive strikes, maybe some war crimes along the way, but that’s all.But what is really frightening here is that it does appear as if Trump has given up on trying to extract something that looks like victory. If we go back just a few days ago, it appeared that what was going to happen was that Trump was going to de facto pull out, give upon the project, take advantage of falling oil prices because the strait was sort of kind of open — and try to spin the story about this was truly, this was actually an American victory and the economy is great and look at the stock market. And, you know, just it was a little bit — more than a little bit —stupid and doomed. It was also kind of amazing because a serious attempt to end the conflict would have required facing up to reality, saying, OK, this war didn’t go well, but America remains great. Sorry about that.But that was apparently not something Trump emotionally could bring himself to do. He just cannot admit that this venture failed. He can never admit that anything failed. We’re going to be searching for the saboteurs of the reflecting pool for the remainder of his presidency.This is a change in strategy that is ominous because what is Trump’s plan for the midterm elections? Here the idea presumably was that there would be enough economic success and people would have sufficiently short memories that they would possibly give Trump credit for opening the Strait of Hormuz, but in any case have put the gas price shock and the whole disruption surrounding the war behind them. And be ready to start admitting that this is the golden age that Trump and company keep on claiming it is.Now that’s all off. Now it’s just we’re going to bomb Iran. No clear strategy there, but we’re not going to even pretend that things are okay. We’re going to blockade them, which actually has a little bit more leverage, but no hint that anything might be resolved in a way that would help Republican chances in the midterms. So what is going to happen?I don’t think it’s a coincidence that just as Trump essentially gives up, not gives up in the sense of abandoning his war, but gives up on trying to achieve anything he can even spin as a positive outcome, that we now have an announcement that this Thursday he’s going to have a primetime speech, which reports say is going to be about election fraud in 2020. Some reports hinting that he might try to declare the two Democratic senators from Georgia somehow illegitimate.Okay, that’s not going to actually work. And nobody’s going to be convinced by the claim that he actually won the 2020 election. But what is happening is that effectively he’s setting up the pretext, the groundwork for massive interference in the vote this November. That we’re basically seeing the stage set for some kind of attempt to block fair elections, maybe block elections entirely.I don’t know how this is going to play out. But we are really now at the point where it’s pretty clear that Trump and the people around him have given up on actually winning the election. They’ve decided instead that somecombination of propaganda, misinformation, disinformation, and possibly massive illegality is their way forward.And don’t say they wouldn’t do that. That has been famous last words every step of the way. The proposition that there were some things that even Trump and company would not do has been the best way to be wrong about everything, every step of the Trump administration.So in a peculiar way, the fact that Trump is back to bombing Iran is really bad news, not because of the bombs. Yes, it’s terrible and all that, But not because I have any real fear that America is going to be at risk from a foreign power, but because I think it signals an enormous risk to us from our own president, our own government.Be afraid, be very afraid.And take care. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 Dennis Kelleher of Better Markets 11.07.2026 54minFor all my interviews and more, subscribe on YouTube.With everything else going on, the ongoing demolition of financial regulation and supervision, which is raising the risks of financial crisis, isn’t getting much attention. So I spoke with Dennis Kelliher, president of Better Markets, an independent think tank that is trying to sound the alarm.Full disclosure: my nephew works at Better Markets. But I would have wanted to talk to Kelleher regardless.. . .TRANSCRIPT: Paul Krugman in Conversation with Dennis Kelleher(recorded 7/10/26)Paul Krugman: Hi everyone. It seems hard to believe now, but the great financial crisis of 2008 and its aftermath are now in the distant past. I think, in fact, in November there will be some voters who weren’t born yet. But for some of us, it was a huge, defining event, and financial markets as a source of economic problems and instability hasn’t gone away. And I thought I would talk with Dennis Kelleher, who is the head of Better Markets, an independent think tank devoted to trying to make financial markets work better for the rest of us. And in the note, I’ll mention I do have a personal connection to Better Markets, but that’s not why I’m interviewing Mr. Kelleher. Dennis is a former Senate aide, and as you know, congressional staffers are one of the great sources of expertise in America. And we want to talk about financial markets, so hi.Dennis Kelleher: Hi. Thanks for having me, Paul. Good to see you.Krugman: Good to see you, too. I have a bunch of questions, but we can go wherever this goes. The first thing is, whenever I try to talk about financial market functioning, what comes up is that most financial assets are owned by a relatively small part of the population, even if you take 401(k)s into account. So why isn’t this just a fight among the investor class? Why should everyone care about this?Kelleher: Well, it’s a great question because there’s such a lack of information about financial markets, the financial system, and frankly, as you well know, the economy. You know, one of the great services that you and many of your colleagues have provided is basically translating what’s happening in the economy and financial markets to the average Main Street American, reader of the New York Times, and consumers of news. And the truth is that the financial markets and obviously the economy impact everybody, and you’re right.This November during the election, some of the people voting will not have actually had any awareness of the 2008 financial crash, which was the biggest crash in the United States since 1929, which caused the Great Depression. And even though they may not have been born at that time, the people who are voting in November are still living through the repercussions of the 2008 crash. We basically lost an entire generation of Americans, economically speaking, from that crash.It took ten years for the U-6, the broad unemployment rate, to return to pre-crash levels. It was 2017 before that happened. And indeed, the Fed did an interesting study, which people can quibble with the baseline, but they did a study in 2018 that showed at the end of 2016, 90% of Americans were poorer than they were in 2007 by 17 to 35 percent. So if you think about that, at the end of 2016, the best-off American in that ninety percent bucket was 17% poorer. Now you could say the baseline of 2007 was inflated, but by and large, 90% of Americans have been doing pretty poorly since the crash for a lot of reasons.And so in November, when those people go to vote, they might not know it but they are actually living through the continuing economic consequences, financial consequences, and actually political consequences. Because the rise of Trump and the dissatisfaction of voters, Americans, and actually voters in the UK and elsewhere—Martin Wolf from the Financial Times wrote a terrific book called The Crisis of Democratic Capitalism. It shows how if countries don’t deliver for the broad population, then democracy erodes and people look for easy answers, authoritarians, and strongmen. And we end up with Brexit, we end up with Trump.And so you’re right. People don’t remember the crash, but the crash is incredibly important to everybody in America. And the circumstances that we find ourselves in today are unfortunately echoing many of the drivers of that crash.Now, I didn’t answer your question about the investor class, but when you look at investors, something like 87% of the value of the stock market is owned by the top 10%. On the other hand, there are today $27 trillion worth of assets in 401(k)s and IRAs, retirement accounts. It’s overwhelmingly skewed to the top, but not only. And importantly, one of the great projects that America really needs to undertake is to democratize finance so that financial assets and the ability to grow wealth is more broadly spread out. One of the big crippling problems we have today is that the bottom 50% of Americans, about 165 million Americans, only have 2.5% of the wealth of the country. It’s astonishing, right?And so a big part of what Better Markets does in economic and financial policy making is to try and rebalance what we see as a rigged economy that’s driven by a rigged and broken financial system. So our economy is producing very well for the top ten percent, and our financial system is structured to deliver those results. Now, part of that is wealth extraction, but a lot of it is just structural drivers put in place by policy makers in Washington that cater to the top ten percent. And that, unfortunately, Paul, as you know, is on a bipartisan basis.Krugman: We’re gonna get into that in a bit, but let me just ask a question. I’m gonna actually kind of veer off course, although this is something I wanted to get to. Top ten percent. So basically, ownership of stock is, roughly speaking, a top ten percent activity. When you talk about skewed, I mean, I have a sense that it is actually increasingly skewed towards a fraction of a fraction. Do you have anything I should take away about how the system is rigged or skewed within the stock-owning population?Kelleher: Well, I think the problem is that the higher up you go on the wealth scale, the greater your ability to accumulate even more wealth in a tax-free fashion, right? And then to pass it along to both use it today as if it was cash and income, not be taxed on it, use it, and then hand it off through inheritance without being taxed to heirs for multi-generational wealth concentration at the top. It’s bad for the economy and bad for democracy.I mean, you’ve talked to Ro Khanna and there’s all sorts of people with different ideas about what to do. We’ve got a wealth tax on the ballot in California. But in terms of the structural drivers, one of the problems we see at Better Markets is that Democrats don’t pay enough attention to the financial structural drivers of the economy. So here’s just a simple example that people are often surprised by.Community banks in the United States—there’s about a little over four thousand of them. You see them on every corner across America, particularly in “real America,” as opposed to where you and I live, Paul, which is by no means real America. But those banks lend out seventy-five cents on average of every dollar of deposit. The big Wall Street banks, they lend out somewhere less than fifty cents of every dollar of deposit. And that’s because it’s so much more profitable for them catering to the rich, mostly engaging in financial activities, trading, and capital markets activities.And so ask yourself, why is that? Well, that’s because the rules enacted by the banking regulators and Congress and other regulators allow the profit margins on the financialized trading side to be so much greater than on the lending side. I mean, truthfully, the rules that are created in Washington actually discriminate against lending to the real economy.And so you have community banks which don’t have capital markets activities. They’re bread-and-butter banks for the most part. It depends on how you define community banks; some people define them all the way up to Wall Street, but those are people in the propaganda industry. But these are banks that are actually driving the real economy. So for example, the community banks have somewhere in the neighborhood of 10% of the total assets of the banking system, but they actually provide somewhere in the neighborhood of 40% of all loans to small businesses.Krugman: Right.Kelleher: Well, why are we not having rules that skew towards benefiting the real productive economy and away from the trading financialized activities which serve the very top one or two percent and not the rest? And actually, it not only doesn’t serve the rest of the country, it’s at the expense of the rest of the country. Better Markets put out a report showing that last year the growth in major Wall Street bank lending to what are called “non-banks” grew by 50%. Do you know what their lending to the real economy grew by? Zero. Zero. And so a lot of these activities are being pushed out into what are called non-banks because it’s more profitable. It’s more profitable because the rules make it more profitable. The rules are created in Washington by policymakers, regulators, and legislators who, unfortunately, too often are beholden to the wrong people. And so you end up with this cycle where the rules keep reinforcing the current structure that’s channeling activity and money to the top and away from Main Street.Krugman: So as I understood it, reading some of Better Markets’ reports, if you’re a big financial institution, lending to non-banks probably ends up being a roundabout route by which the money reaches lenders, but not through the original bank. They actually have kind of a regulatory advantage because it’s lower capital requirements. If I got that right?Kelleher: Well, it’s lower capital requirements, it’s lower requirements across the board. Capital is one of the core drivers, but it’s not the only one.Krugman: So if you put your money with Citigroup or another one of the big financial institutions, it’s not going to be lent out, or much of it will not be lent out to small business or households. It’ll be lent to others; it’ll kind of divert around and it’ll in effect be channeled into what you consider a worse way through which the money reaches the rest of the economy. Is that a fair summary?Kelleher: That’s a fair summary of part of it. Keep in mind a lot of this money is funding hedge funds doing big basis trades, basically swinging for the fences. I’m not saying there’s no value at any hedge fund to the real economy, but when you look at their activities, that’s not exactly what I would call beneficial lending to the real, productive economy. Private equity is basically a strip-and-rip business model. It gets their money from the banks. Almost everything goes back to the banks, and that’s because deposit money is the safest, soundest, and cheapest source of funding for economic activities.And so the banks have got the money, and what they decide is: where are they going to send it? Are they going to send it over here to lend to Main Street businesses where their profit margin is modest, or go over here to hedge funds, private equity, or other financialized activities—business development corporations, crypto, all sorts of things where the profit margin is large? They’re making rational economic decisions in their self-interest to profit maximize.The question is: why are the people in Washington structuring it that way so that their profit margins are like that? The current capital rules that we’re fighting about, Paul, are supposed to change that. And in fact, what they’re supposed to do is have, for example, the trading activities accurately reflect the risk associated with them. And if they accurately did that, the capital requirements for those activities would be much higher. Not only are the banking agencies with the Federal Reserve in the lead not doing that, but when they’re done with the proposed capital rules, capital at the biggest, most dangerous banks in the United States is going to be back to the levels roughly before what they were before the 2008 crash.I mean, think about that. It’s crazy, right? Here’s something that’s even crazier: a bunch of those big banks are going to have capital rules and capital levels that are roughly similar to community banks.Krugman: Which are low, because they’re in a very safe business, right?Kelleher: Yes. Well, right. The systemic risk to the economy of community banks, first of all as an absolute matter, is pretty low. But relative to the giants on Wall Street, they’re infinitesimal; they’re not even comparable. And we’ve got a Federal Reserve, particularly the Vice Chairman of Supervision and Regulation over there, that acts as if she’s the primary lobbyist for Goldman Sachs or JP Morgan Chase.She even hired three of Wall Street’s top lobbyist lawyers to be her senior advisors. I’m not making this up. One was a vice president at Goldman Sachs. One was one of Wall Street’s top lawyers at one of the top Wall Street law firms for 35 years. And the other one was a top executive at Wall Street’s biggest trade group in Washington. Those are her three top advisors.Krugman: Are you talking about Fed employees or outside consultants?Kelleher: No, they’re Fed employees. They’re on staff. We put out a press release about her hiring the three of them. I mean, this is not just the fox guarding the hen house; this is the fox in charge of all operations of the hen house. So the lawyer who was on Wall Street for 35 years, serving his clients for 35 years—all of the banks—is now the Director of Regulation and Supervision at the Federal Reserve of his former clients, and the right-hand top staffer for the Vice Chairman of Supervision and Regulation on the Board of Governors of the Federal Reserve. And so anybody who is surprised that the Fed is now enacting or proposing rules incredibly favorable to the biggest banks on Wall Street...And it’s not just capital, Paul. I mean, one of the tradeoffs here is that banks get to have a somewhat unique role in the United States, right? They get to accumulate all these activities and take people’s deposits. Main Street American deposits are how these banks fund themselves, largely. And then we insure that money through the FDIC so people have confidence that they’ll get their money back. But the exchange is: we regulate them so that they don’t actually threaten the economy and financial system of the United States because they’re so big. So that means they’re supervised.People don’t know this, but every day, people who work for the Federal Reserve and are paid by the American people, go to work at the biggest banks, supervising them. They literally have an office there. They go in, look at the books and records, and talk to people all day long at Goldman Sachs, JP Morgan Chase, and Citigroup. That’s called supervision. It’s basically invisible but incredibly important. But the Fed is not only cutting back on capital and regulation like stress tests and other important safety features; they’re also gutting supervision. And so they’re basically unleashing the biggest banks in the United States from modest, sensible regulation and supervision that’s supposed to protect Main Street jobs, homes, and savings from high-risk, reckless, and inappropriate conduct by these gigantic banks. We saw in 2008 what happens when you don’t regulate them or supervise them. And we actually just saw it again in 2023.Krugman: Right. This is 2023 with the Silicon Valley Bank and all of that, right?Kelleher: 2023 there were four big bank failures. Three of the four biggest bank failures in the history of the United States happened in 2023. People don’t realize it.Krugman: Even I didn’t realize that, and I’m supposed to be on top of these things. And this is happening incredibly fast, right? Normally we think you forget the lessons of the last financial crisis basically once people age out of the business and nobody is around who really remembers it. But we were dealing with the aftermath of 2008 just fifteen or sixteen years ago. And you’re saying that basically we’re fully back to that kind of Wild West, no-supervision world, or maybe worse.Kelleher: Well, we’re getting there, and the direction is there. We’re not quite there yet, but the thrust of what’s happening now is broader, deeper, and more reckless than it was in the years leading up to the 2008 crash. I mean, if you think about it, it’s quite amazing. The so-called shadow banking system—non-bank financial institutions—today is bigger than it was in ‘08 and less regulated.Krugman: That’s what I was going to say. Yeah.Kelleher: And it was identified as one of the primary drivers of the ‘08 crash.Krugman: That’s right. I mean, I remember very vividly in the fall of 2008, the conventional wisdom, even in textbooks—including my own—said, “Well, we can”t have a 1931-style banking crisis because the banks are insured and regulated,” and then the week of Lehman’s failure was, “Sixty percent of the banking system is shadow banks.” And you’re saying that we’re back to that and more now.Kelleher: Yeah, I don’t remember the exact percentage, but yes. And what’s worse is they’re less regulated today than they were then in many material respects. And now a lot of people think, “Well, it’s hard to worry about big catastrophic events when there’s a lot going on every day.” But this is happening fast, and because there’s so much happening in the Trump chaos machine—where there’s not a scandal a day, it’s like almost an hour.You know, J.D. Vance, who I almost never agree with on anything, said in a speech recently at the Nixon Library that if the Nixon crimes happened today, it wouldn’t even last a full news cycle. And he’s probably right. And so a lot of this is not only happening fast, it’s happening invisibly because just a very small slice of what’s happening is getting into the media. Meanwhile, the industry termites are working day and night in the policy-making process in Washington, eating away at the foundations of the financial stability of the United States.Krugman: You’ve been talking a lot about the Federal Reserve, which is critical because it traditionally has been the more competent, less politicized piece. And you’re basically saying that now that piece of the Fed has effectively been captured. Is that a fair description?Kelleher: The Fed has unfortunately been largely captured. It’s being run by people who have an agenda that is not consistent with the best interest of the American people, frankly. I’m not talking about the monetary policy side—that’s a whole different discussion—but on the supervision and regulation side, they are not acting consistently with the best interest of Main Street Americans. Wall Street is winning day in and day out in the policy fights.Krugman: Right.Kelleher: There’s going to be news coming out, I think, over the next several weeks, maybe months, that will illustrate that pretty starkly. It’s really quite astonishing what has happened at the Fed. And don’t get me wrong—there are a lot of good, hardworking, dedicated public servants at the Fed who nobody will ever see or acknowledge, who have been fighting the good fight for many years. But the leadership at the Federal Reserve at this point—the Trump leadership—is doing to the Federal Reserve what’s being done everywhere.Now, we know we had two big Supreme Court cases recently which supposedly cabined off the Federal Reserve from direct political control by the President, unlike the other agencies, and that’s true, but it’s all relative, right? I mean, he now has direct political control of the SEC, CFTC, and everything from the NLRB to the FTC to the FCC—all the critically important regulatory agencies that have been in place since the New Deal, basically creating and enabling an economy to be profit-maximizing but still have adequate protections for the public. I mean, that’s the balance that we need to get.And actually, a former colleague of yours, David Leonhardt, wrote a great book—and I always have it on my desk because I recommend it to people. It’s called Ours Was the Shining Future. It’s a great history of how the United States, post-Great Depression, built the largest middle class in the history of the world, really compressed gross income inequality, and created wealth in places people didn’t think it would happen. And he talks about how things changed when Reagan came in and kind of where we are now. But that was because we had a regulatory state.Now, people can argue about what’s reasonable—how much is too much, how much is too little—but we struck a balance that enabled the SEC, the CFTC, the Federal Reserve, and other regulatory agencies, from labor to health to product safety. That balance took some of the craziness off the blind profit maximization built within the engine of the economy.Now, the Supreme Court basically said last week that doesn’t exist anymore. What exists going forward is that the President gets to control all those agencies, and all those agencies are now subject to both the political agenda and the whim of whoever the President is.Krugman: So, for listeners who may not know: SEC is the Securities and Exchange Commission, which is supposed to regulate stocks and corporate accounting and all of that. CFTC is the Commodities...Kelleher: Futures Trading Commission, regulating derivatives and commodities. It’s the least known but a very important agency. For example, commodities: the bread in your lunch pail, the cereal in your breakfast bowl, the gas in your car, the heat in your home—all those markets are regulated by the Commodity Futures Trading Commission.Krugman: Yeah. And so Humphrey’s Executor, the case where the Supreme Court essentially said that Congress cannot establish a mandate and then expect an agency to fulfill it if the President doesn’t want to. That really affects all of these agencies, right?Kelleher: Right. Actually, the case last week was Slaughter v. FTC, and that case overruled Humphrey’s Executor, which was a Supreme Court case from ninety years ago. I don’t remember exactly; it could be eighty. Contrary to what my kids often think, I haven’t been around that long.Krugman: It’s ninety years ago because it was actually a ruling against FDR. FDR was trying to change something, and the Supreme Court said, “Well, that’s not what Congress said and you, Franklin Delano Roosevelt, cannot change it.” But now it’s been waived for Donald Trump.Kelleher: Yeah, well, look. We have a right-wing Supreme Court—a supermajority—that is essentially creating, for the first time in American history, an all-powerful executive branch. As you know, it’s been referred to by legal scholars as the “unitary executive theory,” where essentially the President, whoever they are, gets to control the entire executive branch. And of course, over the last ninety years or so since the New Deal, we’ve had an administrative state that has, in key respects, put some brakes on the worst excesses of unrestrained profit-seeking. They’re just basic public protections.I think of it as being like cars, right? Cars today are very safe; they have airbags, bumpers that are shock absorbers, glass that shatters and doesn’t kill you, and reinforced doors. What the Supreme Court is doing with Slaughter v. FTC and these other cases that are empowering the President is literally taking the airbags and bumpers off your car. Except the car, in this case, is the country. It’s our democracy, our economy, and our financial system. The safety aspects of that system that protect our democracy, economy, and financial system protect people’s jobs and savings.And frankly, their safety—even things like the Consumer Product Safety Commission or the FDA. These acronyms can get confusing, but what they really are are safety mechanisms and protections for Main Street Americans from things that happen in a gigantic economy like the United States that would otherwise have really bad impacts on Main Street Americans, whether it’s their job, their health, their safety, or their savings—frankly, their families and their dreams. And that’s what these agencies do; some do it better than others, and I’m not saying they always get it right. They don’t; they get it wrong. We criticize them all the time. We criticize them when Democrats are in charge and we criticize them when Republicans are in charge. We also praise them when they do well. But we need them; we need these shock absorbers on an otherwise unrestrained economy that’s just profit-driven, and that’s what we’re seeing now.Krugman: We’ve ended up talking a lot about the Fed, which has a critical supervisory role, but Better Markets has been writing a lot about the SEC lately, and there’s stuff happening there that’s barely being noticed. I’m barely seeing anything about it in the newspapers, and yet that’s just as important, right? There’s a lot going on at the Securities and Exchange Commission.Kelleher: So, the Securities and Exchange Commission was created in 1933. There were two laws: 1933 and 1934. And by the way, I should say if anybody’s really interested in this—I hate to sound like a book reviewer—but there’s some great stuff. Diana Henriques wrote a terrific book last year called Taming the Street, which is a history of the SEC, how it came about, why it’s so important, and what happened during the Great Depression. It’s also a history of the American economy, a bit like David Leonhardt’s book. And it’s an easy read.But the SEC regulates investor protection in our markets. And you asked this earlier, Paul: why should anybody really care given that so many of these assets are owned by the top ten percent? Well, as you know, we basically have an economy funding pipeline—a capital pipeline, if you will—in our economy. People all over the country come up with ideas, some of which fail and some of which succeed. Those that succeed need capital to grow so that they can take it from their garage to a local store, to a factory, and to global markets.Krugman: Right.Kelleher: When they start, they end up using angel capital or friends and family. Ultimately they get a good idea and a venture capitalist. And then the big success used to be your company would go public on the stock exchange. That’s how companies generated enormous amounts of capital—which is just a fancy word for money. They got enough money to grow their business, build things, and hire a lot more people. It’s how we built the middle class.And that’s what the SEC regulates: the public part of that capital pipeline—the big public markets like the New York Stock Exchange and the NASDAQ. They regulate both the disclosure obligations and they police those markets. They do that because what happened in the 1920s contributed mightily to the 1929 crash and the Great Depression. It was basically people who were lying, cheating, and stealing with almost no regulation at all. The big banks were often multi-headed financial conglomerates doing self-dealing and conflicts of interest. Not only didn’t they disclose things, but when they did, they often lied and defrauded people. A lot of that ended up being basically what we would think of today as Ponzi schemes—nothing really there except the people running the firms enriching themselves.The SEC was created to make sure we had well-regulated and well-policed markets so investors wouldn’t get fleeced, providing capital for businesses to grow. And until very recently, the SEC was the global gold standard for investor protection. Well, that’s gone. The SEC under Trump has now moved from investor protection to management protection. It is as captured as, unfortunately, the Fed in many respects. It is cutting back on disclosures and investor rights.For example, they’re even interfering with proxy advisors. It’s very difficult if you’re an investor to keep track of the proxies at all the public companies. The big investors have to vote on director appointments or major policy questions, so they hire proxy advisors, just like you would hire an advisor for anything else. Well, the SEC is now interfering with people hiring advisors to give them advice on proxies. How can you say I can’t contract with somebody to give me independent advice? They’re interfering with that because it makes investors more dependent upon management.Krugman: Just explain to me how that works. How is the SEC blocking that? I’m just curious because that sounds important.Kelleher: It is important, and the details are on our website. But at a very high level, there are two big proxy advisor firms that have a large amount of the market. And what you would do is hire them to provide tailored advice. For example, if you were interested in companies that were socially active and cared about the climate, you could tell your proxy advisor you want advice related to that. If you were on the other side and you loved fossil fuels, you could tell them that and the proxy advisor will tailor it to you. You then pay them, right? What the SEC said in one of its proposed rules—I’m not kidding—is that the proxy advisor had to submit any comment about a company to the company’s management, and management had the right to comment on it. Well, it’s the exact opposite of independent advice. How that’s even constitutional is beyond me.The proxy advisory firms have been engaged in litigation I believe in Trump I and in Trump two, about the restrictions that they’re trying to put on independent proxy advice. It’s just one example. I actually put out a report called The SEC is Demolishing Investor Protection, Threatening Capital Formation and the US Economy, which detailed many of the actions they’re taking.But the problem we have is that this isn’t just an issue for rich investors; it impacts the entire economy. One of the reasons people all over the world send their money to the United States capital markets is because they are well-regulated and well-policed. They’re not going to do that if those protections are gone. There’s already been reporting about people thinking about putting their money elsewhere. Now, because the US stock market is doing so well, you could argue it’s still a safe bet. By and large, there’s no other place that can compete robustly with the United States at the moment. Leave aside whether it’s a bubble or not. As an investment vehicle, it’s one of the top global places to put your money.Well, that’s because—and this is what they don’t get, Paul—they are well-regulated and well-policed. You take that away, and you’re going to end up with crooked, rigged markets where you don’t know what happens to your money. And if that happens, that doesn’t just hurt the rich people who own most of the financial assets. That’s going to have impacts all the way down the capital formation pipeline to the real economy and people’s jobs.Krugman: Okay. I was completely unaware that the SEC was doing all of that. But I just want to move on a bit. Better Markets has been writing quite a lot about crypto. Crypto has suddenly faded from public attention because there’s so much else going on, like AI. But crypto is still a two trillion dollar asset class. Talk to me about crypto and where it fits into all of this.Kelleher: Well, to start with, we have been the tip of the spear fighting crypto since 2020. We were the leading opponents of FTX and Sam Bankman-Fried back in ‘21 and ‘22 when he was trying to buy all of Washington and get his predatory model approved by the CFTC. In fact, we were so much of a thorn in their side that Sam called and came into the office for ninety minutes to try to convince me to support him. Unfortunately, there are so few people active at the CFTC, which is where he was trying to get his predatory model adopted.Krugman: This is Sam Bankman-Fried who came in to talk to you. Okay.Kelleher: Yeah, him and his bipartisan phalanx of advisors, because he bought everybody. For ninety minutes he tried to convince us. We didn’t know about his crimes obviously—but he clearly had an entire business model that was financially predatory. It was basically: “If we get rid of all these customer and investor protections, I can make a lot of money.” And I was like, “Well, anybody can make a lot of money.” You could make a lot of money building buildings if you don’t put in fire escapes or fire doors. It doesn’t mean it’s a good idea. That was essentially what Sam Bankman-Fried was trying to do in the derivatives markets, and we opposed him.He also thought he could bribe us; he offered us a million dollars or more. Frankly, I could have asked for twenty-five million bucks and I’m sure he would have delivered it in a paper bag. We said no. To my knowledge—and I don’t say this arrogantly, but in sadness—I think we were the only ones in Washington who didn’t take his money. He ended up in the right place.But Better Markets has been out front on this because there is no legitimate use case for crypto. They’ve had 18 years to come up with one. They keep throwing things up like “an inflation hedge” or “source of stability.” Every one of them has turned out to be baseless. The only real use for crypto is tax evasion, money laundering, and crime. It’s the preferred mechanism of choice for global terrorists, sex traffickers, and rogue nations like North Korea and Iran.You have to ask yourself why crypto has basically hijacked the political agenda of Washington. It’s because they followed the Sam Bankman-Fried model of buying bipartisan support by spending hundreds of millions of dollars in campaigns. And this is the astonishing thing, Paul, that people don’t know.Krugman: Okay.Kelleher: It’s the biggest bait-and-switch in history. In the hundreds of millions of dollars they spend on campaigns, they don’t mention crypto. That’s because they know crypto is toxic. Poll after poll shows crypto is toxic with the American people. Politico and the Wall Street Journal independently looked at the massive amounts of ads bought by the crypto industry supporting candidates in the United States, and not one mentioned crypto. Then they get their friends elected who come to Washington and say, “Crypto voters sent us here,” except not one voter voted based on crypto. They were mostly negative attack ads on extraneous issues.So crypto has now basically hijacked the agenda. The amount of attention politicians give it is crazy. The Senator from Maryland was recently quoted as saying, “I’m spending virtually all my time on crypto.” If his constituents knew that, they wouldn’t be happy. So here we have a financial product of no social use and massive negative uses that is being integrated with our core banking and financial system. Now, I’m sure it’s a coincidence, Paul, that the President is getting filthy rich on crypto.The problem is that the downside of crypto is not going to fall only on the people getting rich on it. Once they connect it up to the banking and financial system, which they’re doing across the board, we are going to see problems. In many ways, I think what’s happening now is worse than what happened before the ‘08 crash. Before the ‘08 crash, we had subprime. Well, we not only have financial craziness going on, we have this entirely new multi-trillion dollar financial product that has no value, is incredibly volatile, and is rife with conflicts of interest. It is going to be a core part of our banking system within the next twelve to thirty-six months.Krugman: Okay. This is a broader question of what happened to the political system. Massive campaign spending, but also a lot of effective bribery. You’ve been going after that. And it is kind of shockingly bipartisan. I mean, obviously, nobody has ever been “bribed.” The bribery of Donald Trump is, as he would say, “like nothing anybody’s ever seen before.” But it does extend across the political spectrum. You’ve been writing about that, right?Kelleher: Well, unfortunately, it has. Any ordinary person looking at what’s happening would think it was bribery. Unfortunately, it’s not technically bribery because the Supreme Court has made that almost impossible to prove in a political context. So we have politicians taking massive amounts of money from the crypto industry and then prioritizing their special interests over the American people. Poll after poll—and we have this on our website—shows that very few people in America use or own crypto. These are not our polls; these are from Pew and other non-industry sources. Even the FDIC and the Federal Reserve’s own surveys show this.If you look at the polls looking at what voters think, including one right before the 2024 election that looked at swing voters in six states, 68% of them had a negative view of crypto. That’s why crypto doesn’t mention crypto in its ads. But you have all this money coming into the political system, and now Democrats want that money too. Their view is: “Elections cost a lot of money. We need to neutralize this money cannon from crypto.”Therefore, they deliver for them so the industry doesn’t fire that money cannon against them—or better yet, gives them some of it. They do that directly through campaigns, independent expenditures, and Super PACs. They also do it through the revolving door where the industry hires former public officials, including Congressmen and Senators. They purchase them like you go to a vending machine. They give them a ton of money, and next thing you know, they’re mouthpieces for the crypto industry. They also hire lobbyists who are family members of very important people.There was a story that Senator Gillibrand’s twenty-two-year-old son has founded a company.That company is being funded by billionaires and other financial types because apparently he has a brilliant idea and they randomly found him in a phone book, Paul. Everybody is pretending it has nothing to do with the fact that his mother is a powerful Senator from New York who isthe leading cheerleader for crypto special interests. She also happens to be the chair of the DSCC—the Democratic Senatorial Campaign Committee—which raises the money to elect Senate Democrats.You can just read the media reports. You have to ask yourself: how are all these billionaires putting money into this startup? The spokesperson said these people are “longtime friends” of the son. When you’re twenty-two years old, how do “longtime friends” really work? Where do you run into billionaires? I know if you’re a Princeton professor they’re all over the place, but where I come from, running into a billionaire just isn’t common. Getting them to give you money for a startup at twenty-two might be the American Dream, but it ain’t working the way it’s supposed to.Krugman: I’m not a Princeton professor anymore, and there are very few billionaires at the City University of New York. But okay, there’s so much here. Any quick thoughts about AI? It’s monopolizing attention, but where is the financial side of that?Kelleher: I think in some ways it is monopolizing attention too much, and in other ways it’s not getting enough attention in the right places. We think that we’ve got a huge problem here. AI is inevitable; the real issue is what the safety features will be. Cars were a great innovation, but they killed a lot of people until we got airbags and protective glass. There is a fight now between people who think AI should proceed unregulated and those who think it should have regulation. We think you need a balance.The American people are on to this. They know it’s going to impact them. For one, these gigantic data centers are sucking up electricity and driving up bills, straining the electrical grid to the point where the entire country could be subject to blackouts. But also, AI is going to have a very big impact on whether you get a loan or at what rate. It’s not just your energy bill; it’s your local bank. When everything becomes automated, how does a community bank keep up?Community banks provide loans to the auto dealer or the local grocery store. They are going to come under enormous pressure because they can’t keep up with the infrastructure spending they’ll need. We have some ideas on how to strengthen them because they are so vital to our economy—providing 40% of small business lending. You lose community banks, you lose small business.And then there’s the gigantic banks’ use of AI with infrastructure and spending. Community Banks are gonna need to make major investments if they’re gonna keep up. I mean, as I said earlier, forty percent of the lending to small business in the United States comes from community banks. You lose community banks, you lose small business, you lose community. So that’s just one way, but it’s all the way up the chain.Another issue is that the people writing the algorithms are importing their own bias. Who’s guarding against that? There’s the “fat finger” problem where traders make mistakes, but who is testing AI machines pre-deployment? Representative Ro Khanna from California has made this point before, as have others. Truthfully, whether you like him or not, or you agree or don’t agree, you should listen to him because he’s got lots of thought provoking ideas on topical issues people really need to think about, and this is one of them.It’s like thinking: “Let’s open a nuclear plant in our neighborhood.” Everybody would say you wouldn’t do that without checking a million things first. AI is the same, if not worse, because it’s less visible. Better Markets is putting out a “people-centered agenda” on how we should find the right balance so we can get the best of AI while avoiding the bad parts—many of which are unknown. We shouldn’t be putting AI on autopilot. And you know, just like we’re not letting cars on the road running on autopilot without thoroughly testing them and making sure they’re not going to kill everybody. We sure as heck shouldn’t be putting out AI on autopilot.Krugman: Okay. This altogether makes me justifiably much more nervous.Kelleher: Then, let me end on an up note. I thought your piece this morning on jury duty service was interesting. I’m optimistic because the vast majority of the American people are reasonable and community-minded. The problem we have is that there’s so much money flooding into the system, and that money represents the extremes. The extremes are buying the political system. We need to figure out how to get more Americans involved so the reasonable people can have civil conversations. I do think most Americans agree on striking a balance within a reasonable range. Our problem is a Supreme Court empowering billionaires, and we have a president that doesn’t care about laws, norms, customs, or rules.What we’re trying to do at Better Markets—we just did this with our SEC campaign—is engage people. We engaged retail investors, and to our shock, two hundred thousand of them commented on an SEC rule. That is a historic high. So there are people out there, and we need to identify them and get them engaged. If we do, then I believe the core of the American Dream can be reflected in our political system.Krugman:I think that’s an upbeat note on which to end. Thanks so much. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 An Encouraging Encounter With Real Americans 10.07.2026 7minFor all my interviews and more, subscribe on YouTube.TranscriptToday i want to give you some encouraging news about the state of the heartland. Well, actually New Jersey, but you got a problem with that? But I did something kind of different yesterday — which has prevented me from producing a usual analytical Substack post — and it was actually a very uplifting experience.So hi, I’m Paul Krugman. What i did yesterday was participate in jury selection in Mercer County, New Jersey, where i am still a legal resident.That is something I’ve done before: back in 2020 I spent 16 weeks on a grand jury. It was done remotely, because it was the depths of Covid. It was a New Jersey grand jury, which is not high profile cases. It’s actually very ordinary cases in which the police want to bring someone to trial but 23 citizens must agree that they have provided sufficient evidence to bring the case to trial. You don’t have to judge guilt or innocence but you have to judge that there is sufficient evidence to warrant bringing charges. It was enlightening. I got to see a lot of the negative side of life, obviously, but it was just it was a pretty good experience on the whole.So I was summoned again this year. I wouldn’t have been able to do it, but I had to participate in the selection in order to explain to the judge, if necessary, why I could not be available during the period of this grand jury — a bunch of already agreed to conferences and talks in Europe.So it wasn’t going to be something I could do, but I did the right thing and went through the whole procedure of listening to the explanation, being pronounced present, and waiting to see the judge and explain the issue. Now, as it turned out, I didn’t even have to do that. By the time they had reached the people who had said they could not do it, including me and 77 other people, they already had filled the jury. So it ended up that it was time-consuming, okay, not a terrible thing, but it was a procedure that had to be done. And I did my citizenly duty and was released well into the afternoon.But what was interesting about it was that those of us who had said we couldn’t do it — 78 people in a Zoom room — had a long wait while the judge did whatever she needed to do with the rest. And after a little while some people unmuted themselves and we started having a conversation. This was by definition kind of a random sample of people — of course people who have felony convictions are not part of this, people are not us citizens are not part of it, and to be fair it’s Mercer County which includes Princeton although it also includes Trenton. Still, it’s on average an affluent, highly educated county so this was not exactly typical America but it wasn’t exactly the elite either: This wasn’t a virtual room full of Princeton professors.So conversation started. Obviously people are not fools so it wasn’t about politics, it wasn’t about current events, it started with people saying “anybody want to recommend some books that I should read?” and then turned to TV shows and movies and then somehow or other we got involved in a discussion of AI and applications and learning. Because there were several school teachers.Not everyone spoke up — most people didn’t — but everyone was listening, it seemed fairly attentively. And it was a great conversation! People were reasonable, they were either well informed or were happy to say “I don’t know about this.” There was actually some discussion about “how should I where should I go for news now that everything is so polarized” — nobody talked politics but they did talk about the fact that news is kind of hard to parse these days.The book recommendations, the TV and movie recommendations to the extent that I know them were pretty good. And the whole tone was, wow, it was civilized. I felt a little bit as if I was in the middle of a Norman Rockwell painting.By the way, yes, people did recognize me and a couple said you know I read your Substack and I talked a little bit but I made a deliberate effort to step back and not play the celebrity there.And that was good, because I got to listen to other people who were really level-headed, interesting, pretty well informed about a bunch of stuff. Oh, and just to say that this was New Jersey, so it was a very diverse group of people — a random selection of people from New Jersey, which meant that it was multi-racial and multi-ethnic. The clerk had some trouble with pronouncing everybody’s name, which was okay — I mean everybody was very forgiving of that.So it was very much America as I see it — a country of lots of people who look very different, who sound different (except a fair number of people did have New Jersey accents.)And it was just a far more hopeful scene — at least I found it much more hopeful —about the state of the country. It turns out that ordinary Americans — this is, again ordinary Americans from Mercer County, New Jersey, but still — ordinary Americans are a lot nicer, more thoughtful, more willing to hold interesting discussions than you might think.And it does seem to me, given all the political news, there’s a lot of people out there, I would say primarily on the right, but not only on the right, who fundamentally hold ordinary Americans in contempt, who believe that you have to go with cheap slogans and that you can appeal to the baser instincts of everybody’s nature and that’s the way that you win.And obviously they do sometimes win. But it’s worth going out there a little bit.I mean I’m never going to be the kind of person who travels around and has conversations with the person in the street and reports back on what I’ve learned about the real America. But I actually did have, by accident, a pretty good selection of real Americans — because we’re all real Americans — and came out of it feeling just much lighter in mood. You know, this country is actually okay if we can just get past some of the people who are trying to take us down a dark path. We’re not bad people — we’re mostly good people. And there’s a lot there’s a lot of uplift out here if you’re willing to see it. For once if I say I’m ending on a happy note, I really am.Take care. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
-
 The Pain in Spain is Mainly in Trump's Brain 08.07.2026 2minFor all my interviews and more, subscribe on YouTube.TranscriptYesterday, Donald Trump ordered Scott Bessent, the Secretary of theTreasury, to cut off all trade with Spain. Bessent said “Yes, sir.” Trump also said that this is because the Spaniards had stolen his strawberries. Okay, I made up that second part, but he did in fact order Bessent to cut off all trade. This is not going to happen.Presidents have a lot of discretionary authority on tariffs and trade, more than they should, but you do not have the right as president to impose tariffs on a country just because you don’t like their defense spending or you think that they haven’t been nice enough to you.So this would not fly even in the Trump administration. Even with a supine congress and a permissive Supreme Court this is not going to happen. Also Spain is part of the European Union. So this is like Europe declaring “we’re cutting off all trade with Florida”: they can’t do that. And also, there’s a lot of U.S. business with Spain. In fact, Spain is one of those countries with which we run a trade surplus. So U.S. business would be howling.So this is all a non-event, this is is not something that is real. Except that the President of the United States did say this. It was completely crazy, and that’s the story that we should be taking from this. It’s not really at this point about economics. It doesn’t even make sense to talk about Trump Administration policies, let alone ideology. What we have is President Sundowner. I mean, this this is completely insane stuff. In any kind of normally functioning political system, in any kind of normally functioning party environment we would have a massive bipartisan call across the aisle, across almost everybody except for a handful of members of congress who are themselves crazy, to say okay this guy is non compos mentis. We cannot leave the fate of the United States or the world in the hands of somebody who is completely irrational, who is making demands and believing himself to have powers that he does not. And of course, instead, not only does everybody pretend that he’s still a rational human being, but the Republican Party, the Trump administration, is full-on engaged in trying to build a personality cult.What this says to me is that the problem is a lot bigger than Trump. Something is fundamentally wrong with America, and at this point you don’t have to go through complicated justifications. You can just say something is wrong with a country and a system that lets this guy remain in a position of power.Have a good day. Get full access to Paul Krugman at paulkrugman.substack.com/subscribe
Samankaltaiset podcastit


Suosittu maassa
Tämä podcast esiintyy myös näiden maiden podcast-listoilla.


