
The Algorithmic Advantage
The Algorithmic Advantage
0
The Algorithmic Advantage is a podcast focused on quantitative trading and investing. It aims to expand the toolkit of the quant-trading community and introduce investors to the benefits of systematic trading. Through conversations with leading portfolio managers and other experts, it explores knowledge and experience in the field. The show seeks to educate and inspire listeners interested in algorithmic approaches to markets.
Episodes
-
 The Questions that Change Everything - Kris Longmore - 057 07.10.2026 1h 11mEx-prop trader on why solo trading is a different game, and how to win with real edges & portfolios of noisy strategiesKris Longmore of Robot Wealth went from aimless data mining to an equity partnership at a Sydney prop firm, all because a professional trader asked him one question: "What's your edge?" In this episode, he explains why solo trading is a completely different game from professional trading, and why success comes down to picking games you can actually win. We cover why keeping your day job isn't a failure, the two fundamental ways traders get paid, and how to build a portfolio in...
-
 Critical formulas for Bollinger Band trading - John Bollinger - 056 03.09.2026 1h 3mWhat does 46 years in markets teach you about building trading systems that actually last?John Bollinger joins me to discuss simplicity, robustness, volatility, market breadth, position sizing and why traders are paid to accept risk.We also cover Bollinger Bands inside Keltner Channels, price-pattern confirmation, geometric growth, risk of ruin, the danger of optimisation and why old systems can still be incredibly valuable.John even reveals a “secret sauce” trading system along the way.Write Up & Research: https://algoadvantage.substack.comCourses & Community: https://algoadvantage.io/collect...
-
 055 - Toby Crabel - Short-Term Futures Trading with Size! 14.08.2026 1h 43mToby Crabel — founder of Crabel Capital Management (~$5B AUM) and author of the legendary *Day Trading with Short Term Price Patterns and Intraday Breakouts* (1990), the book that gave the world the opening range breakout and NR4/NR7 patterns — joins the show for a rare, wide-ranging conversation. Toby traces his path from a pro tennis career to the Chicago trading floors, his formative stints with Victor Niederhoffer and his early connections to Monroe Trout and Paul Tudor Jones, and how zero-commission floor trading shaped his short-term edge from day one. He unpacks why the "clean open" tha...
-
 054 - Kieran Duff - Trading for a Living 20.07.2026 1h 13mTrading your own account was never going to replace a salary — the compounding you need gets wiped out by the withdrawals you need to live on. The more commercial option is to trade investor capital, but the options are limited.In this video we get a look inside a trader's journey with Darwinex, quickly establishing a track record and attracting external capital.In the Substack article I break down why prop firm evaluations are built for the firm to win, not you: daily loss limits, trailing drawdown, and consistency rules that quietly punish traders with genuine edge. I talk about why fixed st...
-
 053 - Martyn Tinsley - 2 of 2 - Walk Forward Correlation: A New Tool for Robust Strategy Design! 26.05.2026 1hBig discount on Martyn's tool for subscribers: https://www.algoadvantage.io/toolbox/Watch Part 1 first! https://youtu.be/Kxvp00VbLx0My detailed write up on Walk Forward Correlation Analysis: https://www.algoadvantage.io/podcast/053-martyn-tinsley-2/Martyn introduces Walk Forward Correlation (WFC) as a diagnostic for two problems that sit at the heart of systematic trading: over-fitting and structural edge. Traditional walk-forward analysis typically optimizes a strategy on an in-sample window, picks the “best” parameter set, then tests that one choice out-of-sample. Used the wrong way, there’s...
-
 052 - Martyn Tinsley - 1 of 2 - Building Robust Trading Strategies - The Masterclass 11.05.2026 1h 24mMartyn's process. Dealing with common trader pitfalls. Defining steps and methods for avoiding over-fitting."Opt My Strategy" the Robustness Testing Application built by Martyn Tinsley. Up to 25% off for Algo Advantage Subscribers!! https://www.algoadvantage.io/toolboxMartyn's paper on his new technique, "Walk Forward Correlation A Diagnostic for Over-Fitting and Structural Edge in Trading Strategy Optimisation": Our courses, community & toolbox: https://algoadvantage.ioContents:00:00 Introduction and Setup02:02 Martyn's Trading Journey12:07 Transition to Algorithmic Trading20:02 Common Pitfal...
-
 051 - Samir Varma - Classify Risk Don't Chase Alpha 14.04.2026 1h 3mWhat does a quantum physicist & inventor bring to quant trading? He thinks differently and is purposefully anti-alpha - instead focusing on risk management. After years of trying conventional risk models, Samir’s conclusion was not that risk is impossible to model. It was that most people are solving the wrong problem. They try to predict exact future risk levels. His approach shifted to classifying market states instead: when risk is low, be exposed; when risk is high, reduce or eliminate exposure.That is a profound change in mindset.Prediction asks for precision.Classification asks for usefu...
-
 050 – Samir Varma - When Academic Finance Theory Fails 06.04.2026 1h 7mWhere Real Edge in Quant Trading Actually Comes FromDo not watch this podcast. This is Part 1 with Samir Varma, and in Part 2 we go into great detail about his quantitative trading. In the Collective, he gives our members some specific instructions on how to measure risk differently – this stuff isn’t fluff. But in Part 1, I got derailed into quantum physics, determinism, AI, Asimov’s three laws of robotics and more. One of my favourite shows – but the first show I’ve done that isn’t about trading! It’s the warm-up you need to make the most of Part 2 though, and if I didn’t publish it, I’d be...
-
 049 - David Bush - Build a High-Performance Quant Crypto Portfolio Without Blowing Yourself Up! 26.03.2026 55mCrypto Trader's Edge Course: https://www.algoadvantage.io/academy/crypto-traders-edge/Most crypto traders are still thinking like coin pickers when they should be thinking like portfolio architects. High-performance systematic crypto trading is not about chasing narratives — it is about robust portfolio construction, trend following, mean reversion, risk management, alpha stacking, diversification, and building strategies that can survive extreme volatility.This pod with David Bush breaks down how to build a smarter algorithmic crypto trading portfolio using proven trading logic, better R&D, a...
-
 048 - Michael Wallace - Dynamic Position Sizing Like You Haven't Seen Before 09.03.2026 1h 7mThis interview with Michael Wallace (who was inspired by Larry Williams & Ralph Vince) brings a few things to mind. First is the absolute centrality of the role of position sizing in trading, second is the nature of ‘probabilities’ in trading. They are highly related obviously. Sizing is not an afterthought; it can change everything. Presuming an ‘average win rate’ is going to apply to your next 10 trades is not a wise way to proceed either. You want to be more ‘statistically minded’ than that – just toss a coin 10 times, and do that 10 times, the number of heads you get in each group of 10 is...
-
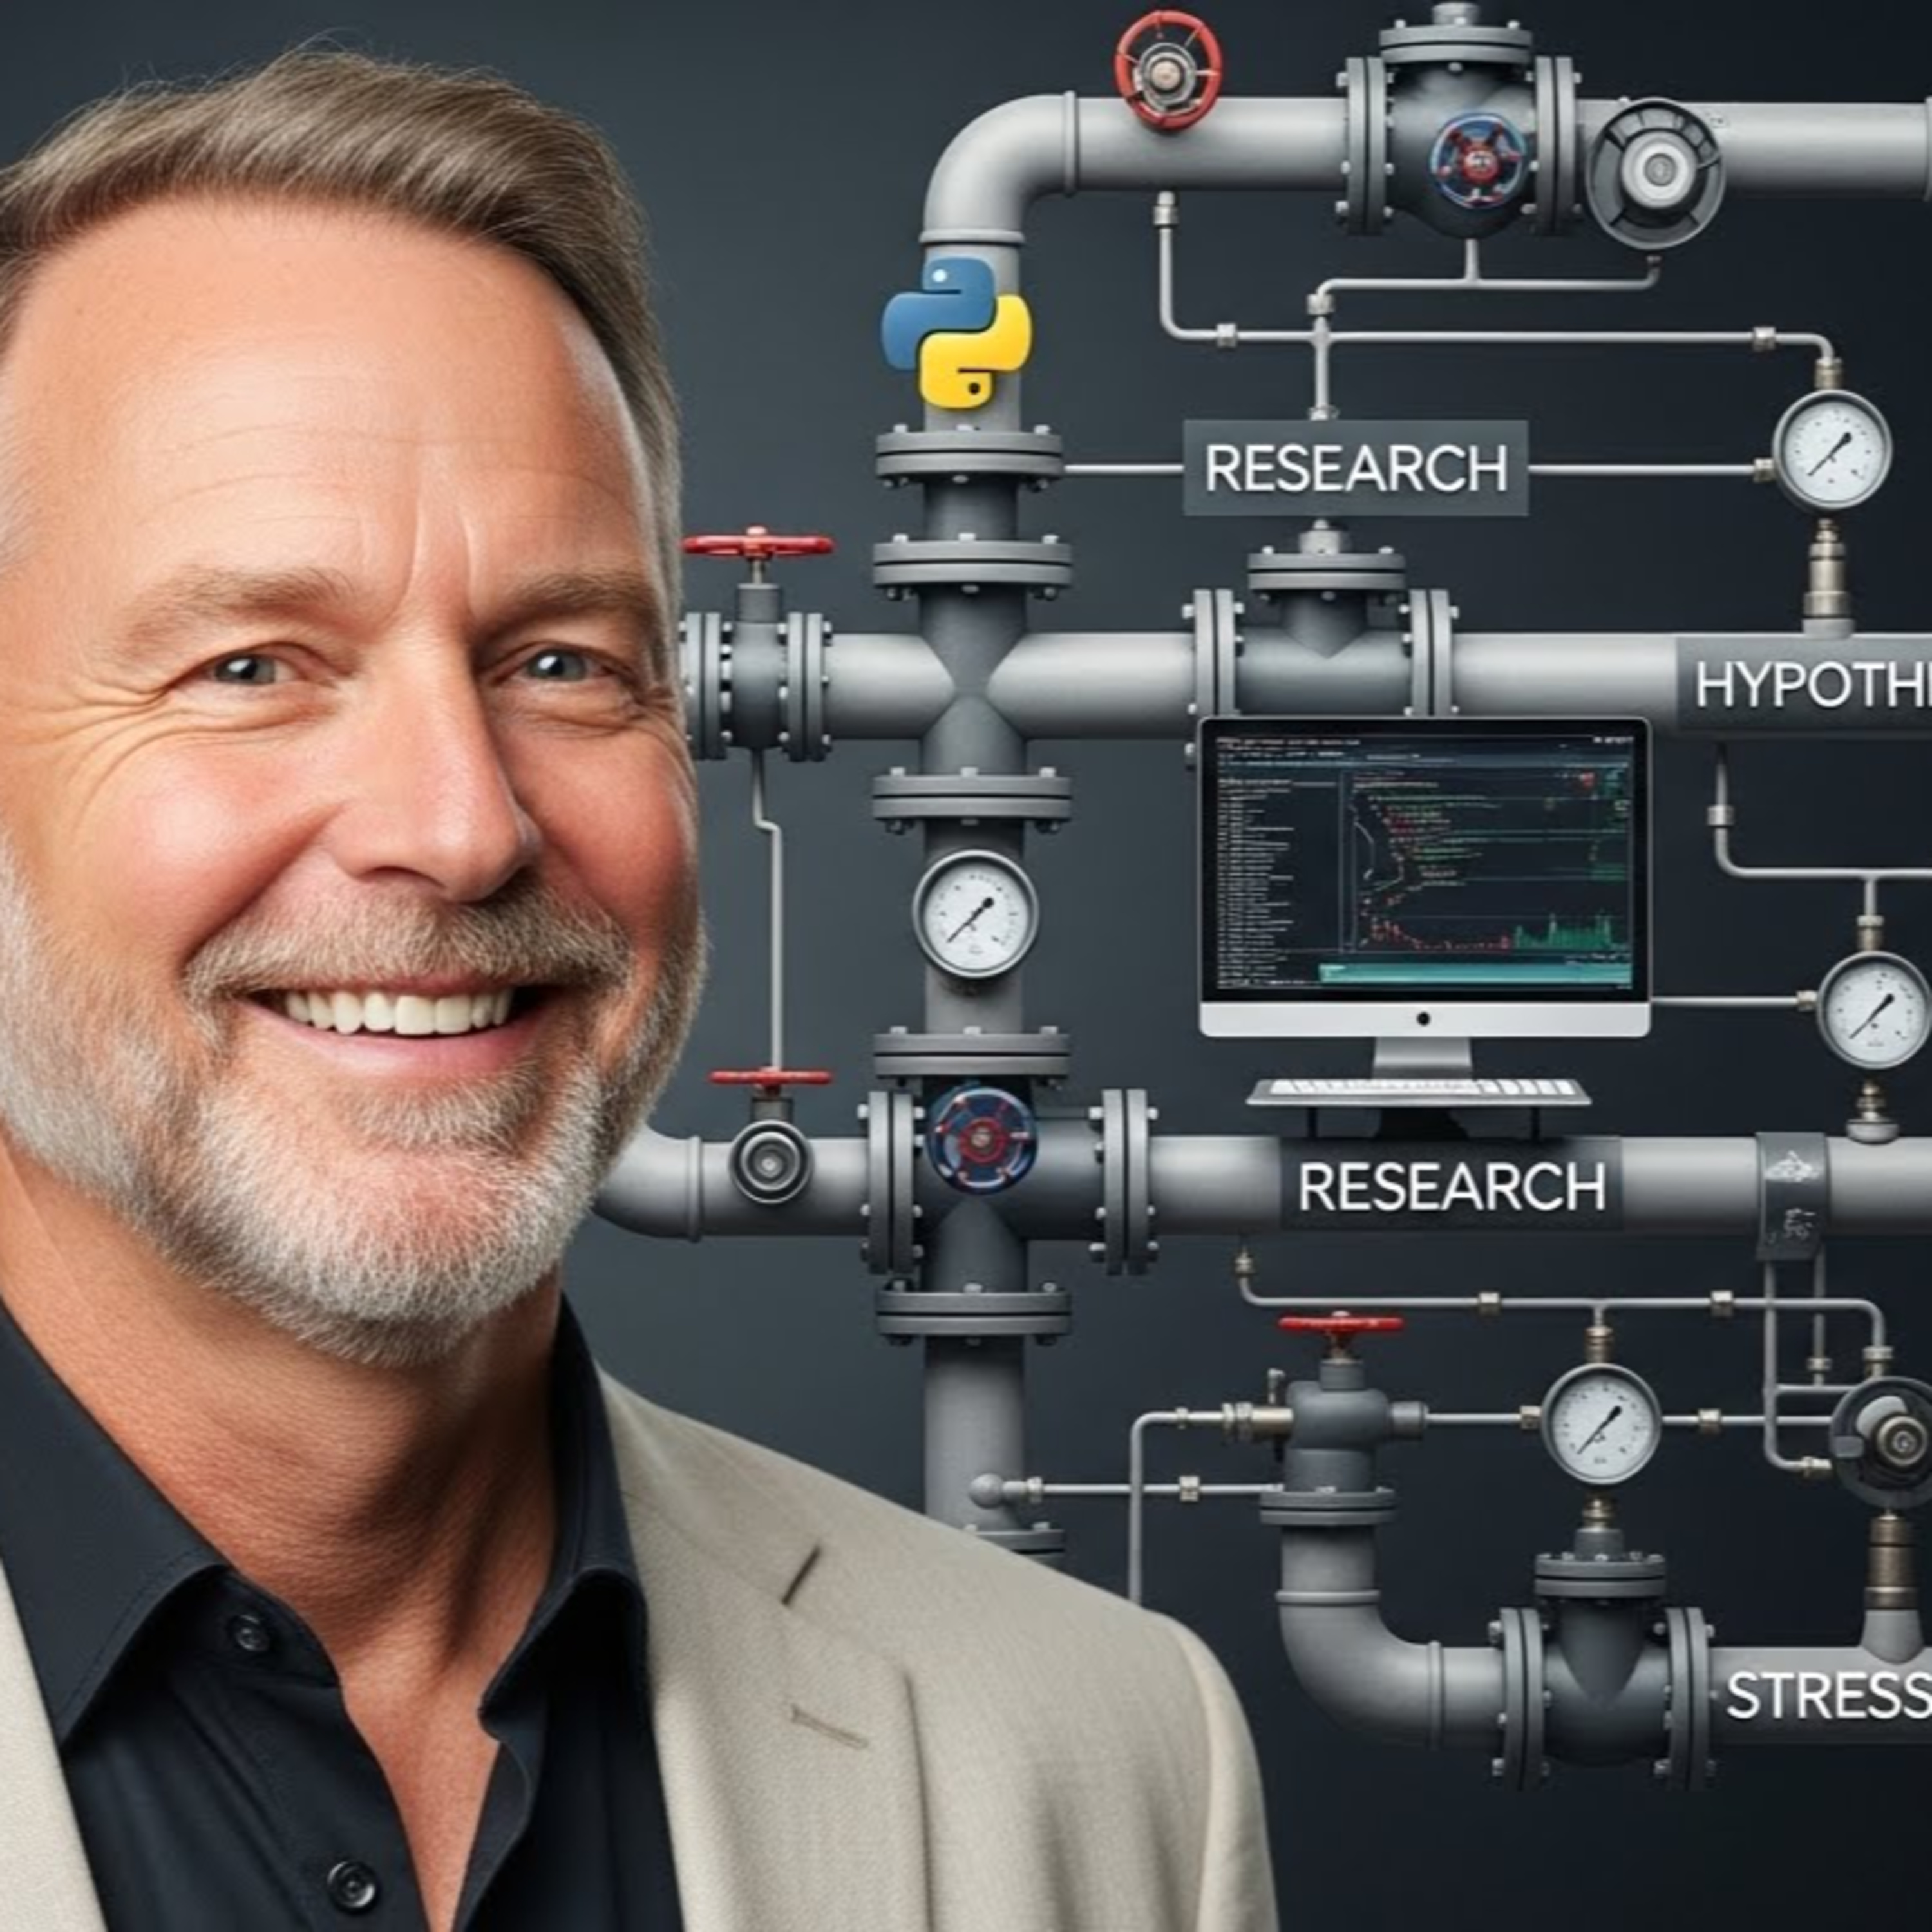 047 - Tom Starke - The Basics of Building a Strategy Development Pipeline 18.12.2025 1h 35mCourses, community & more: https://www.algoadvantage.ioThis is part II, part I is Episode 46.I know we all want “quick, actionable take-aways”, but the reality is that foundational principles of strategy development process is at the core of successful trading, and you more than likely do not have half of this in place like you should. So, while this is ‘foundational’, and can only be covered briefly, don’t skimp on reviewing this stuff. It’s only in the Algo Collective that we’ll be able to take the time to deep-dive how to set this all up in a highly practical way. Believe me, once you have...
-
 046 - Tom Starke - Institutional Quant Trading Fundamentals 11.12.2025 1h 45mDetailed write up on how institutions trade differently: https://www.algoadvantage.io/podcast/046-tom-starke/Part 2: coming soon!Dr Tom Starke trades significant institutional capital as a quant trader for a private fund. In Part 1, we cover the common pitfalls of 'retail' or newer traders. Tom makes the case that institutions 'think differently', applying an extra dimension to their thinking, as compared to retail traders. A significant result of this is the critical role a systematic R&D process plays in strategy development. The development pipeline is a 'research first', 'hypothesis testin...
-
 045 - Rob Hanna - Trading the VIX in a Diversified Portfolio 03.12.2025 1h 5mDetailed write-up on all of the concepts discussed here: https://www.algoadvantage.io/podcast/045-rob-hannaRob Hanna has been trading since the mid 90's and has slowly progressed from discretionary swing trading to a systematic, research driven approach, while still carrying some of those qualitative features into his quant trading. He trades a diversified set of strategies in equities and ETFs, with a focus on the shorter term (and particularly mean-reversion) models. Of particular interest to me was his VIX trading strategies due to their usefulness as a hedge in times of crises, and because...
-
 044 — Nick Radge: Want Big Fish? You'll Need a Bigger Rod 28.10.2025 1h 30mI think Nick Radge’s edge is actually an architecture: robust, simple, momentum-driven systems stitched together into a portfolio that survives, adapts, and compounds. Across nearly four decades, he’s traded through crashes, chop, and melt-ups; shifted from futures to equities for business reasons; and kept his build-process stubbornly logic-first and comfortingly boring—by design. The pro vs amateur divide, per Nick: pros ride the drawdowns and are present for the next outlier. They profit from human bias—fear, greed, crowding—by refusing to trust their own emotions and by outsourcing discret...
-
 043 - Brent Penfold - Can Pre-Historic Strategies Still Make 30%pa? 01.10.2025 1h 49mCan caveman-simple trading rules still work in today’s markets? Brent Penfold says yes. In this interview, he reveals why old strategy rules remain powerful, why portfolio-level thinking is the real edge, and how diversification and discipline create timeless success.Brent talks about trading patterns in a range of 30 futures markets, deploying 20 strategies diversified across mean reversion and trend following principles. I write an article inspired by each podcast which are full of my insights and practical tips. Check them out on the website: https://www.thealgorithmicadvantage.comLinks for...
-
 042 - Laurens Bensdorp II - Building Strategies with Purpose 21.08.2025 1h 27mRound II of a systematic trading masterclass with Laurens Bensdorp: architect non-correlated, purpose-built portfolios—mix trend following, mean reversion, and long-volatility hedges to drive smoother, higher risk-adjusted returns.We unpack the “paradox of diversification” (Parrondo’s paradox) to turn “ugly” equity curves into compounding machines, and when (not) to switch systems off to avoid recency bias and overfitting.Plus: robust portfolio construction, capital allocation, and highlights from Laurens’ latest book, Trading Retirement Accounts.Combining losing investments into a winner:http...
-
 Episode 041 - Cesar Alvarez - A Novel Way to Combine Trend, Reversion, ETFs, Volatility & More! 13.06.2025 54mDive into the deep experience of quantitative trading with Cesar Alvarez (trader first, martial artist second), a veteran trader known for his mastery in mean reversion, breakouts, momentum, ETF and volatility strategies. Discover his innovative methods building a dynamic portfolio, retiring strategies, parameter sensitivity tests, strategy robustness checks, and the art of balancing risk and return to ensure long-term trading success. Cesar’s insights highlight essential strategies for thriving in volatile markets, fine-tuning strategy components, and avoiding the trap of overfitting. Perfect...
-
 040 - Pavel Kycek - Generating Insane Returns with Quant Crypto Trading 27.05.2025 1h 16mA Smart Portfolio of Trend Following, Mean Reversion & Hedging StrategiesUnlock insane returns with quant crypto trading! Discover how Pavel from Robuxio builds robust portfolios combining mean reversion, momentum, and hedging strategies—even with limited historical data. Learn essential techniques for managing crypto volatility, optimizing execution, and leveraging diversified strategies. Curious? Dive into the show! #QuantTrading #CryptoTrading #Momentum #MeanReversion #Hedging #AlgorithmicTrading #CryptoStrategies
-
 039 - Brett Steenbarger - Mental Keys to Quantitative Trading Success 16.05.2025 58mPsychology for Quant Traders? Really?Quantitative futures traders like to think in code, not clichés—but Dr Brett Steenbarger makes a compelling case that mindset is part of the edge. In this interview, Brett argues that the same statistical rigor quants apply to markets should be applied to the grey matter behind the keyboard. Here's a guide for the advanced systematic trader who suspects “psy-stuff” might be more than motivational posters.The punch-line from Brett’s research is simple: systematic trading is less “set-and-forget” and more Formula 1 pit-crew—engineering precision plus real-ti...
-
 038 - Andrea Unger - 672% Returns? Sure! Would You Like Some Risk with That? 07.05.2025 1h 46mFinishing our little mini-series on shorter-term futures trading we talk to Andrea Unger and happily inject some click-bait in the form of gloating about his 672% return in a single year when he won the World Trading Competition. Naturally, we know that this kind of return is generated by specifically trying to win the comp, and taking on the associated risks! If you've been asleep the first two guests in this series were Bob Pardo and Kevin Davey. Between the three we've got a complete masterclass in shorter-term, diversified and responsive futures trading!Andrea Unger is actually a four-time...
Similar podcasts


Popular in
The podcast also appears in the podcast charts of these countries.
